
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Strong Margins And Low P E Altering The Investment Case For Gulfport Energy Stock?
- Gulfport Energy has reported a ten year track record of 10.8% annual revenue growth, a 70.9% gross margin, and a 17% free cash flow margin, alongside a current valuation of 7x forward P/E.
- This mix of high profitability and free cash flow provides Gulfport Energy with multiple options for funding drilling, land acquisitions, and shareholder returns, while the shares trade on a comparatively low earnings multiple.
- We will now assess how Gulfport Energy’s combination of strong margins and a 7x forward P/E could influence its broader investment narrative.
Compare Gulfport Energy’s mix of high margins and a 7x forward P/E with other profitable resource stocks using our curated list of 33 high quality undervalued stocks.
Gulfport Energy Investment Narrative Recap
For an investor to back Gulfport Energy, the belief needs to be that its 70.9% gross margin, 17% free cash flow margin and Appalachia inventory can keep supporting disciplined drilling even if gas markets stay choppy. The key near term swing factor is commodity pricing and demand, which directly affects how quickly the firm can convert that inventory into usable cash.
The biggest immediate risk is that weaker gas prices or a 2027 demand soft patch limit the value of those roughly 15 years of identified locations. Ongoing discretionary Ohio Utica acreage spend also matters, because if returns on those higher cost parcels disappoint, it could pressure earnings and narrow that margin profile.
Recent commentary around Gulfport Energy’s roughly US$140 million of planned discretionary land purchases in 2026, including US$83 million already committed in an Ohio auction, is central to the current story. This program adds about 20% more Appalachia locations, which ties directly into any thesis that the business can sustain its output and margins over time.
For you as a shareholder, the question is whether execution on those new Utica and Marcellus locations plus ongoing drilling efficiency gains can outweigh the flagged risks around gas fundamentals. Any progress on lowering drilling and completion costs, keeping net leverage in check and optimizing transport contracts will likely shape how quickly the 7x forward P/E re rates relative to operational delivery.
Gulfport Energy’s current analyst narrative points to revenues of US$1.7b and earnings of US$531.7 million by 2029, based on an assumed 7.9% yearly revenue growth rate and an earnings increase of about US$44.6 million from US$487.1 million today.
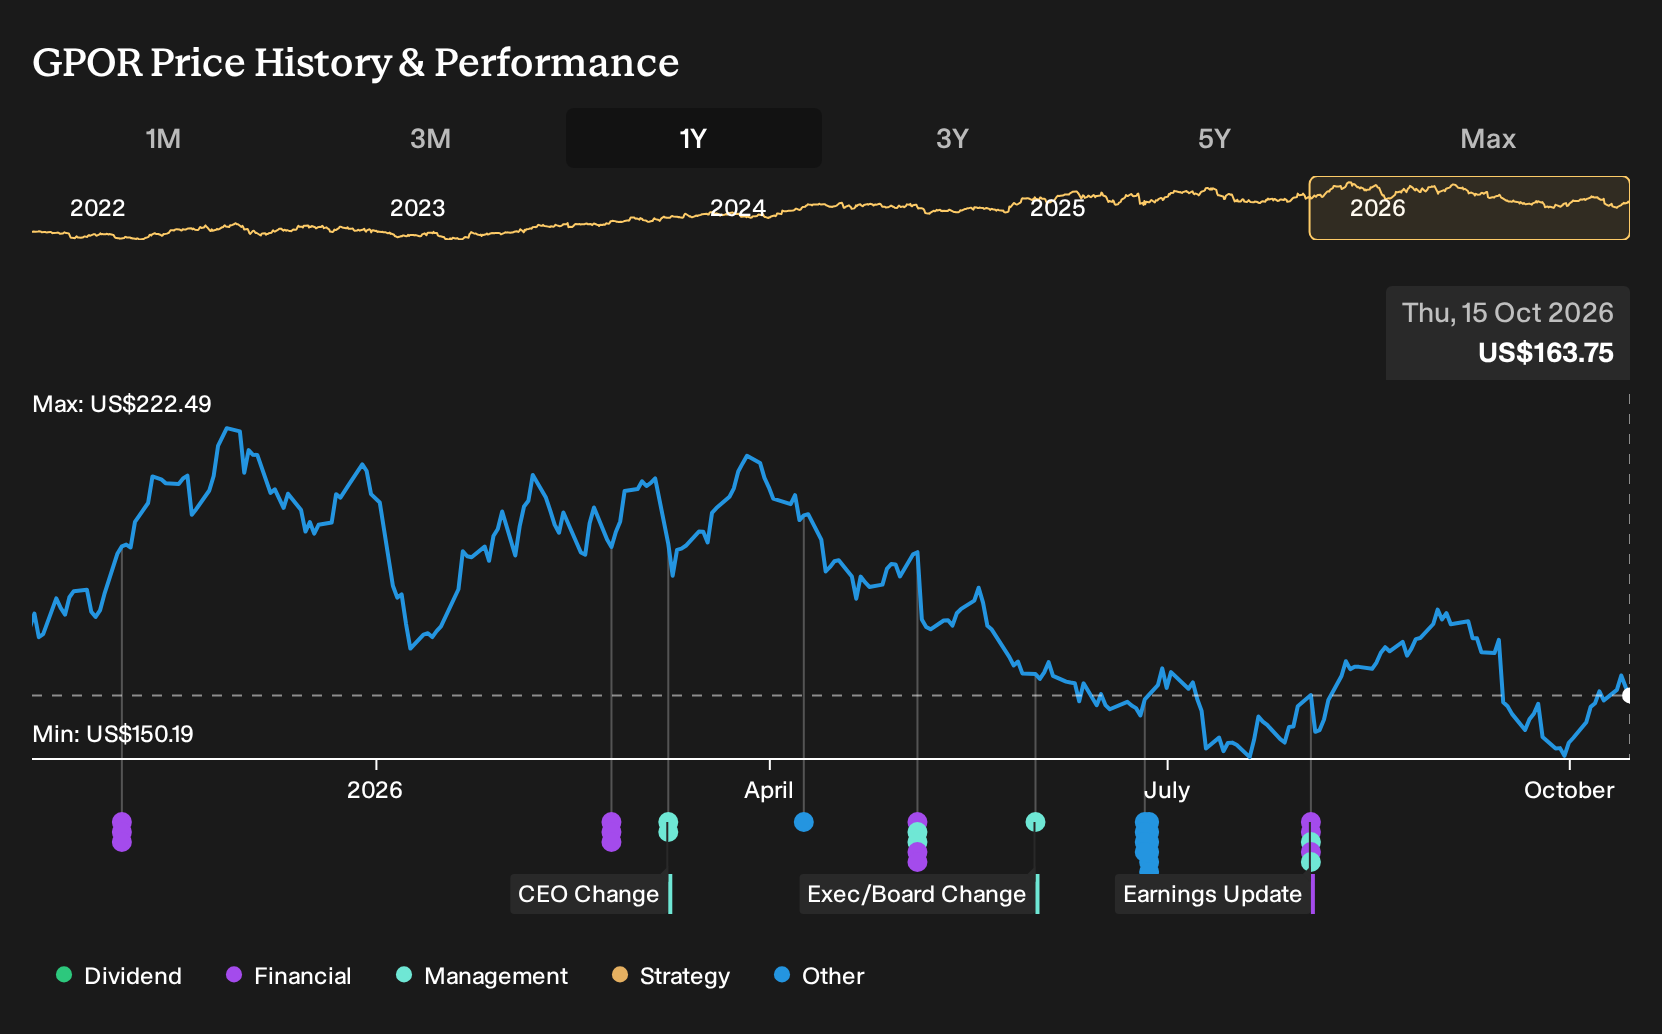
Uncover why Gulfport Energy's fair value indicates a 31% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly US$215 at the low end and just over US$1,034 at the high end, which shows how far apart retail views on Gulfport Energy can be. You are weighing that spread against risks around gas demand and discretionary acreage spend, so it helps to explore several alternative viewpoints before leaning on any single narrative.
Explore another Gulfport Energy fair value estimate, including one that suggests it could be worth just $214.85!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Gulfport Energy research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Gulfport Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Gulfport Energy's overall financial health at a glance.
Looking For More Investment Ideas Beyond Gulfport Energy?
If you like the mix of margins, cash generation and valuation that Gulfport Energy offers, it can help to compare it with other stocks that show different combinations of quality, balance sheet strength and income potential. The Simply Wall St Screener lets you quickly filter for these traits so you can build a watchlist that matches your own investing style.
- If you want potential upside with tighter financial discipline, start with a 32 resilient stocks with low risk scores that may appeal if capital preservation ranks high on your list.
- For investors who care about steady operations and robust finances, consider a list of solid balance sheet and fundamentals (25 results) that can help surface companies with stronger cushions against shocks.
- If you are hunting for opportunities that are not widely followed, use a 20 high quality undiscovered gems that highlights stocks with solid fundamentals but less crowded attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com