
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Groupe Dynamite And 2 Canadian Undervalued Stocks To Watch
Global markets are reacting to renewed inflation worries and shifting central bank policies, which puts the spotlight on one thing that tends to matter most over time: cash coming into a business. When share prices lag behind the cash those companies are expected to generate, value gaps can appear. This article looks at three Canadian stocks where projected cash flows suggest more value than the market price implies.
The three stocks below are a short list pulled from a wider universe of ideas, and the full screen surfaced 5 more companies with equally cash-rich stories that are not covered here.
If you want to go beyond this sample and focus on opportunities that match your own risk and return checklist, head straight into the Undervalued Stocks Based On Cash Flows screener to identify, analyze, and prioritize the highest-conviction plays for undervalued cash flow potential.
Groupe Dynamite (TSX:GRGD)
Overview: Groupe Dynamite is a fashion retailer that designs and sells women’s clothing and accessories through Dynamite and Garage stores and e-commerce.
Operations: The business generates about CA$1.49b in retail apparel revenue, with roughly CA$903 million from the United States and CA$579 million from Canada.
Market Cap: CA$6.43b
Groupe Dynamite matters for this cash flow focused screen because its women’s fashion stores and online channels convert everyday apparel demand directly into operating cash that can be lined up against SWS DCF fair value estimates.
"Rapid expansion in the United States and early traction in the United Kingdom, including Oxford Street and other prime centers, positions Groupe Dynamite to reach more higher income shoppers and tourists, which can support sustained revenue growth and higher sales per square foot."
What happens to that cash flow story if a single pressure on pricing power or markdown discipline starts to shift?
If that pricing pressure ever bites, you will want the full context in the full narrative for Groupe Dynamite to see how cash generation and valuation could decouple.
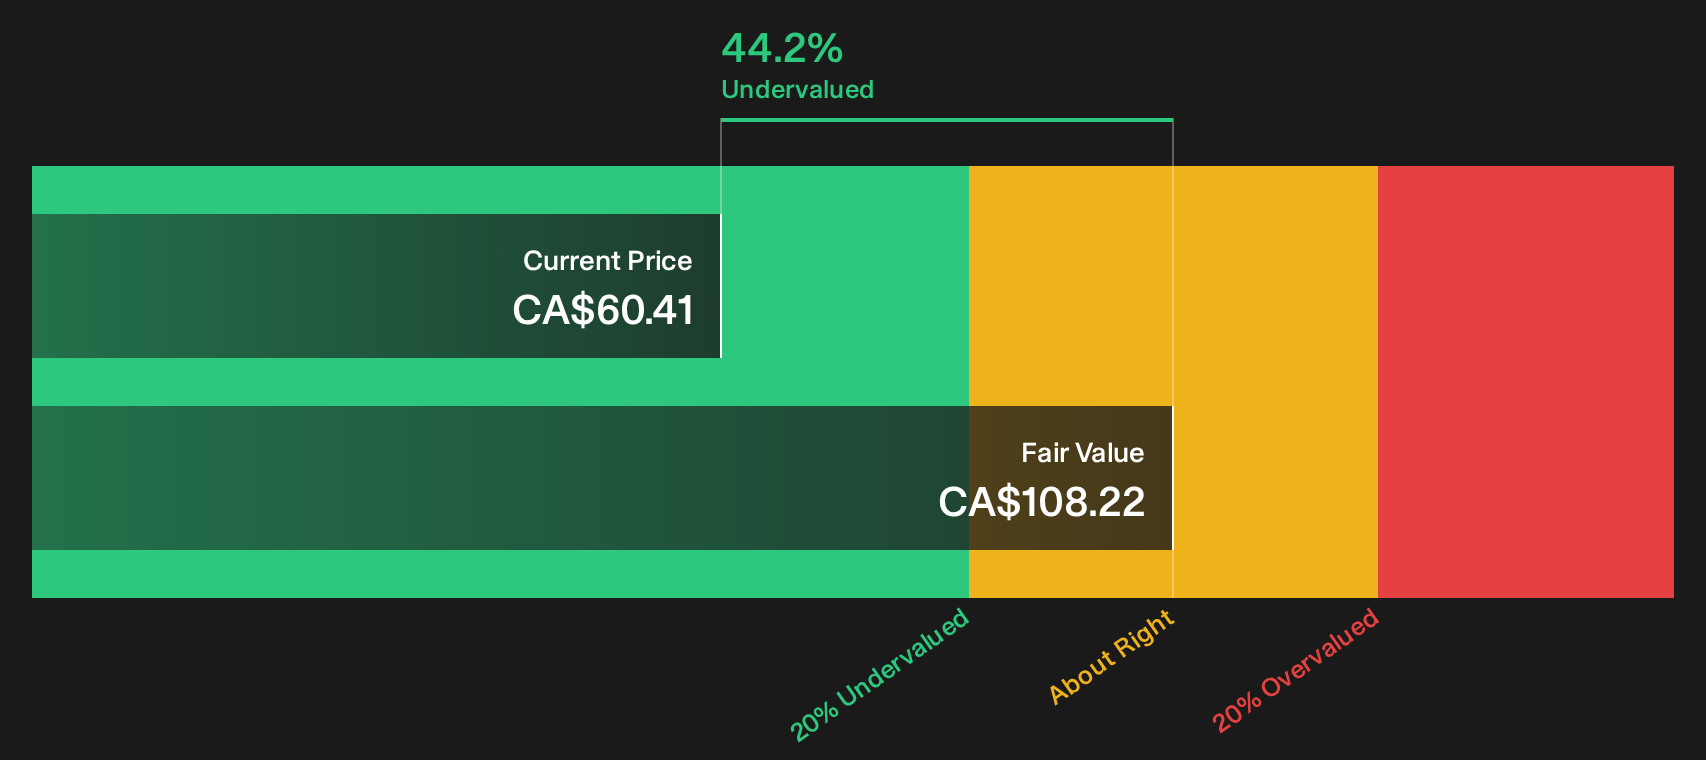
Stantec (TSX:STN)
Overview: Stantec provides engineering and consulting services for infrastructure and water systems, helping public and private clients plan, design, and manage critical assets.
Operations: The business generates about CA$3.56b from the United States, CA$1.7b from global operations, and CA$1.56b from Canada.
Market Cap: CA$10.74b
Stantec matters for this undervalued cash flow screen because its long term water and infrastructure consulting contracts can support steady, visibility rich cash generation that can be weighed directly against SWS DCF estimates.
"Demand for infrastructure upgrades, water/wastewater treatment, energy transition, and climate adaptation projects remains exceptionally strong globally, with double-digit organic growth and a $7.9 billion backlog, which the company believes positions it for sustained revenue expansion."
The real tension for Stantec is how that healthy backlog filters through to margins if a single cost pressure starts to bite.
If that margin squeeze ever starts to bite, the full narrative for Stantec shows how Stantec’s backlog, pricing power, and capital allocation could still accelerate value creation.
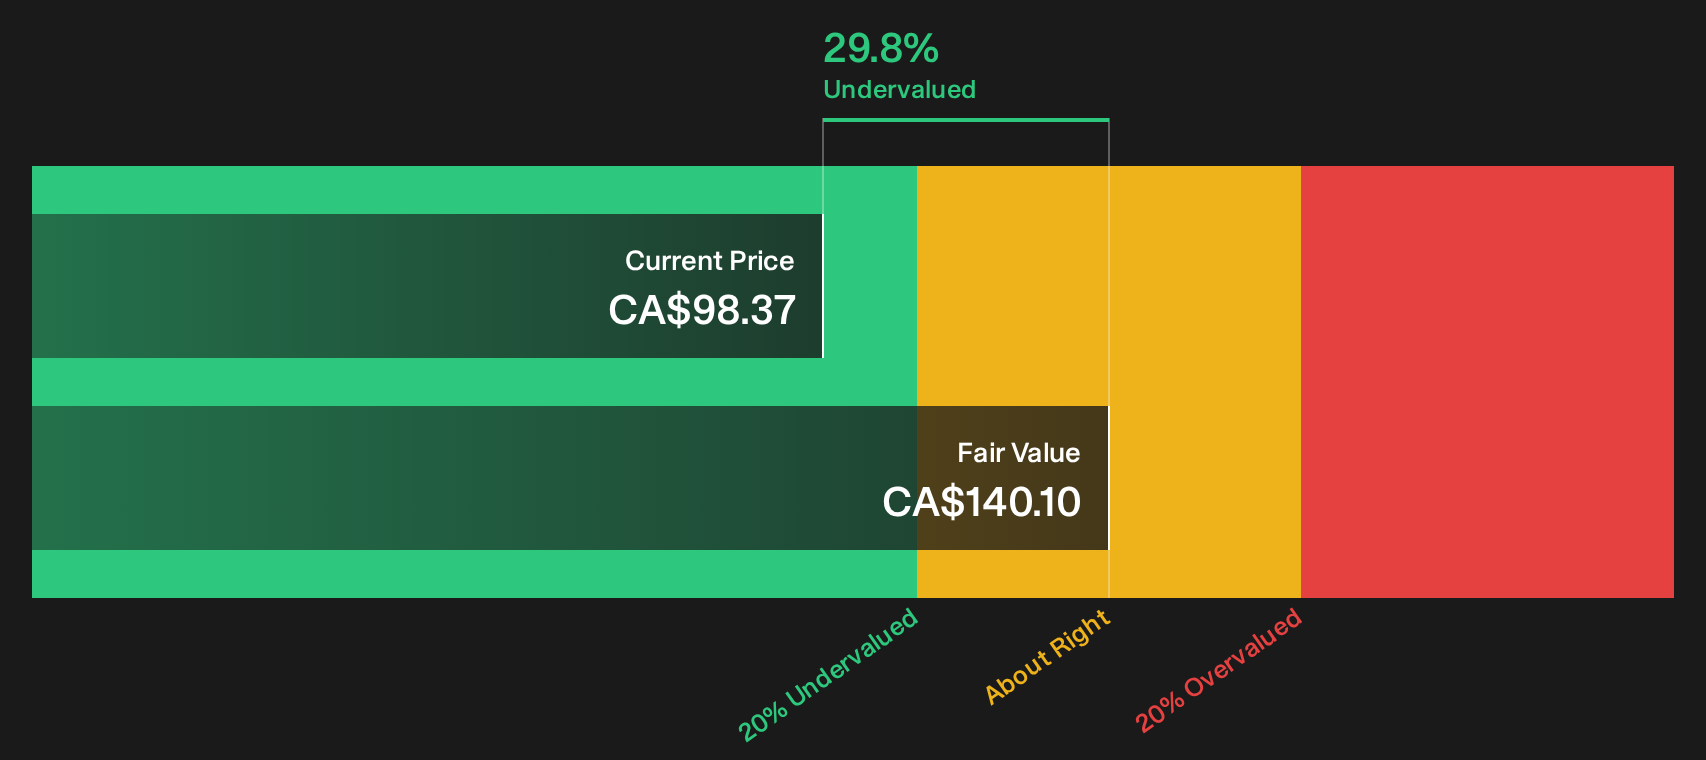
Hudbay Minerals (TSX:HBM)
Overview: Hudbay Minerals is a diversified miner focused on copper concentrate production at Copper Mountain, with additional gold, zinc, silver and molybdenum output across the Americas.
Market Cap: CA$15.32b
Hudbay Minerals matters for this undervalued cash flow screen because its Copper Mountain and Copper World projects concentrate future cash generation in copper heavy production, which is exactly what discounted cash flow models focus on when comparing operating potential to market pricing.
"The Mitsubishi joint venture at Copper World brings US$600 million of partner funding, cuts Hudbay’s estimated remaining capital share to about US$200 million and pushes its first major cash outlay to 2028. Once Copper World is operating, Hudbay expects annual copper output to be more than 50% above current levels, with over 70% of consolidated production and revenue coming from copper."
What happens to that cash flow story if a single cost or execution pressure starts to eat into the copper rich margin profile investors expect?
If that pressure is what worries you, read the full narrative for Hudbay Minerals to see how Hudbay Minerals balances copper heavy ambition, execution risk, and potential upside re rating.

Seeking Alternatives Before The Crowd
Fresh ideas move first. By the time momentum headlines hit, early entry points are already flying. Scan these under the radar lists while it matters and get in early.
- Spot cash generative outliers before they trend by running 6 high quality undervalued stocks while they are still under the radar and expectations have not fully caught up.
- Track capital flowing into digital assets by scanning 19 cryptocurrency and blockchain stocks and see which listed plays are catching real business traction, not just price hype.
- Focus on resilient balance sheets and durable cash flows through the curated list of solid balance sheet and fundamentals (8 results) to avoid scrambling after the market has already repriced quality.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com