
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
CSX (CSX) Starts Leadership Transition, Is The Stock Still Below Fair Value?
CSX (CSX) just kicked off an important leadership transition, with longtime rail operator Michael A. Cory retiring as executive vice president and chief operating officer on October 12, 2026.
Investors have already been pricing in this reshuffle at CSX, with the stock at US$48.69 and a strong year to date share price return of 34.24% and a 1 year total shareholder return of 37.03%. This points to momentum that has cooled in the last quarter, as the 90 day share price return declined 4.06% going into the dividend affirmation, upcoming earnings report and leadership transition.
Spot emerging rail and infrastructure plays responding to leadership shifts like CSX by scanning our curated list of list of solid balance sheet and fundamentals (25 results).CSX has already delivered a strong run with double digit gains over 1 and 3 years. The real question now is whether valuation still leaves meaningful upside ahead or if most of the move is already in the rear view mirror.
Most Popular Narrative: 8% Undervalued
On the prevailing narrative, CSX is worth $53.10 a share, which sits modestly above the latest $48.69 close and frames the stock as slightly undervalued rather than mispriced in either direction.
The current valuation suggests that the market is not fully reflecting this narrative’s view that CSX may be undervalued relative to the earnings power indicated by recent margin changes, intermodal activity and the industrial development pipeline.
The industrial development pipeline of roughly 600 active projects, with about 100 expected to enter service in 2026 and provide significantly more volume at full ramp than the prior year cohort, is poised to add new carloads that support merchandise and bulk revenue and help operating leverage.
See why 25 investors see CSX as 8% undervalued.
Result: Fair Value of $53.10 (UNDERVALUED)
Still, the CSX story can change quickly if crew shortages strain service again or if tougher safety and access rules increase operating costs.
Find out about the key risks to this CSX narrative.
Another Angle On CSX Valuation
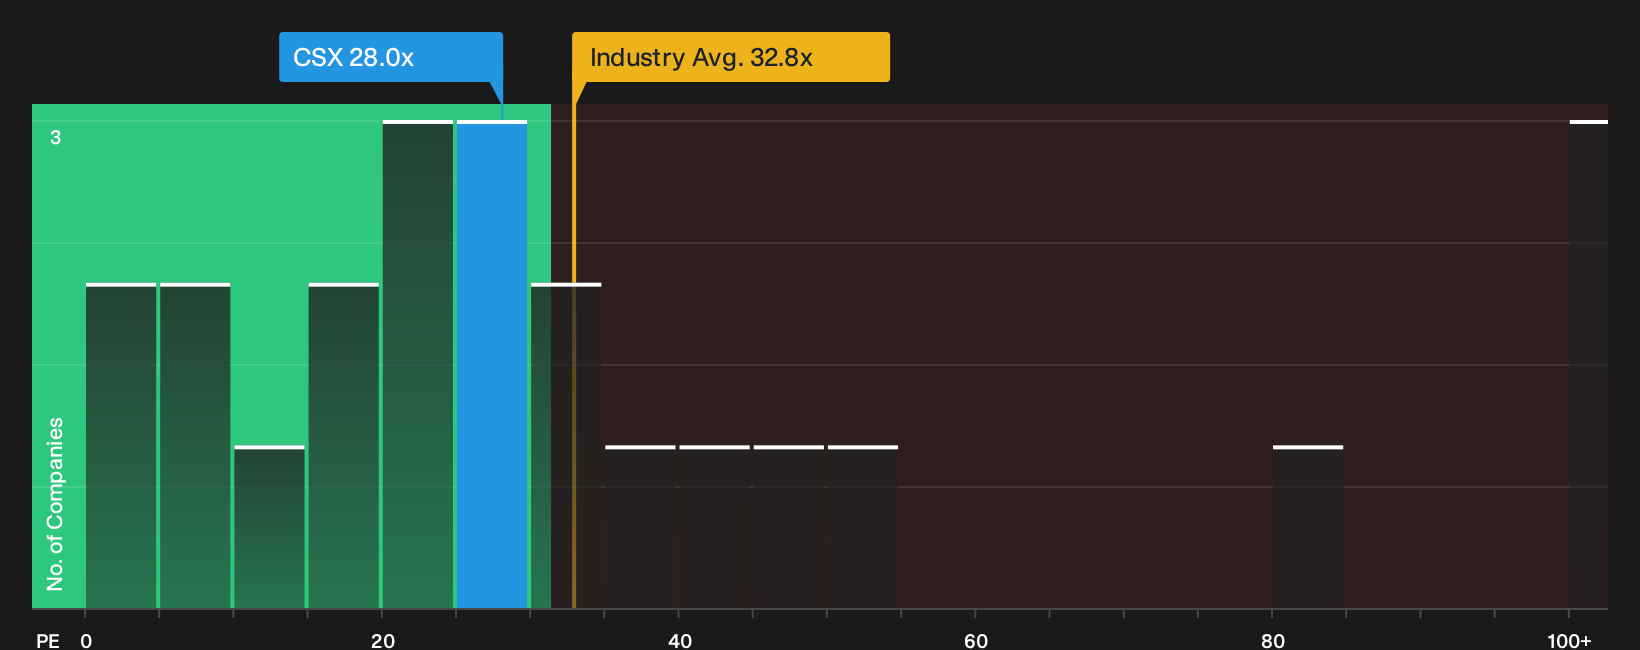
The analyst narrative points to CSX trading modestly below a fair value estimate around $53.10. The market is telling a different story on simple earnings math. At a P/E of 28x, the stock trades below the US Transportation average of 32.8x, yet above a fair ratio of 20.6x. That mix of relative discount and absolute premium raises a sharper question: Is this pricing a cushion for rail quality or a valuation risk if expectations tighten?
Our earnings based view leaves room for more detailed work with our valuation tools, especially if you want to see how different assumptions interact in practice. See what the numbers say about this price — find out in our valuation breakdown.
To cross check how CSX trades against its industry on this metric over time, review the latest valuation chart for extra context.
Next Steps
Sentiment around CSX is split between concern about risks and optimism about potential rewards. Move quickly, review the data yourself, and weigh the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond CSX?
CSX offers one angle on the rail story, but your portfolio may benefit from a wider set of opportunities that match different goals, risk levels, and income needs.
- Target potential mispricing across quality businesses by scanning the 33 high quality undervalued stocks that currently clear strict fundamentals filters.
- Strengthen your defense with the 32 resilient stocks with low risk scores that pair resilient balance sheets with more measured volatility when markets turn choppy.
- Expand your income options by reviewing the 8 dividend fortresses built around higher yields that still rest on financial strength and cash generation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com