
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Duolingo (DUOL) Jumped, But What Is Driving Attention Now?
Robbins Geller Rudman & Dowd LLP has filed a securities class action against Duolingo (DUOL), spotlighting how its ad load, subscription upsells, and AI driven content choices may have affected user trends and investor communications.
Against this backdrop, Duolingo’s share price has been volatile. The stock gained 6.58% in one day to reach US$148.93 after the lawsuit news, following a 30-day share price return of negative 3.24% and a 1-year total shareholder return of negative 54.95%. This combination points to fading longer term momentum despite occasional short term bounces.
Spot opportunities beyond Duolingo by scanning a hand picked 20 high quality undiscovered gems that could be flying under most investors’ radar.Duolingo shares just jumped after sharp longer term losses, so rushing in now feels very different from waiting for a reset. Does this legal overhang justify patience, or does the recent swing already reflect the risks?
Most Popular Narrative: 11% Overvalued
Against a last close of $148.93, the most followed narrative anchors Duolingo’s fair value at $134.29. This implies the stock trades at a premium based on that framework and a 7.29% discount rate.
The numbers and current valuation imply that Duolingo is fairly valued with a bearish skew, with recent stock price weakness already reflecting concerns about slower bookings growth, lower gross margin guidance and the costs of its AI and subject expansion.
See why 169 investors see Duolingo as 11% overvalued.
Result: Fair Value of $134.29 (OVERVALUED)
Still, that playbook could crack if daily user trends in mature markets fade, or if China related AI restrictions keep delaying higher margin products.
Find out about the key risks to this Duolingo narrative.
Another View: SWS DCF Signals Undervaluation
The analyst narrative tags Duolingo as roughly 11% overvalued at a fair value of $134.29, yet the SWS DCF model paints a very different picture. On that cash flow view, Duolingo’s estimated value sits at $303.05, which puts the recent $148.93 share price at a steep discount. Which story do you think deserves more weight?
Before leaning too hard on either lens, it helps to understand how the SWS DCF model works in practice and what assumptions sit underneath that $303.05 figure. Look into how the SWS DCF model arrives at its fair value.
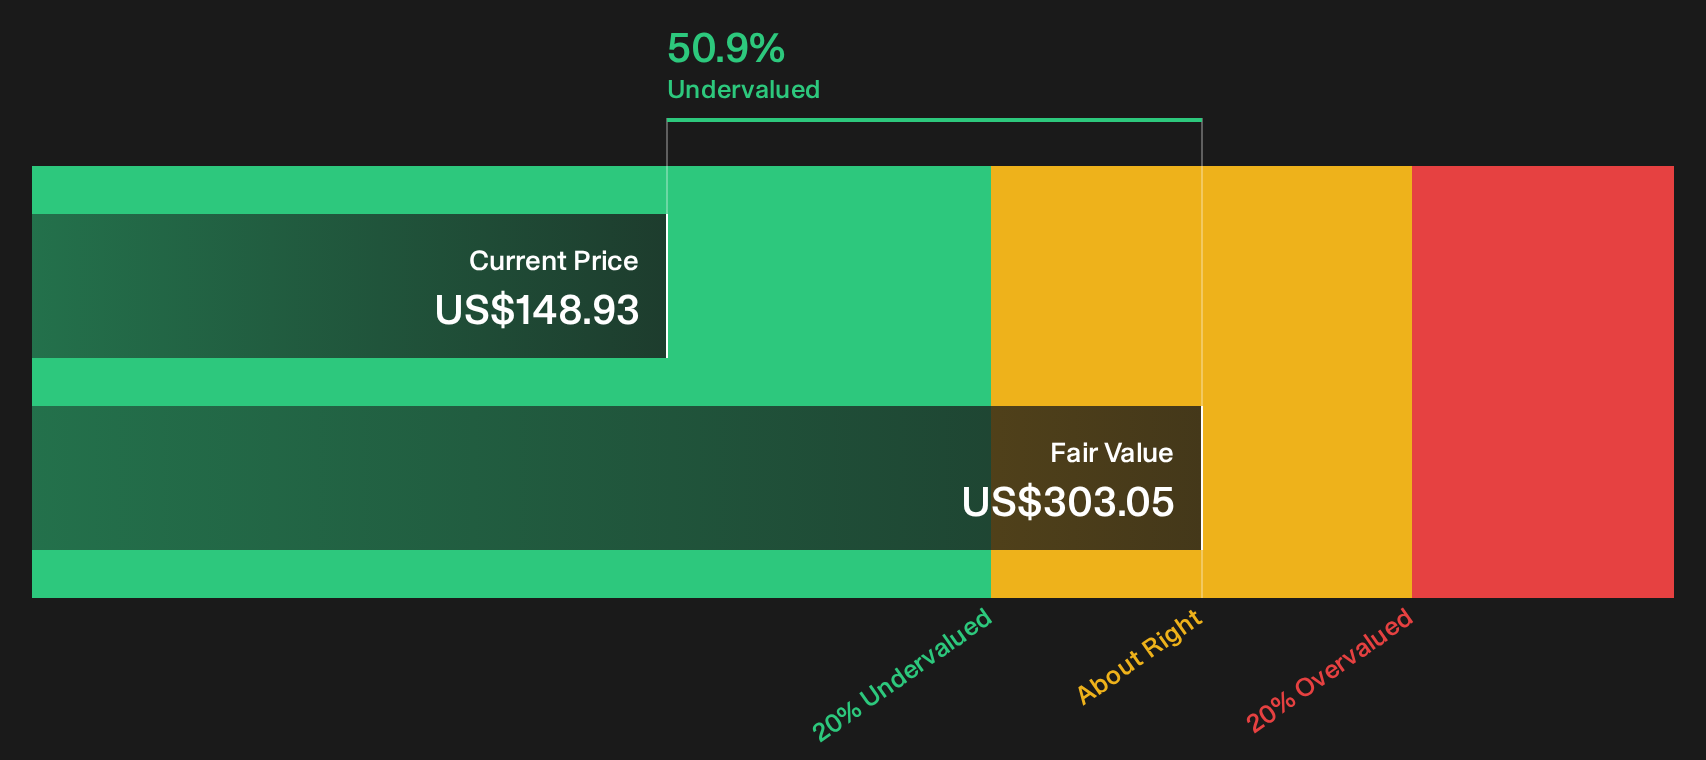
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Duolingo for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Feeling caught between Duolingo’s risks and rewards after this legal twist and valuation split? Move quickly to weigh the evidence on both sides through 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Duolingo?
Duolingo’s story is compelling, but your next strong move may come from broadening the search with focused stock ideas tailored to different investing angles.
- Target potential upside in companies that combine quality and valuation by scanning a hand picked set of 33 high quality undervalued stocks.
- Protect your downside by prioritising resilient businesses with sturdier finances using a curated 32 resilient stocks with low risk scores.
- Hunt for future leaders early by reviewing a carefully filtered 13 elite penny stocks with strong financials that most investors are not watching yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com