
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Envista Holdings (NVST) Climbed Today, But What Is Driving Attention?
Envista Holdings (NVST) landed in the spotlight after several brokers, including Baird, downgraded the stock. This shift can quickly reshape how investors view risk, opportunity and near term trading setups.
Recent moves in Envista Holdings reflect that mixed backdrop. The share price has climbed over the past week, with a 7 day share price return of 3.43% and a 1 day gain of 2.98%, but that follows a 30 day share price return that declined 4.97% and a 90 day share price return down 12.12%. At the same time, total shareholder return over the past year sits at 19.11%, while longer term total shareholder returns over three and five years remain in slightly negative territory. This suggests short term momentum is rebuilding, while the longer history still shows a more subdued journey.
Scan how Envista Holdings compares to other dental and healthcare equipment plays by reviewing our curated list of list of solid balance sheet and fundamentals (25 results) before the next round of analyst moves lands.
Envista Holdings just bounced after a wave of downgrades, which puts a simple choice in front of you. Is this a reasonable entry now, or does patience for a cheaper valuation make more sense?
Most Popular Narrative: 21% Undervalued
Envista Holdings last closed at $23.50, while the most widely followed narrative pegs fair value close to $29.69 using an 8.2% discount rate. That gap reflects a story built around earnings expansion, disciplined buybacks and a recalibrated view of risk rather than a quick sentiment swing.
Increasing R&D investment (up 14% year-over-year) and successful launches of digital and AI-driven products (e.g., DTX Studio Clinic with AI, DEXIS CDCTs, Spark product line) enhance Envista's ability to capitalize on growing demand for digital dentistry, supporting both future revenue growth and gross margin expansion.
See why 3 investors see Envista Holdings as 21% undervalued.
Result: Fair Value of $29.69 (UNDERVALUED)
Still, the Envista Holdings story can change quickly if China volume based procurement pressures deepen, or if trade tariffs and currency swings keep squeezing profitability.
Find out about the key risks to this Envista Holdings narrative.
Another View: Envista Holdings Through The P/E Lens
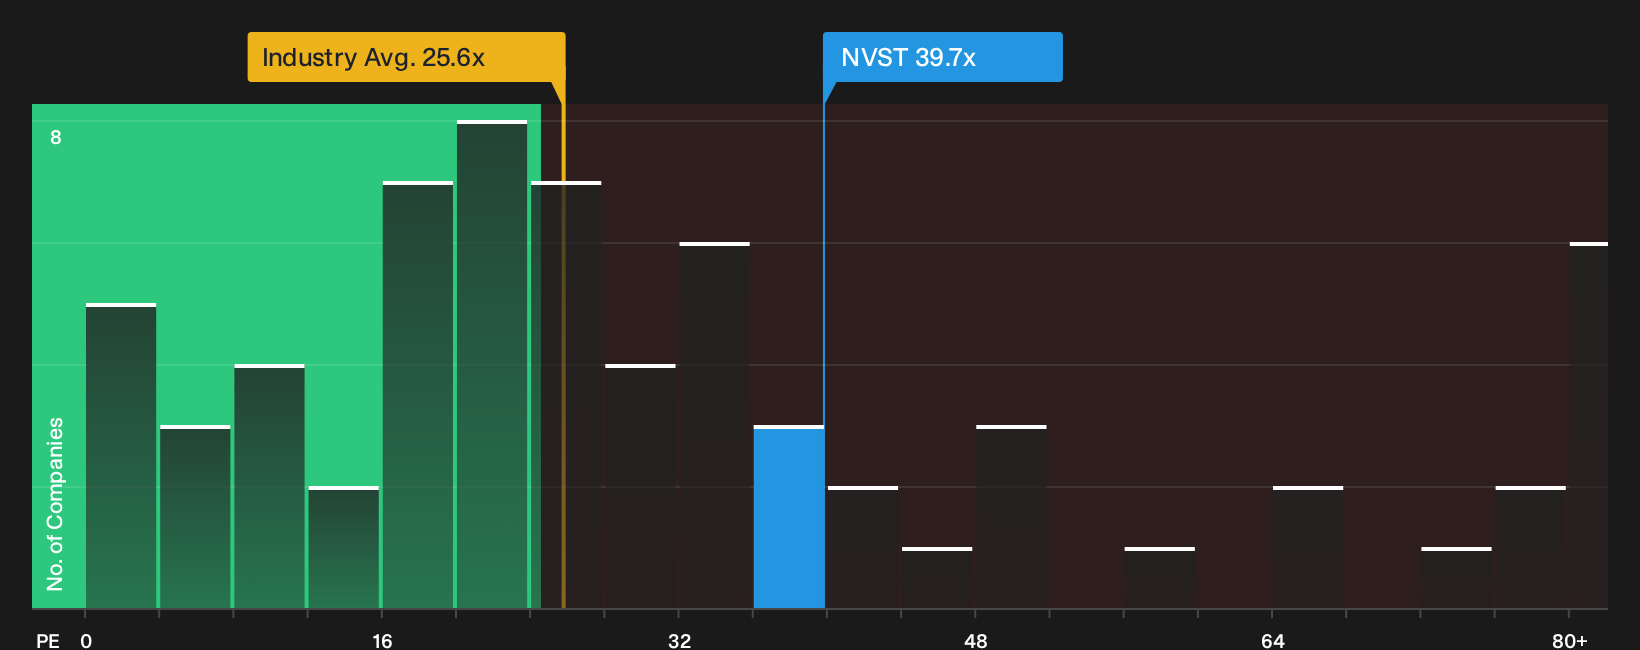
The DCF work points to upside, yet the basic P/E check paints a cooler picture. Envista Holdings trades on a 39.7x P/E, while the fair ratio is 26.9x and the US Medical Equipment industry sits closer to 24.7x with peers around 31.9x. That premium suggests investors risk paying up today if sentiment or forecasts slip. How comfortable are you with that gap?
To pressure test this earnings based view against detailed cash flow assumptions, have a look at the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment around Envista Holdings is split, which is exactly when fresh data can matter most for your own decision. Move quickly, review the full picture, and weigh up the 4 key rewards.
Looking For More Investment Ideas Beyond Envista Holdings?
Do not stop with Envista Holdings. Broaden your watchlist today with fresh ideas filtered by quality, value and resilience, so you are not chasing the crowd later.
- Target potential mispricing by scanning companies that combine quality fundamentals with appealing valuations through the 33 high quality undervalued stocks.
- Prioritise resilience by reviewing a 32 resilient stocks with low risk scores that focuses on businesses with steadier profiles when conditions get choppy.
- Get ahead of the crowd by checking a 20 high quality undiscovered gems that highlights strong fundamentals before they attract wider attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com