
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
ABM Industries (ABM) Could Be 10% Undervalued As SoFi Stadium Contract Extends
ABM Industries (ABM) extended its long running facilities contract with SoFi Stadium and YouTube Theater, underlining how embedded the provider is in large sports and entertainment venues that rely on recurring operations support.
Recent trading backs up that story. ABM Industries shares are up 6.68% on a 90 day share price return and 18.93% on a year to date share price return, while the 3 year total shareholder return of 30.75% points to steady compounding rather than a sudden surge of momentum.
Scan other facility and infrastructure specialists that show similar recurring-contract momentum to ABM Industries by using our curated list of list of solid balance sheet and fundamentals (25 results)
ABM Industries appears to be a solid operator with long contracts and a history of steady share price gains. The harder question is whether that resilience is already fully reflected in today’s valuation.
Most Popular Narrative: 9% Undervalued
ABM Industries closed at $50.76 while the most followed narrative anchors fair value closer to $55.93, so the gap now hinges on how much of its higher margin technical work ultimately flows through to earnings.
The strong growth in ABM Industries semiconductor, microgrid, and data center activities, which generated nearly US$775 million of year to date revenue in FY26 at a double digit blended operating margin and now exceed 11% of company revenue, points to a larger share of earnings coming from technical infrastructure end markets that could lift consolidated margins and earnings power.
See why 11 investors see ABM Industries as 9% undervalued.
Result: Fair Value of $55.93 (UNDERVALUED)
Still, the ABM Industries story leans heavily on higher margin semiconductor and microgrid work scaling as planned, and on free cash flow staying close to recent guidance.
Find out about the key risks to this ABM Industries narrative.
Another View: What ABM Industries Looks Like On Earnings Multiples
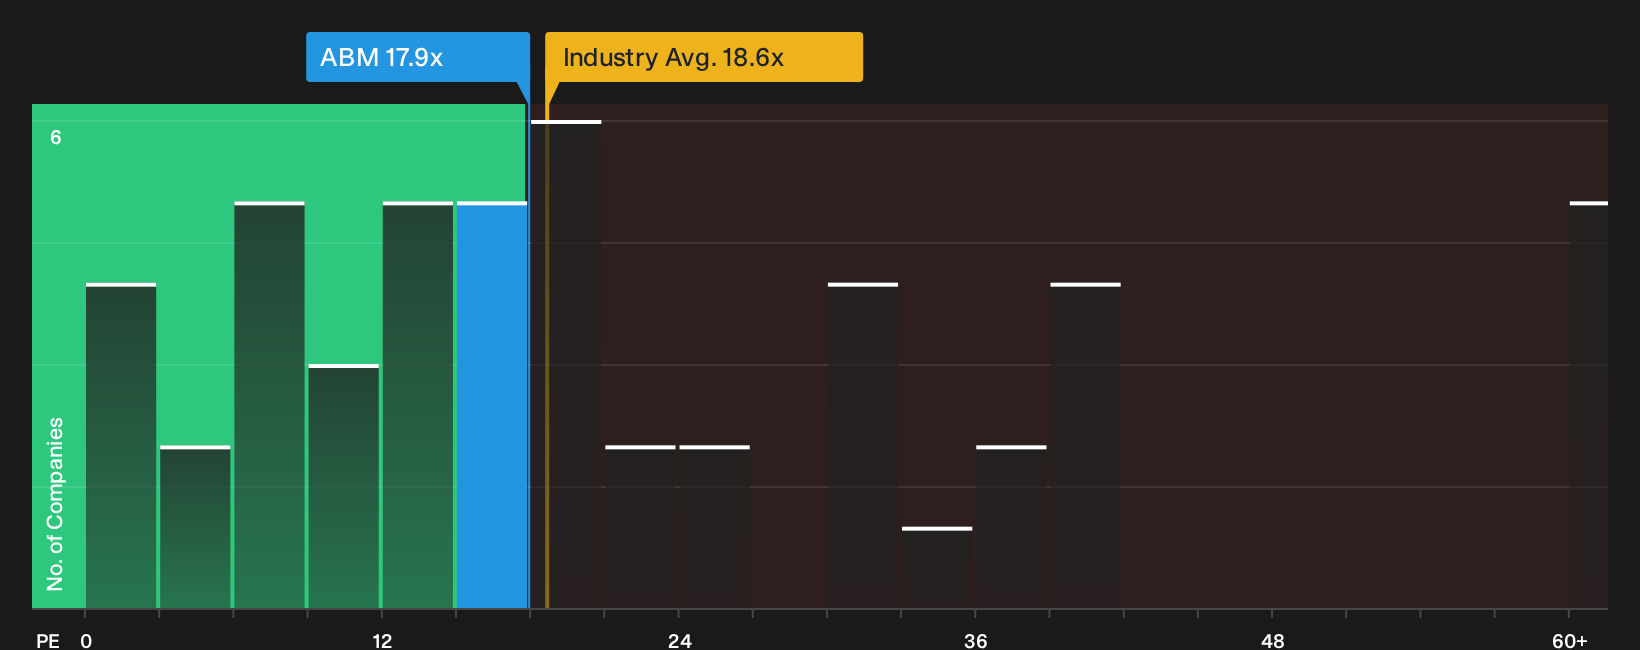
The earlier fair value of $55.93 leans on long term earnings projections and discount rate assumptions. A simpler lens uses today’s P/E. ABM Industries trades on 17.9x earnings, almost identical to its 17.7x fair ratio and slightly below the US Commercial Services average of 18.7x, which points to only modest valuation room either way. If expectations on margins or cash flow shift, how quickly could that tight gap widen?
For a closer look at how that current earnings multiple lines up against peers and the fair ratio the market could move towards over time, check the valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
With mixed signals on valuation and earnings power, it is worth testing the optimism and caution against the underlying numbers yourself right now. For a full snapshot of both sides of the story, start by reviewing the 4 key rewards and 1 important warning sign
Looking for more ABM Industries style investment ideas?
Do not stop with ABM Industries. Use the screener to surface fresh angles, compare quality, and pressure test your next move before capital goes to work.
- Target stronger value opportunities by scanning a curated pool of companies that pass strict quality filters through the 33 high quality undervalued stocks.
- Prioritize resilience and steadier balance sheets by focusing on businesses that clear high financial health hurdles using the 32 resilient stocks with low risk scores.
- Spot potential early-stage opportunities with solid fundamentals by running screens for under-followed companies via the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com