
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Missed BAWAG Group's Run? What Holders Had To Believe
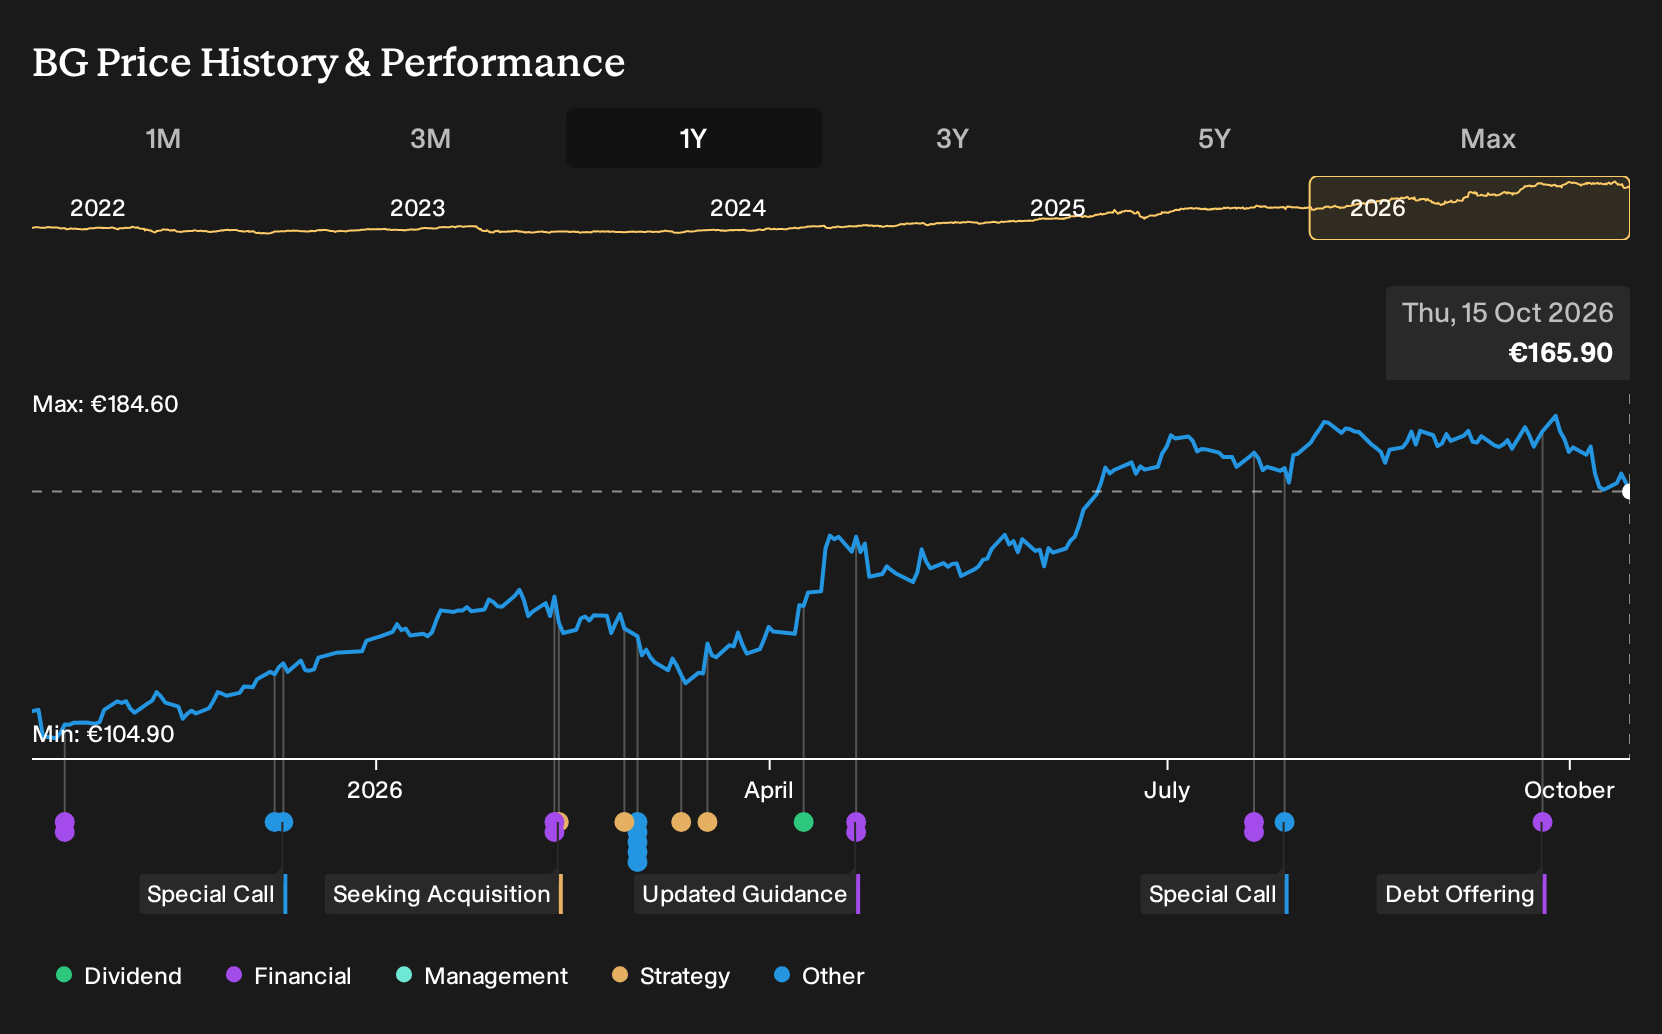
BAWAG Group spent this year in the headlines for a €1.6b bid for Permanent TSB and fresh filings showing T. Rowe Price lifting its stake past 8%. Holding BAWAG Group over the past year would have returned 54.6%, including dividends. If you had been weighing a purchase on 15 October 2025, what would you have needed to believe about integration, digital banking and DACH concentration before any of that later news arrived?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
If the move has made BAWAG Group harder to judge, start where the gap is still open and scan 194 high quality undervalued stocks.
The Argument You Would Have Been Weighing On BAWAG Group
Shares in BAWAG Group cost €112 at the start of the period, and you were choosing between two very different but reasonable stories about where the bank could go next.
The bullish narrative saw fair value at €141, or 26% above the start price, and leaned on integration and digital execution. It assumed Knab and Barclays Consumer Bank Europe would deliver synergies ahead of plan, with efficiency and net operating margins running well ahead of existing targets.
The bearish view put fair value at €79, or 29% below the start price, and focused on structural threats. It highlighted rising fintech competition and heavy DACH exposure as key risks, with prolonged low or negative interest rates expected to keep pressing on net interest margins and group earnings.
What The Evidence Around BAWAG Group Actually Tested
The planned Permanent TSB acquisition gave fresh support to the bullish integration story for BAWAG Group, while Q2 2026 results showed revenue at €500.5m and net income at €236.9m with net margin at 47.3%. Profit and margin both rose, yet a lower starting revenue base in 2025 means long run DACH concentration concerns were not settled.
The key lesson is simple. When a bank pitch leans on integration and digital execution, you test it against net margin and profit per quarter rather than headlines about new deals or shareholder disclosures.
What You Are Paying For In BAWAG Group Now
BAWAG Group now trades at €166, with this Narrative's Fair Value sitting above that level based on its own assumptions rather than any proven outcome.
The current bull case leans on capital strength, self funded growth and a bigger unsecured loan mix tied to the PTSB deal. The key question is whether management can keep risk costs near guidance while expanding higher yielding consumer and credit card lending.
"The main thing that has to go right is that management successfully executes the PTSB integration while keeping risk costs around guided levels as the loan book shifts further toward unsecured consumer and credit card lending."
The price and this Narrative do not agree. → Uncover what this Narrative says BAWAG Group is actually worth
Which Company Could Surprise You Next?
You may be late to this rally, but that does not have to mean arriving late to every opportunity. Start with companies whose prices leave room for a different view of their future. Here are three trading below our estimates.
- Company 1 - 17% below our estimate - scales distributor-led expansion into new regions using added automated production capacity.
- Company 2 - 46% below our estimate - rides accelerating online gaming adoption as proprietary technology lifts engagement and efficiency.
- Company 3 - 29% below our estimate - shifts toward adult probiotics sold through retailers as preventative health interest rises.
That is three of the list. See all 202 companies with the balance sheet to back it up →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com