
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
CoreWeave Stock Is Crashing. This Could Be Great News for SpaceX Investors.
Key Points
CoreWeave has borrowed over $50 billion to build artificial intelligence (AI) data centers.
While CoreWeave's revenue is accelerating, the company's free cash flow is expected to remain negative over the next few years.
Space Exploration Technologies has a unique opportunity to use its financial horsepower to win AI capacity deals over CoreWeave.
The artificial intelligence (AI) boom has created some unlikely winners over the last few years. But lately, one of its biggest beneficiaries has suddenly become a major headache. CoreWeave (NASDAQ: CRWV), a leading provider of AI computing infrastructure, has seen its stock plummet as investors question whether the company is borrowing too much to capitalize on surging AI demand.
Meanwhile, Elon Musk's Space Exploration Technologies (NASDAQ: SPCX) is quietly building a competing business. While SpaceX is best known for rockets and Starlink satellites, the company is becoming a serious player in AI infrastructure following its acquisitions of xAI and Cursor earlier this year.
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
With several multibillion-dollar capacity agreements beginning to generate revenue, CoreWeave's troubles could create a golden opportunity for SpaceX.

Image source: The Motley Fool.
Why is CoreWeave stock crashing?
CoreWeave is known as a neocloud. Rather than developing AI models itself, the company operates data centers filled with Nvidia chips and rents that compute capacity to hyperscalers. It's a savvy business model but an extraordinarily expensive business to build at scale.
CoreWeave has accumulated more than $50 billion in debt and operating leases as it races to build AI factories for customers including Microsoft, OpenAI, and Meta Platforms. On Oct. 14, CoreWeave stock plunged more than 15% after investors began questioning the sustainability of its borrowing strategy.
The warning signs were particularly evident in the bond market. CoreWeave's senior notes maturing in 2032 briefly traded at yields near 15% -- substantially above their original 9.625% coupon.
This doesn't mean CoreWeave is paying 15% interest on this debt. Rather, declining bond prices simply mean bond investors are demanding greater compensation for the company's credit risk.
The bigger issue at hand here is free cash flow. According to estimates from Visible Alpha, CoreWeave is expected to generate negative free cash flow of $25 billion this year, followed by deficits of $28 billion in 2027 and $18 billion in 2028.
Much of the company's spending will continue going toward infrastructure build-outs. But given the expected cash burn over the next few years, CoreWeave will depend on outside financing to continue its expansion. If lenders become less confident about the payoffs from AI data centers, CoreWeave's growth strategy becomes more vulnerable.
SpaceX is becoming CoreWeave's newest competitor
Following its merger with xAI and acquisition of Cursor, SpaceX gained access to the Colossus AI data centers originally developed to train Musk's Grok family of models. Rather than reserving all the compute power for its own internal applications, SpaceX has begun renting out excess capacity to external customers.
So far, the numbers are impressive. Anthropic agreed to pay $1.25 billion per month for compute capacity across SpaceX's infrastructure. Meanwhile, Google Cloud signed a $920 million-per-month agreement. This deal is expected to go online this month and potentially continue through June 2029. The arrangement provides access to 110,000 Nvidia GPUs and related network equipment.
In addition, start-up Reflection AI entered into a compute leasing agreement worth $150 million per month, with the potential to reach up to $6.3 billion over the lifetime of the contract. In September, SpaceX CFO Bret Johnsen disclosed an additional cloud services deal worth approximately $1.11 billion per month, with revenue scheduled to begin in December.
Together, these arrangements represent approximately $3.4 billion of monthly revenue -- equivalent to more than $41 billion annually. Most importantly, these contracts show how SpaceX is expanding into AI and moving beyond being a rocket and satellite company. It's now competing for the same AI infrastructure spending that once made CoreWeave a Wall Street darling.
SpaceX has more financial flexibility than CoreWeave
SpaceX is not immune to the financial pressures around building AI infrastructure. As of June 30, the company carried $39.4 billion in total debt. The company is also spending heavily on data centers and other capital-intensive projects.
Nevertheless, SpaceX might be better positioned than CoreWeave because of its balance sheet. Following its blockbuster IPO in June, SpaceX ended the second quarter with roughly $100 billion in cash and equivalents. By comparison, CoreWeave held only about $6 billion in cash and equivalents at the end of the second quarter.
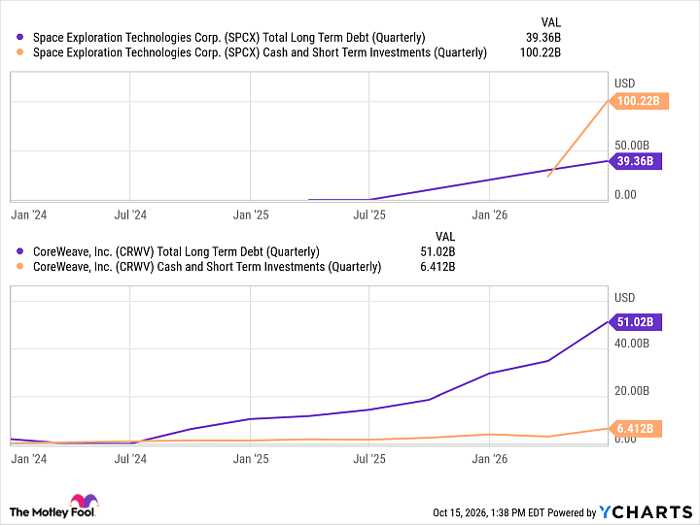
SPCX Total Long Term Debt (Quarterly) data by YCharts
For now, CoreWeave must convince lenders to keep financing its expansion while SpaceX has more room to maneuver. If CoreWeave decides to slow construction to preserve liquidity, SpaceX could have an opportunity to secure additional capacity agreements and capture more market share in the AI infrastructure market.
SpaceX's growing roster of AI customers and formidable liquidity profile give the company strong competitive advantages. For investors seeking exposure to the AI infrastructure supercycle, I see SpaceX as the more compelling opportunity over CoreWeave right now.
Adam Spatacco has positions in Microsoft and Nvidia. The Motley Fool has positions in and recommends Meta Platforms, Microsoft, and Nvidia. The Motley Fool has a disclosure policy.