
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Buckle (BKE) Sales Growth Draws Attention As Fair Value Looks About Right
Buckle (BKE) just released fresh sales data that caught investor interest, with both comparable store performance and total net sales edging higher for the latest 5 week and 35 week periods.
Buckle’s recent sales update arrives as the share price shows a sharp short term rebound, with a 1 month share price return of 17.45% and a 7 day gain of 7.53%, yet the year to date share price is still down 13.54% and the 1 year total shareholder return has declined 5.87%. This contrasts with a much stronger 3 year total shareholder return of 70.40% and 5 year total shareholder return of 82.08%, which reflect how the longer term story has looked very different from the more recent pullback.
Scan Buckle’s rebound in context by lining it up against 33 high quality undervalued stocks, which combine healthier balance sheets with stronger cash generation.
Buckle’s sharp bounce and still weaker year-to-date showing pull in opposite directions, so are investors early in a renewed rerating or already late to the move?
Most Popular Narrative: 1% Overvalued
Buckle’s most followed valuation view pegs fair value at $46, almost exactly in line with the last close at $46.57, which leaves very little valuation gap for investors to lean on.
Higher private label penetration (which reached 48% of sales in Q1 2026 and 44.5% in Q2 2026 and was linked to stronger merchandise margins) can continue to support merchandise margin levels that offset higher occupancy and SG&A and thereby sustain operating earnings.
See why 11 investors see Buckle as 1% overvalued.
Result: Fair Value of $46 (ABOUT RIGHT)
Still, Buckle’s heavier spending on new stores and remodels, along with higher SG&A as a share of sales, could pressure earnings if sales productivity softens.
Find out about the key risks to this Buckle narrative.
Another View: Buckle Through A Cash Flow Lens
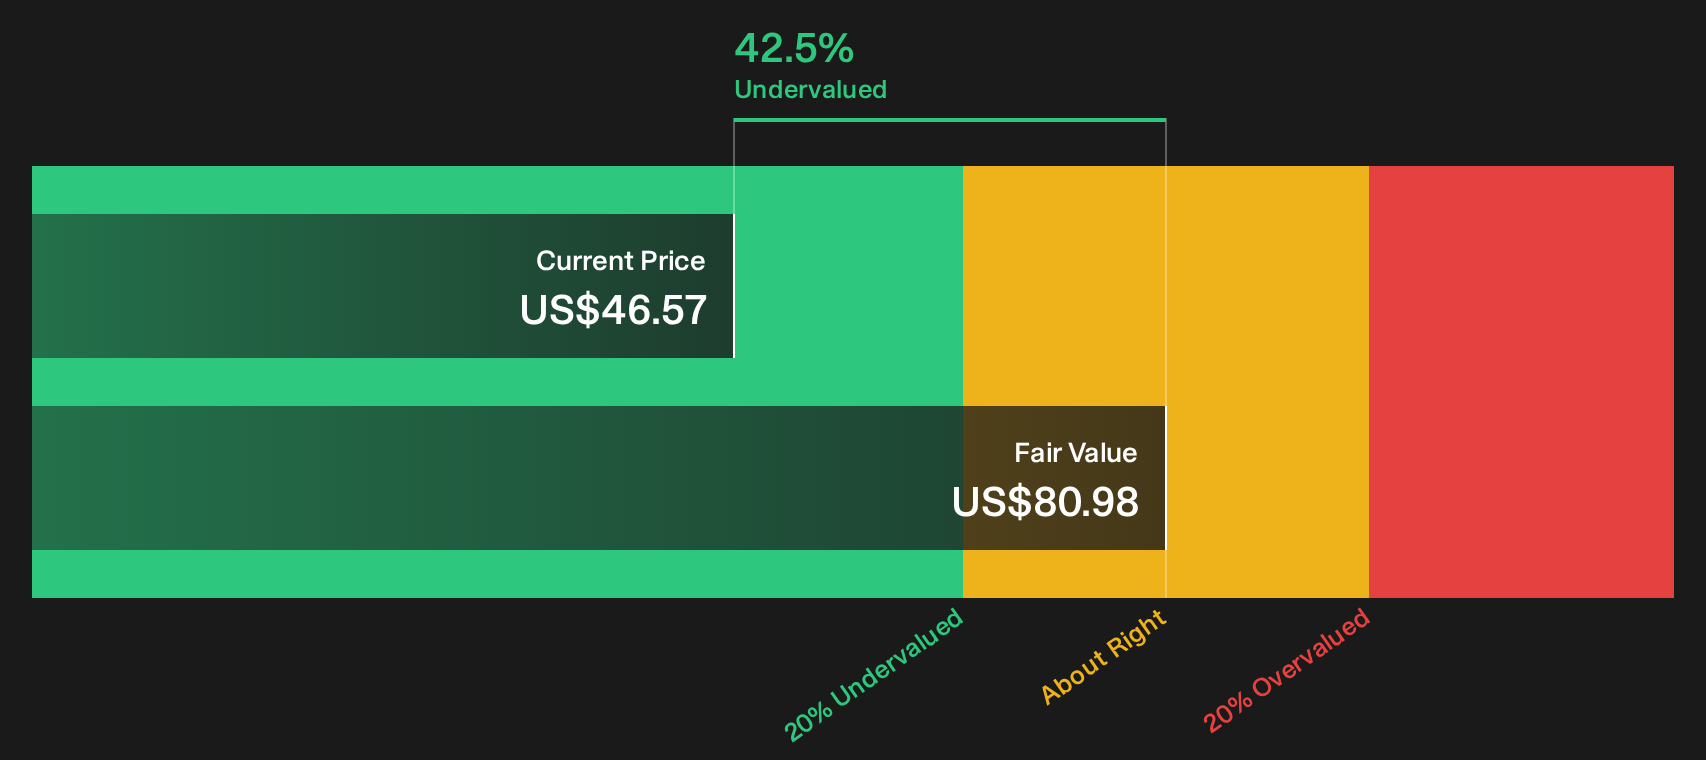
The first take on Buckle leans on analyst targets that point to a fair value around $46. A different lens tells a very different story. The Simply Wall St DCF model estimates future cash flows at $80.98 per share, which frames the current $46.57 price as trading at a steep discount.
That gap suggests the share price might be pricing in much weaker long term cash generation than this model implies. It raises a simple question for investors. Is the DCF too optimistic about Buckle's ability to keep converting its category mix and store investments into cash, or is the market being overly cautious on a mature retailer with high reported returns on equity?
To judge whether that cash flow view fits how you see Buckle's next decade, it is worth walking through how the SWS DCF model is built and what assumptions sit under that $80.98 estimate. Look into how the SWS DCF model arrives at its fair value.
Next Steps
The mix of cautious and optimistic signals around Buckle will not resolve itself for you, so move fast and weigh the 1 key reward and 2 important warning signs.
Looking for more investment ideas beyond Buckle?
If Buckle sharpened your focus, do not stop there. Broader opportunity often sits in places you have not checked yet, and the screener can surface them fast.
- Target fresh growth angles and look for beaten down quality by scanning the 20 high quality undiscovered gems before others catch on.
- Strengthen your downside protection and sort for financial resilience using the 32 resilient stocks with low risk scores while conditions still feel comfortable.
- Focus on dependable cash generators and prioritise payout strength through the 8 dividend fortresses while market attention sits elsewhere.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com