
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What to Expect From Archer-Daniels-Midland’s Q3 2026 Earnings Report
With a market cap of $40.3 billion, Archer-Daniels-Midland Company (ADM) is a global agricultural processing and nutrition company that sources, transports, and transforms crops such as corn, soybeans, and wheat into ingredients and products used in food, beverages, animal feed, biofuels, and industrial applications. With an extensive global supply chain and processing network, the Chicago-based company connects farmers with customers worldwide and is positioned to benefit from demand for food security, alternative proteins, and renewable fuels.
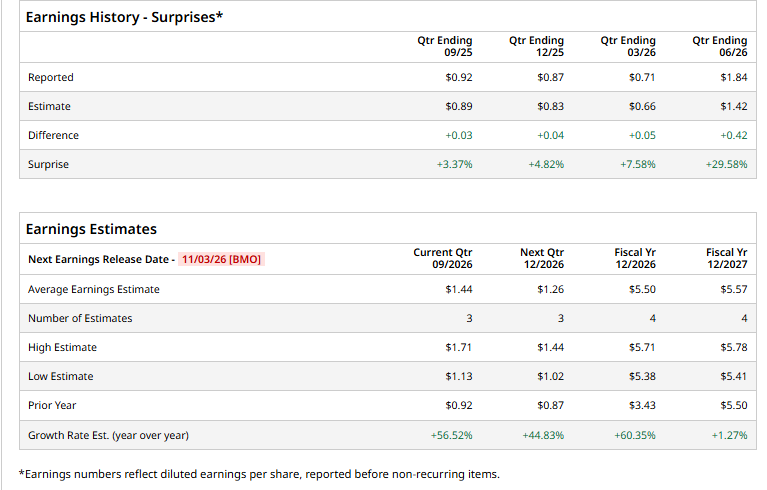
The farm products giant is expected to release its Q3 2026 results before the market opens on Tuesday, Nov. 3. Ahead of the event, analysts expect ADM to report a profit of $1.44 per share, up 56.5% from $0.92 per share reported in the year-ago quarter. The company has surpassed the Street earnings projections in all of the past four quarters, which is impressive.
For the fiscal year 2026, analysts expect the company to deliver an EPS of $5.50, up 60.4% from $3.43 reported in the previous year.
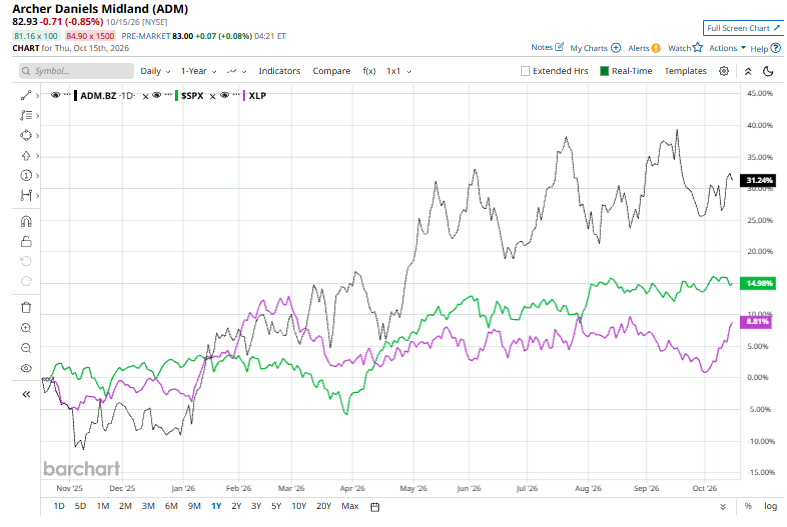
ADM has soared 30.9% over the past 52 weeks, outperforming both the S&P 500 Index’s ($SPX) 16.1% gains and the Consumer Staples Select Sector SPDR Fund’s (XLP) 9.4% rise during the same time frame.
ADM shares have popped 1.2% after the company announced a joint venture with CJ CheilJedang, a global food and biotech company that owns a leading animal nutrition business, to strengthen U.S. production of feed-grade amino acids, particularly lysine, a key ingredient in livestock nutrition. The partnership will combine CJ’s fermentation technology and amino acid expertise with ADM’s domestic manufacturing footprint and reliable feedstock supply to improve cost competitiveness and strengthen supply chain resilience.
The venture also positions ADM to capitalize on opportunities in precision fermentation and growing demand across food, feed, and industrial markets, while supporting more reliable domestic production amid trade pressures on U.S. lysine manufacturers.
Analysts remain cautious about the stock’s prospects. ADM has a consensus “Hold” rating overall. Of the 10 analysts covering the stock, one suggests a “Strong Buy,” seven recommend “Hold,” one advises “Moderate Sell,” and one gives “Strong Sell” ratings. Its mean price target of $84.22 implies a premium of 1.6% from the prevailing price level.
On the date of publication, Kritika Sarmah did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.