
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Will Lower Rate Hike Hopes Change QinetiQ Stock Narrative
- QinetiQ Group recently saw interest pick up as investors responded to a supportive Bank of England tone that implied fewer rate hikes. This pushed attention back toward defence and technology contractors.
- The renewed focus on QinetiQ Group highlights how macro signals around future borrowing costs can quickly influence appetite for long term defence technology projects and services.
- Now the focus shifts to what this macro driven interest in QinetiQ Group could mean for the broader investment narrative around contract visibility.
Scan how the renewed interest in QinetiQ Group compares with other defence and technology contractors by reviewing our hand picked list of 4 resilient stocks with low risk scores.
QinetiQ Group Investment Narrative Recap
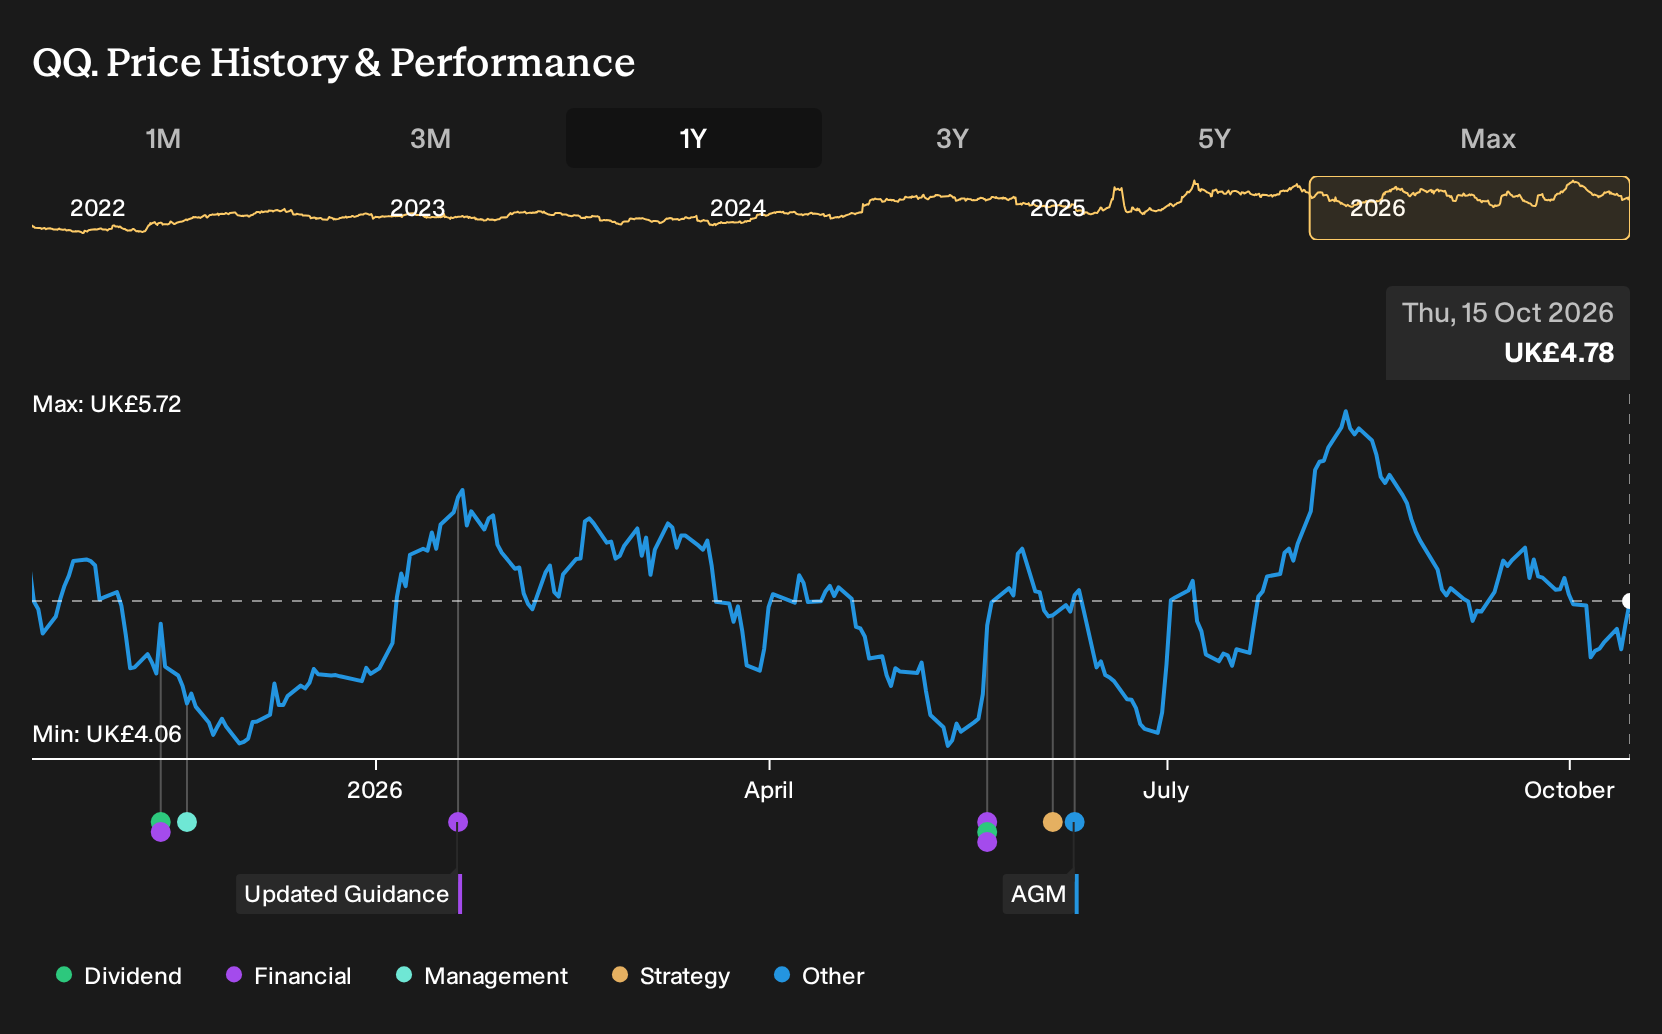
To own QinetiQ Group, you need to believe its long duration defence and mission data contracts keep turning into funded work across the U.K., U.S., Australia and Europe. The recent 2.82% share move on Bank of England comments is more sentiment than substance. The near term swing factor still looks like how quickly delayed contracts convert into revenue.
The biggest operational risk remains disruption to defence budgets or program timing, given dependence on U.K. frameworks and Australian work. Portfolio reshaping and headcount cuts add execution pressure. If contract flow slows or integration costs linger, the order backlog and margin story could look less comfortable.
With no fresh company announcements tied directly to this rate driven move, the earlier extension of QinetiQ Group's long term partnering agreement to 2033 and the reported £3.6b order intake stay central to the thesis. Those awards underpin the £4.8b backlog that covers 67% of the next year's revenue and frame how investors view contract visibility.
That contract base interacts with ongoing portfolio reshaping, the new CFO's focus on capital discipline and the multi year digital programme. Together, these give you a clear checklist for catalysts and risks, from margins and free cash flow delivery to how quickly international opportunities in areas like space, sensors and surveillance translate into executable work.
QinetiQ Group's analyst blueprint ties together a forecast for revenues of £2.2b and earnings of £186.7 million by 2029, with an assumed 5.2% yearly rise in revenue and an earnings uplift of about £79.2 million from £107.5 million today.
Uncover why QinetiQ Group's fair value indicates a 19% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
For QinetiQ Group, the bullish twist is the mission data and laser opportunity. The most optimistic analysts were already pencilling in about £2.3b of 2029 revenue and £213.9 million of earnings before this rate driven rally. You can treat the Bank of England news as a fresh prompt to recheck those assumptions and compare different viewpoints.
Explore 3 other QinetiQ Group fair value estimates, including one that suggests as much as 54% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your QinetiQ Group research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for QinetiQ Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate QinetiQ Group's overall financial health at a glance.
Looking for more investment ideas beyond QinetiQ Group?
If the QinetiQ Group story has you thinking about how to position the rest of your portfolio, the next step is to scan a broader set of opportunities with different risk and income profiles.
- For investors who want a focus on resilient balance sheets, start with our curated list of solid balance sheet and fundamentals (9 results) that combine financial strength with fundamental support.
- If you are hunting for income, use the screener highlighting 4 dividend fortresses that concentrate on higher yielding payouts.
- When you are searching for potential future leaders that are not yet widely followed, check out our hand picked 5 high quality undiscovered gems with robust underlying fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com