
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Recurring Revenue Strength Could Be A Game Changer For Topicus.com Stock (TSXV:TOI)
- Topicus.com, Inc. recently saw increased buying interest that market commentary links to its recurring vertical market software revenue model and its disciplined integration of acquired platforms.
- The focus on recurring service contracts and careful acquisition execution highlights the way Topicus.com’s decentralized subsidiaries approach can influence its operating resilience across multiple end markets.
- This article examines how Topicus.com's investment narrative is affected by the renewed focus on recurring revenue strength and acquisition integration discipline.
Scan other vertical-market software players showing similar momentum and recurring revenue strength through our hand-picked screener of 10 high quality undiscovered gems. These companies share key traits with Topicus.com.
Topicus.com Investment Narrative Recap
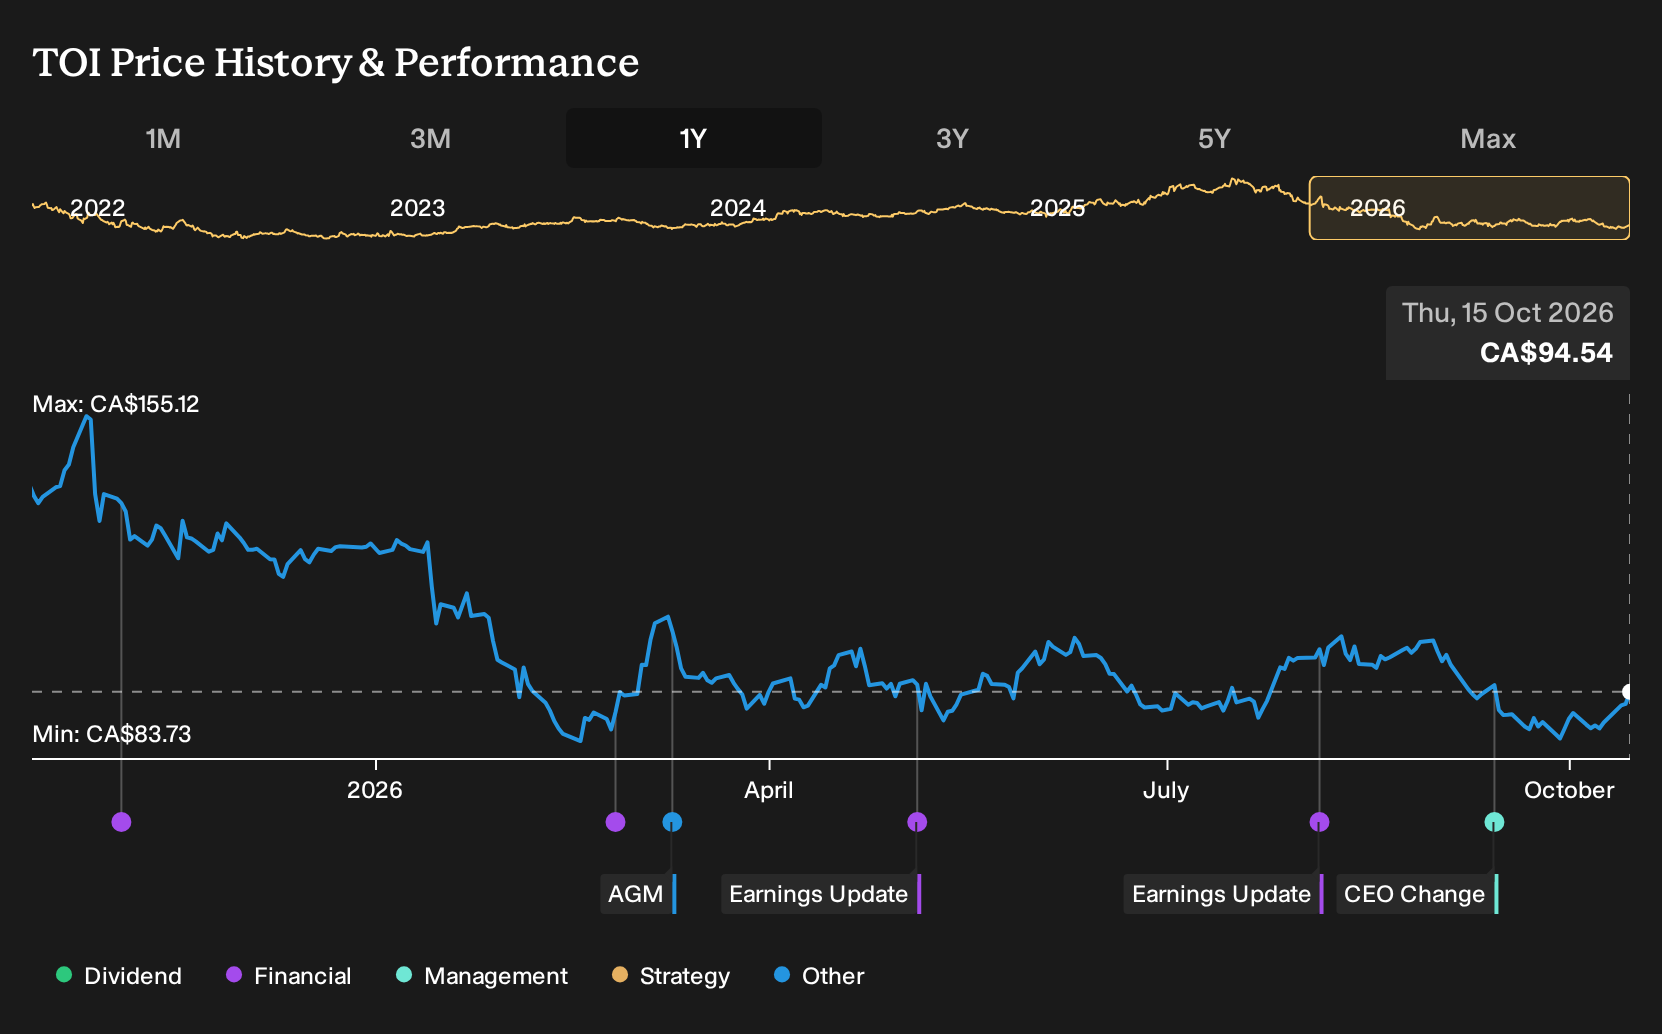
For a shareholder in Topicus.com, the core belief is that a portfolio of niche vertical software platforms, backed by recurring contracts, can compound revenue and earnings over time through disciplined acquisitions. The 4.28% share price move on 13 October simply reflects shifting sentiment. It does not materially change the near term focus on organic growth and efficient capital deployment.
The key short term catalyst remains execution on new deals and integrations without eroding margins, especially with profit margins currently at 2.1% compared with 9.1% last year and recent one off items in the mix. The biggest near term risk is that acquisition outcomes or macro driven valuation swings compress Topicus.com’s high P/E multiple.
With no fresh company announcement tied directly to the 13 October trading action, the most relevant prior update is Topicus.com’s revised non binding proposal to acquire ReadyTech Holdings at up to A$2.00 per share in cash. That potential transaction matters because it would extend the vertical software footprint into Australia and add another stream of recurring service contracts.
For you as an investor, the link back to catalysts is straightforward. Continued capital deployment into assets like ReadyTech, if completed on acceptable terms and integrated with the usual operational discipline, could broaden Topicus.com’s customer base and support the combination of 13.1% forecast annual revenue growth and very strong forecast earnings expansion, while any setback would feed directly into the core acquisition execution risk flagged by the market.
Topicus.com's current analyst narrative points to revenues of €2.5b and earnings of €631.7m by 2029, based on assumed 13.2% yearly top line growth and an earnings increase of about €596.3m from €35.4m today.
Uncover why Topicus.com's fair value indicates a 53% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Four fair value estimates from the Simply Wall St Community cluster between roughly €144.65 and €171.12 per share, which already shows how far opinions on Topicus.com can stretch. There are also risks around acquisition execution and sentiment swings on software roll up models. Use that spread to stress test your own view.
Explore 3 other Topicus.com fair value estimates, including one that suggests it could be worth just CA$144.65!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Topicus.com research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Topicus.com. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Topicus.com's overall financial health at a glance.
Looking For More Investment Ideas Beyond Topicus.com?
If the Topicus.com story has sharpened your thinking about quality, recurring revenue and disciplined capital use, it can be useful to line that up against a wider watchlist. The Simply Wall St Screener helps you quickly surface other businesses that match the kind of balance sheet strength, income potential or valuation profile you want to focus on next.
- If capital preservation comes first for you, start with a basket of companies that our models flag as sturdier options through 8 resilient stocks with low risk scores.
- If resilience and financial health rank higher than headline growth, look at a hand picked list of solid balance sheet and fundamentals (8 results) tailored for stronger funding profiles and cleaner fundamentals.
- If you want to cast the net a bit wider and hunt for potential future winners before they are widely followed, scan our curated 10 high quality undiscovered gems that share some of the quality traits you see in Topicus.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com