
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
International Paper (IP) Stock Could Be A Bargain After EMEA Sale Talks
International Paper has seen its share price move around over the past year, and recent corporate plans have put a fresh spotlight on what investors are really paying for in terms of its sales. With the stock closing at US$34.10 most recently, the question is how well that price lines up with the revenue power of the business today.
- Over the past 12 months the share price has fallen 23.3%. This puts the focus squarely on whether the current valuation is now more closely tied to the company’s sales base.
- Management’s plan to separate or potentially sell the EMEA Packaging business may reshape where those sales sit and how investors think about the future cash that can be generated from them.
- Your read on International Paper is one view; the desks covering it have another. See what analysts think International Paper's shares could be worth.
The issue now is whether International Paper’s current share price is justified by its sales when judged against the Fair Ratio benchmark.
If you want to benchmark International Paper’s sales-based valuation against a wider field, line it up alongside the companies in the 33 high quality undervalued stocks.
Does International Paper Look Undervalued on Sales?
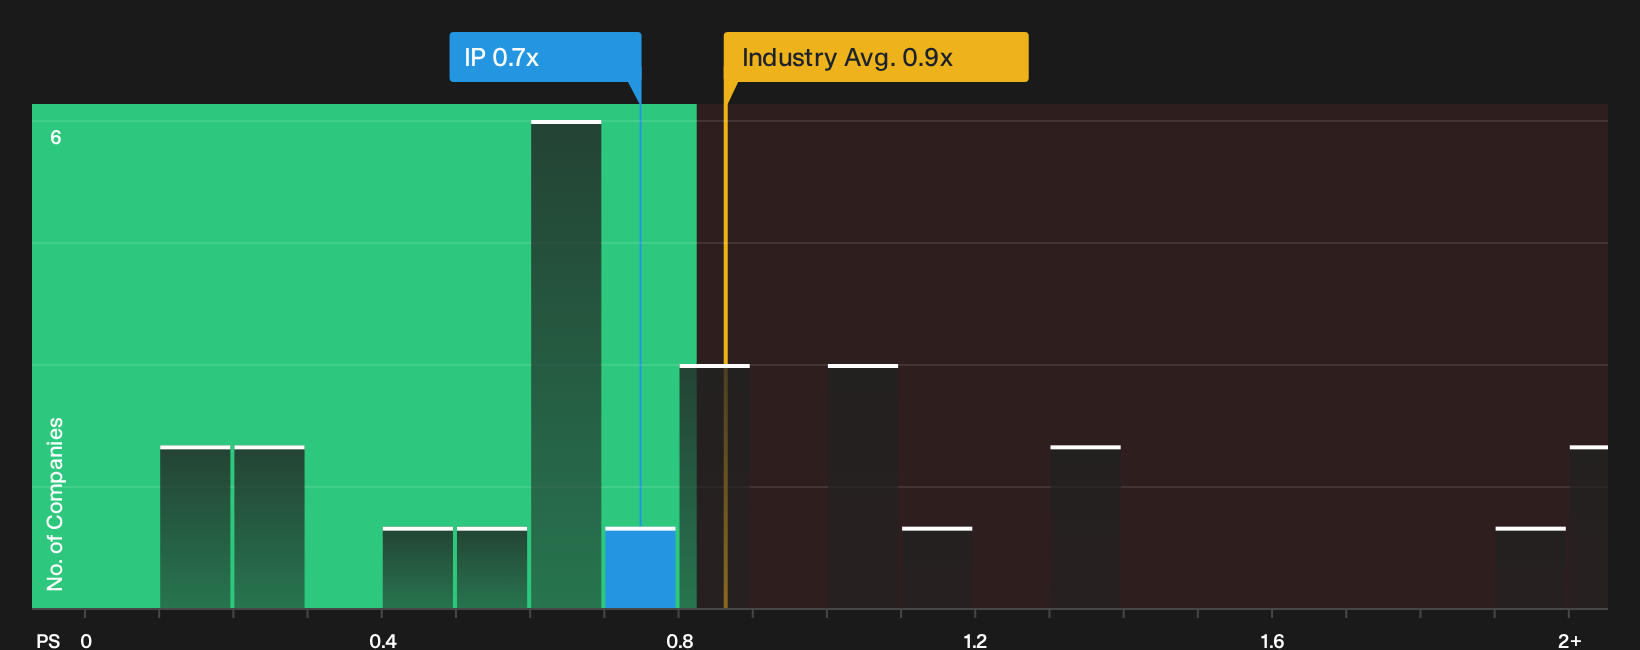
P/S fits International Paper well because this business is heavily defined by the scale and stability of its sales rather than headline earnings. On current numbers, the stock trades on a P/S of about 0.7x, which is slightly above the Packaging industry average of roughly 0.7x but below the peer group mark near 1.3x.
Because the sale or spin off of the EMEA Packaging unit is in play, investors are already weighing how much of today’s valuation really attaches to the remaining sales base. Against the Fair Ratio benchmark, which reflects what would typically be paid for a company with International Paper’s margins, growth profile, size and risks, the present 0.7x P/S screens on the undervalued side. Despite the recent lift in sentiment around a potential EMEA deal, the revenue multiple still prices International Paper at a discount to what that tailored benchmark implies. Explore the numbers behind International Paper's P/S valuation.
The International Paper Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where this P/S puzzle for International Paper leaves off by spelling out which combinations of future growth, profitability and earnings paths would need to play out for the stock to be worth materially more or less than today’s price on the Community page. Each story links its implied number to a specific view on how International Paper’s revenue mix, margins and risk profile might evolve, which you can test again as fresh information comes through.
One of the top community narratives on International Paper: 27% undervalued
"The main thing that has to go right is that management converts announced North American and EMEA footprint changes, price increases and capital projects into the targeted cost savings and returns while offsetting inflation, energy and transportation pressure..."
Discover why this Narrative puts International Paper at 27% undervalued.
International Paper’s share price is only one clue
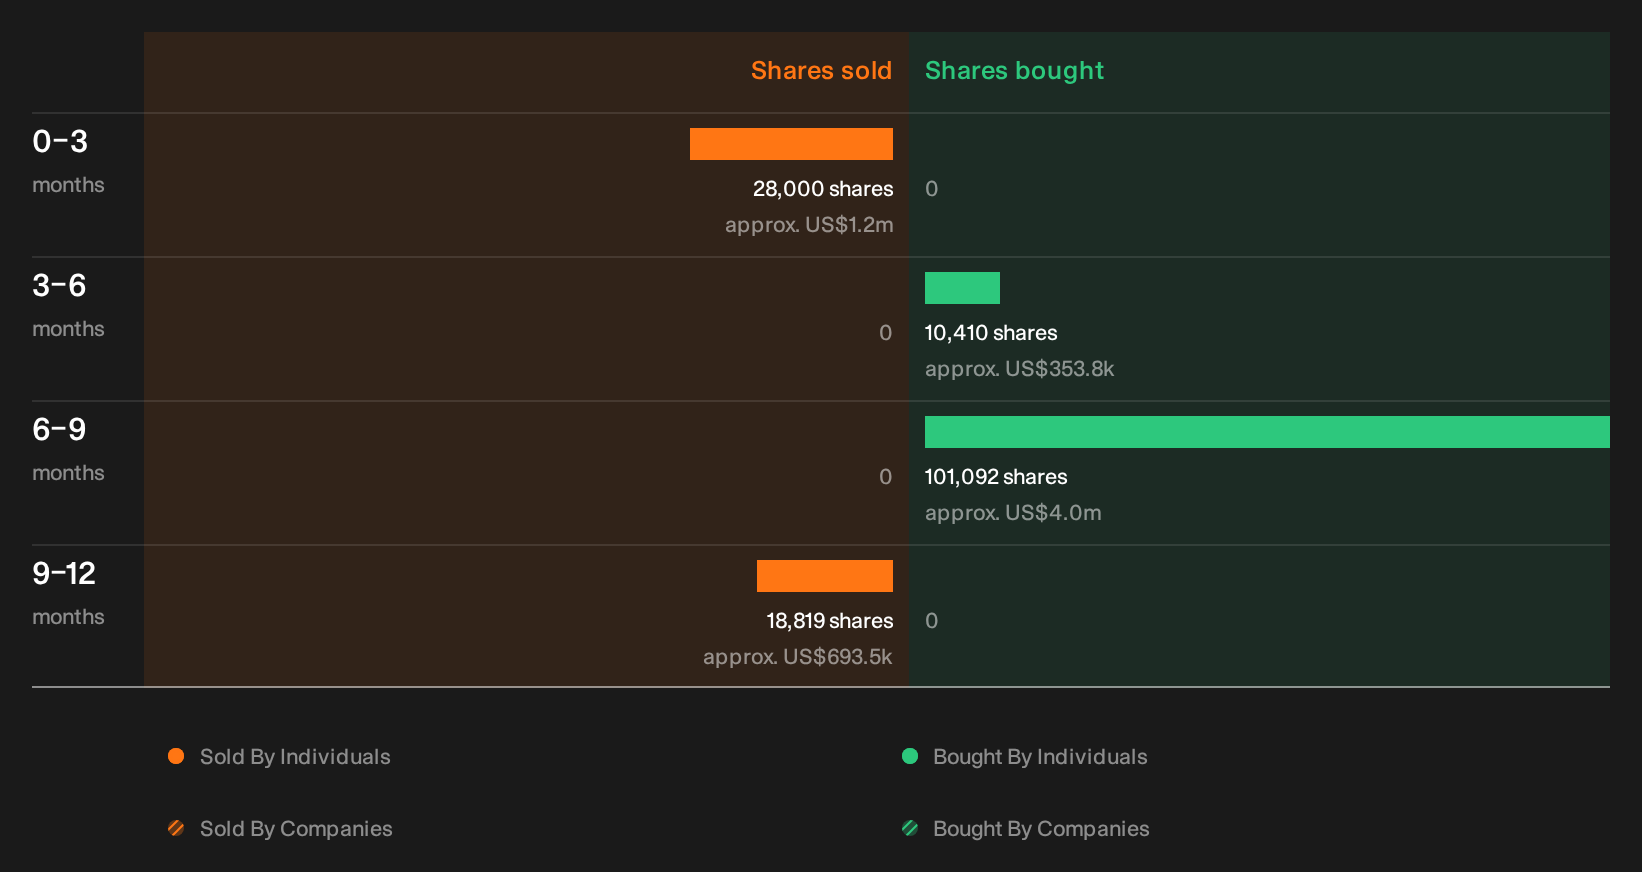
Valuation tells you what the market is paying for International Paper today, but recent trading by people inside the business adds another layer that our checks have picked up and left for you to unpack. See the recent insider selling flagged for International Paper.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com