
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Falling Gilt Yields At Landsec Has Changed Its Investment Story
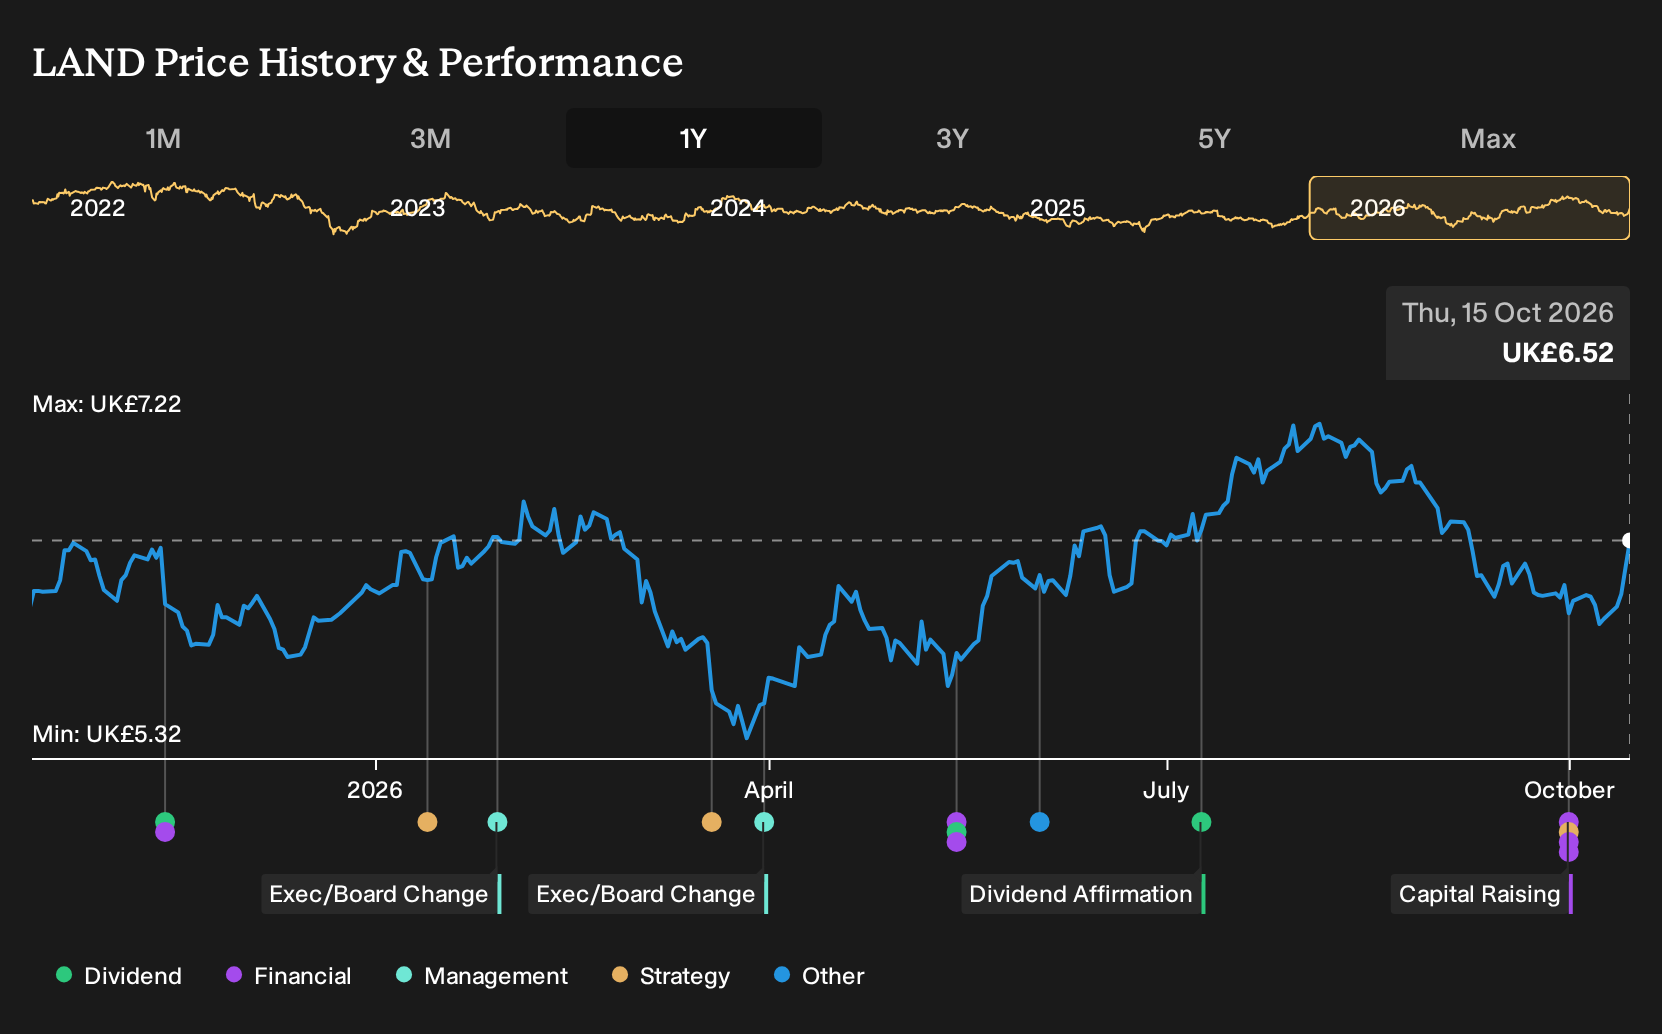
- Land Securities Group recently benefited from improving sentiment toward UK real estate, as easing gilt yields and softer Bank of England commentary reduced concern over financing costs and supported expectations for its future cash generation.
- The shift in the interest rate outlook directly affects Land Securities Group's debt burden and reinvestment options, which matters for how its prime offices and retail properties might contribute to future rental income and cash flow resilience.
- We will look at how Land Securities Group's investment narrative interacts with easing gilt yields and a less aggressive rate outlook.
Land Securities Group Investment Narrative Recap
To hold Land Securities Group, you need to believe its focus on prime London offices and major retail destinations can keep occupancy high and rental terms resilient, even as broader UK real estate stays mixed. The recent rally on softer gilt yields helps sentiment, but the near term operational swing factor is still leasing and rent levels on its key office and retail assets.
The biggest risk remains balance sheet pressure if financing costs stay sticky while portfolio values and cash flows move slowly. Recent rate friendly headlines do not fully resolve concerns about leverage and debt service. Capital recycling above £700m and progress toward lower loan to value targets still look central to the story.
The most relevant recent development is the re rating tied to easing gilts and Bank of England commentary. This fed into a stronger three year total return of 36.6% for Land Securities Group. That move matters because a lower implied cost of capital can make the DCF based valuation gap more visible to investors watching property yields.
For you, the operational question is whether that friendlier rate backdrop gives management more room to recycle low returning offices into higher yielding retail led assets without stressing liquidity. Execution on leasing recently completed London schemes and keeping committed development exposure below 2% of portfolio value will likely remain key catalysts, while debt coverage and dividend funding stay important watchpoints.
What The Current Land Securities Group Forecasts Assume
Analysts are effectively asking you to think about Land Securities Group as a business that can live with falling top line revenue while lifting profitability sharply. Their models build in revenue shrinking by 4.8% each year over the next three years, even as profit margins step up from 38.5% today toward 92.4% by around 2029. That combination matters for you because it implies far more reliance on cost discipline, asset mix and financing terms than on simple rental growth.
The earnings bridge is sizeable. Consensus points to earnings moving from £343.0 million today to £709.7 million by about 2029, which is roughly a doubling of profit. The gap between the central case and the more bullish £866.9 million view gives a sense of how sensitive outcomes could be to leasing, disposals and interest costs. If you are building your own model, the message is clear. The story is less about rapid expansion of revenue and more about what happens to margins and the income statement as older offices are recycled into higher yielding properties.
Valuation assumptions reflect that shift. To line up with the consensus view, Land Securities Group would need to support around £768.5 million of revenue and £709.7 million of earnings by 2029 while trading on a P/E of 9.4x, compared with 14.5x today. That implied multiple still sits above the current 8.8x P/E for the wider GB REITs group, so the forecast path leaves only limited room for disappointment on execution or rates before the gap to peers becomes harder to justify.
For you as an investor, the interest rate backdrop and property cycle are still just inputs. The crux is whether Land Securities Group can move its portfolio toward assets that support the jump in margin analysts are pencilling in, while keeping leverage, refinancing and dividend funding manageable. If the business cannot make that earnings uplift from a shrinking revenue base, the 2029 targets and the P/E expectations that go with them start to look demanding rather than conservative.
Land Securities Group is currently modelled on the basis that revenues reach about £768.5 million and earnings reach £709.7 million by 2029, based on a yearly revenue decline of 4.8% and an earnings increase of roughly £367 million from current earnings of £343.0 million.
Uncover why Land Securities Group's fair value indicates a 10% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Simply Wall St Community members offer four fair value views for Land Securities Group, stretching from £7.18 to £13.02 per share. You are seeing private investors using their own cash flow forecasts, not one playbook. Compare those ranges with interest rate and leverage risks, then explore several alternative viewpoints before forming your own stance.
Explore 3 other Land Securities Group fair value estimates, including one that suggests the potential for up to 100% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Land Securities Group research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Land Securities Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Land Securities Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Land Securities Group?
Once you have a handle on Land Securities Group, it can help to widen the net and compare it with other opportunities that have different risk and income profiles. The Simply Wall St screener makes it easy to filter for traits that matter to you, whether that is financial resilience, income potential or finding under followed companies with solid fundamentals.
- If capital preservation is near the top of your list, start with companies that score well on balance sheet strength by scanning our hand picked 4 resilient stocks with low risk scores.
- For readers who want income to do more of the heavy lifting, focus on businesses with stronger yields and more robust dividend profiles by reviewing this curated 4 dividend fortresses.
- If you prefer opportunities that are less crowded yet still backed by sound financials, cast a wider net using our carefully selected 5 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com