
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
International Petroleum (TSX:IPCO), What Is Behind Its Latest Update?
What International Petroleum’s Completed Buyback Means For Shareholders
International Petroleum (TSX:IPCO) has wrapped up a fresh tranche of its share repurchase program, buying 1,197,483 shares between July 1 and October 2 for CAD 39.65 million, equal to 1.06% of its equity.
This closes the buyback that management first announced on December 3, 2025. It also gives investors a concrete data point to weigh alongside the stock’s recent performance and current valuation metrics.
At a share price of CA$37.66, International Petroleum has seen strong momentum build over the year, with a year to date share price return of 47.98% and a 1 year total shareholder return of 76.06% that reflects both price appreciation and distributions.
Scan for other energy producers executing on buybacks and balance sheet discipline with our curated list of list of solid balance sheet and fundamentals (8 results)
International Petroleum now trades about 10% below the average analyst target and at a deeper discount to some fair value models after this buyback. Is that caution a warning sign, or is it an entry opportunity?
Most Popular Narrative: 6.1% Undervalued
On the latest numbers, the most followed narrative pegs International Petroleum’s fair value at CA$40.11, slightly above the CA$37.66 close. This frames this completed buyback against a modest implied discount and a long project life at Blackrod.
The imminent completion and ramp-up of Blackrod Phase 1 is expected to significantly increase long-life, low-cost production, materially improving operating cash flow and free cash flow from late 2026 onwards, supporting future revenue and earnings growth. Tightening differentials between WTI and WCS (supported by structural pipeline expansions like TMX) are expected to persist, bolstering realized prices for Canadian crude and increasing netback per barrel, directly benefiting net margins.
See why 9 investors see International Petroleum as 6% undervalued.
Result: Fair Value of CA$40.11 (UNDERVALUED)
Still, International Petroleum’s reliance on Blackrod and its exposure to shifting climate and regulatory policy could challenge the current fair value story if conditions change.
Find out about the key risks to this International Petroleum narrative.
Another Way To Look At International Petroleum’s Valuation
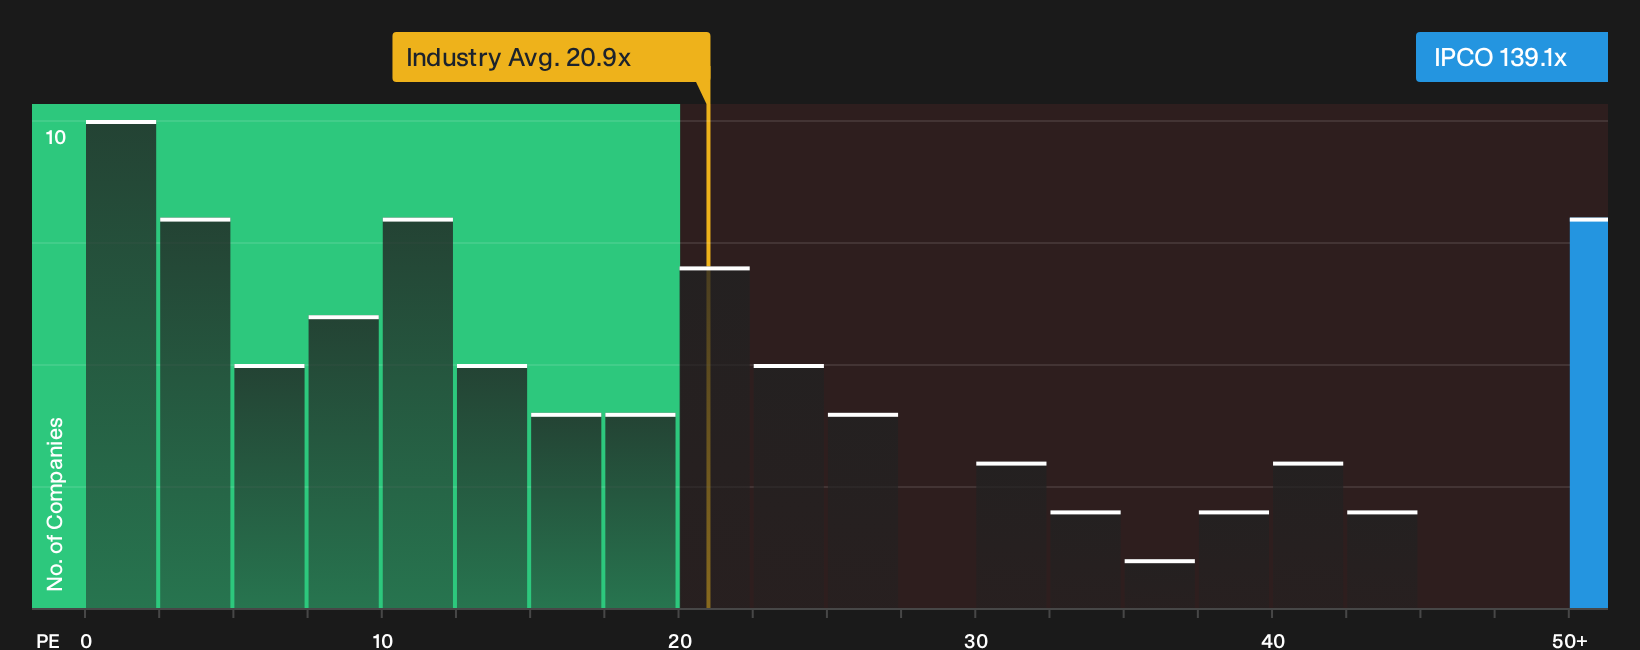
Those fair value narratives paint International Petroleum as undervalued at CA$37.66. The plain P/E story sounds very different. The stock trades on about 139x earnings, compared with roughly 21x for the Canadian oil and gas group and a fair ratio of 24.7x for this business.
That kind of gap signals that a lot of optimism is already embedded in the share price on an earnings basis, even if other models suggest upside. Which lens you trust more depends on whether you think the market will keep paying such a rich multiple for International Petroleum or drift closer to that fair ratio over time.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If you are undecided about the story so far, or already leaning one way, take a closer look at the data, weigh both sides, then judge the 2 key rewards and 2 important warning signs.
Looking For More Investment Ideas Beyond International Petroleum?
Keeping all attention on International Petroleum can mean missing other opportunities. Use the screener to surface high conviction ideas that fit your style quickly.
- Target stability first by tracking companies with resilient balance sheets and dependable fundamentals through our list of solid balance sheet and fundamentals (8 results).
- Hunt for potential mispriced opportunities by reviewing the 6 high quality undervalued stocks that combine quality metrics with attractive pricing.
- Build a steady income stream by checking out 3 dividend fortresses that focus on robust payouts backed by solid financials.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com