
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
European Growth Stocks With Strong Insider Ownership
The European market has experienced volatility recently, influenced by Middle East tensions and a hawkish stance from the European Central Bank, while mixed industrial data adds to investor uncertainty. In this environment, growth companies with high insider ownership can be particularly appealing as they often indicate strong confidence from those closest to the business.
Top 10 Growth Companies With High Insider Ownership In Europe
| Name | Insider Ownership | Earnings Growth |
| Pharma Mar (BME:PHM) | 12.1% | 39.8% |
| Kuros Biosciences (SWX:KURN) | 23.7% | 65.6% |
| KebNi (OM:KEBNI B) | 16.3% | 103.8% |
| Gold Road International (OB:GOLDR) | 36.7% | 89.8% |
| Egetis Therapeutics (OM:EGTX) | 18.4% | 49.5% |
| CTT Systems (OM:CTT) | 17.4% | 55.3% |
| Clavister Holding AB (publ.) (OM:CLAV) | 19.4% | 41.1% |
| Bonesupport Holding (OM:BONEX) | 10.6% | 32.4% |
| Bergen Carbon Solutions (OB:BCS) | 11.9% | 52% |
| 2G Energy (XTRA:2GB) | 13.4% | 30.2% |
Let's uncover some gems from our specialized screener.
Scandi Standard (OM:SCST)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Scandi Standard AB (publ) is a company that produces and sells chilled, frozen, and ready-to-eat chicken products across various countries including Sweden, Norway, Ireland, Denmark, Finland, Germany, the United Kingdom, and other international markets with a market cap of approximately SEK11.11 billion.
Operations: The company's revenue segments include Ready-To-Cook products generating SEK11.11 billion and Ready-To-Eat products contributing SEK2.93 billion.
Insider Ownership: 16.7%
Earnings Growth Forecast: 24.4% p.a.
Scandi Standard has demonstrated robust growth, with earnings increasing by 52.6% over the past year and projected to grow at 24.4% annually, outpacing the Swedish market's average. Despite trading significantly below its estimated fair value, high debt levels pose a risk. Recent financial maneuvers include a SEK 408.52 million equity offering and EUR 450 million sustainability-linked refinancing aimed at supporting long-term growth ambitions, though dividends remain inadequately covered by free cash flows.
- Click here and access our complete growth analysis report to understand the dynamics of Scandi Standard.
- Our valuation report here indicates Scandi Standard may be overvalued.
Oponeo.pl (WSE:OPN)
Simply Wall St Growth Rating: ★★★★☆☆
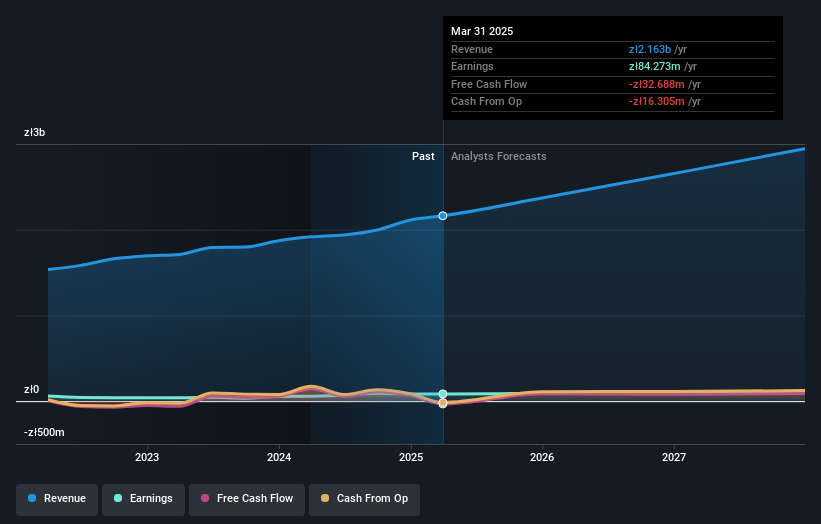
Overview: Oponeo.pl S.A. operates as an online retailer of tyres and wheels for motor vehicles in Poland, with a market cap of PLN1.19 billion.
Operations: The company's revenue is primarily derived from the sale of tires, rims, and accessories (PLN1.99 billion), followed by bicycles and bicycle accessories (PLN608.83 million), and tools including power tools (PLN72.33 million).
Insider Ownership: 21.4%
Earnings Growth Forecast: 15.3% p.a.
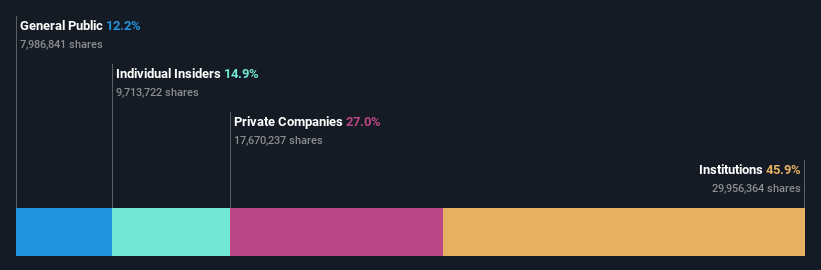
Oponeo.pl is experiencing solid growth, with earnings forecast to grow 15.3% annually, outpacing the Polish market's 10.6%. Revenue is also expected to rise by 11.8% per year, surpassing the market average. Despite this growth trajectory, debt coverage by operating cash flow remains inadequate and profit margins have decreased from last year. Recently added to the S&P Global BMI Index, Oponeo.pl reported a significant increase in half-year sales and net income compared to the previous year.
- Click here to discover the nuances of Oponeo.pl with our detailed analytical future growth report.
- Our valuation report unveils the possibility Oponeo.pl's shares may be trading at a premium.
2G Energy (XTRA:2GB)
Simply Wall St Growth Rating: ★★★★★★
Overview: 2G Energy AG, with a market cap of €846.05 million, manufactures and provides decentralized energy supply systems in Germany and internationally through its subsidiaries.
Operations: The company's revenue primarily comes from its Electric Equipment segment, which generated €398.62 million.
Insider Ownership: 13.4%
Earnings Growth Forecast: 30.2% p.a.
2G Energy is poised for robust growth, with earnings expected to rise 30.2% annually, significantly outpacing the German market's 14.5%. Revenue is forecast to grow by 21.7% per year, driven by strong order trends and strategic initiatives like new data center projects in the US. However, recent half-year results showed a net loss of €0.75 million amid declining sales and revenue compared to last year. Despite this setback, raised guidance for future years indicates management's confidence in sustained growth and improving profit margins starting in 2027.
- Navigate through the intricacies of 2G Energy with our comprehensive analyst estimates report here.
- The analysis detailed in our 2G Energy valuation report hints at an inflated share price compared to its estimated value.

Summing It All Up
- Navigate through the entire inventory of 203 Fast Growing European Companies With High Insider Ownership here.
- Searching for a Fresh Perspective? Trump has pledged to "unleash" American oil and gas and these 22 US stocks have developments that are poised to benefit.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com