
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
GLP J REIT (TSE:3281) H1 Results Cloud Buyback Confidence
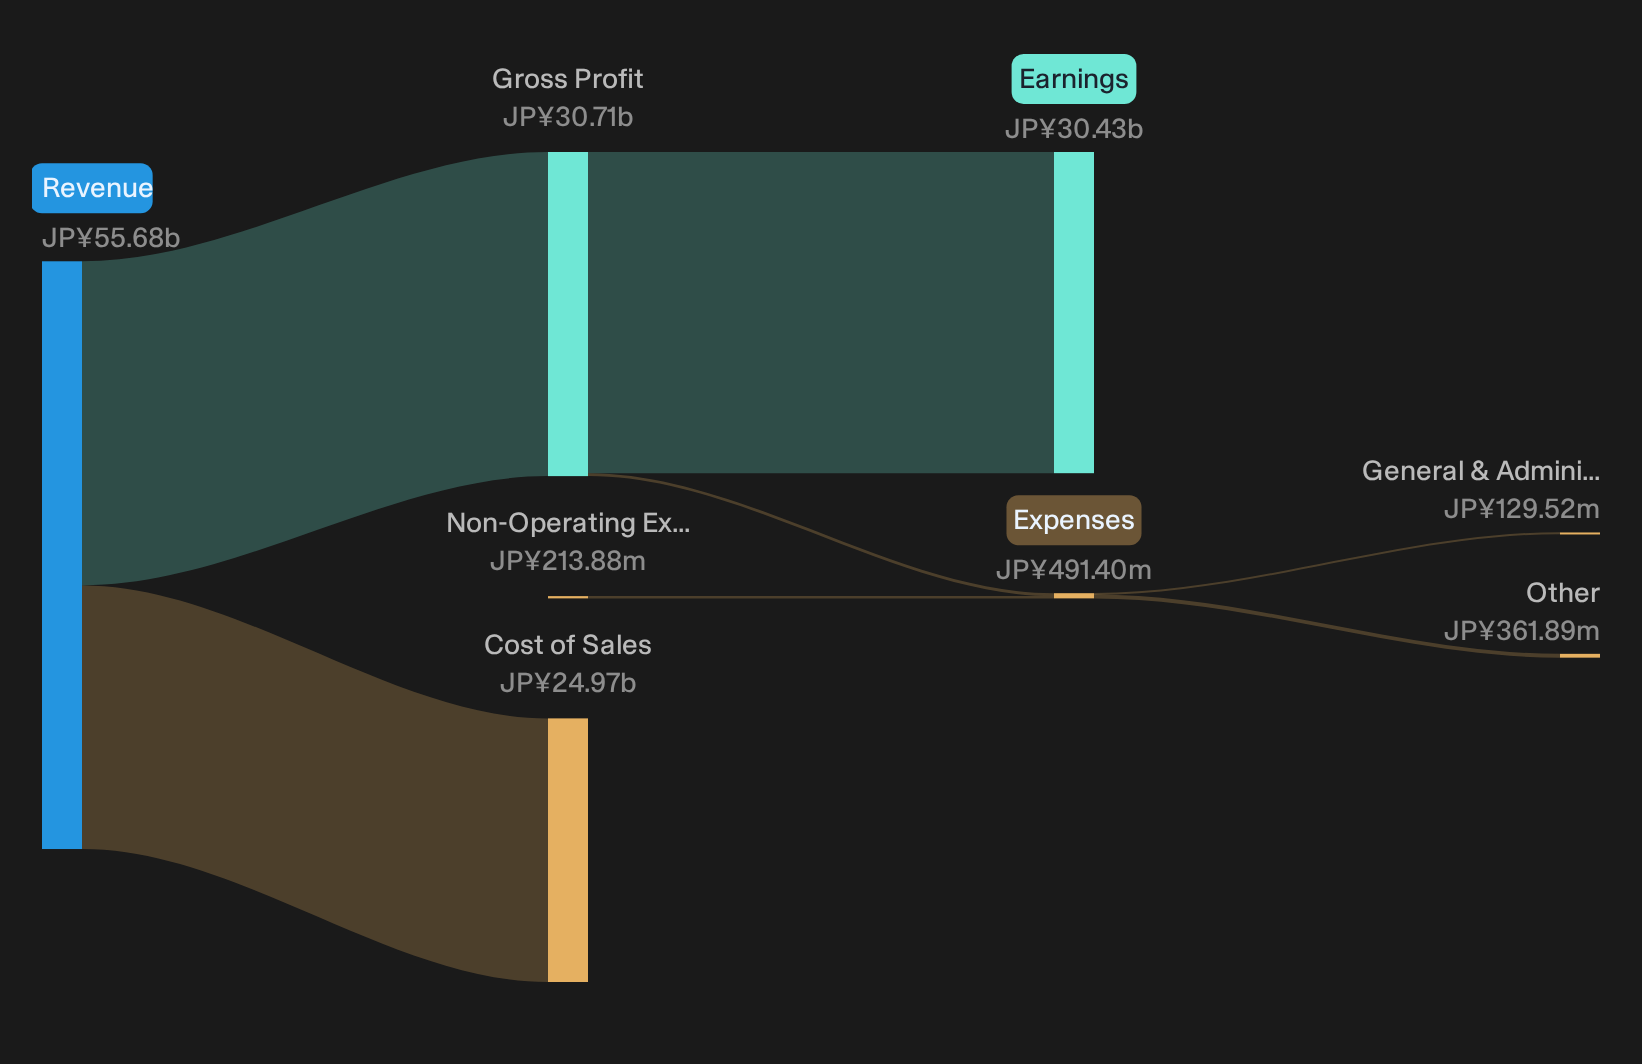
GLP J-REIT walked into this H1 2027 earnings print with a stock that has drifted over the past quarter, down about 9% over 90 days, and carrying a rich 20.2x P/E and a stretched 5.14% yield. The fresh results show net income of ¥15,532 million on revenue of ¥30,454 million, solid figures for a logistics focused trust. However, the real story is sentiment colliding with a balance sheet that still looks tight on dividend and debt coverage.
Love the 5.14% yield on GLP J-REIT but uneasy about tight dividend and debt coverage? Check out the list of solid balance sheet and fundamentals stocks (21 results).
H1 2027 Earnings Summary
- Revenue (H1 2027 vs. H1 2026): ¥30,454 million vs. ¥26,018.357 million (higher reported revenue)
- Net Income (Excl. Extra Items, H1 2027 vs. H1 2026): ¥15,532 million vs. ¥16,062.727 million (lower reported net profit)
- Basic EPS (H1 2027 vs. H1 2026): ¥3,248.71 per unit vs. ¥3,347.98 per unit (lower earnings per unit)
- Funds From Operations (FFO, H1 2027 vs. H1 2026): ¥15,607 million vs. ¥15,904 million (slightly weaker cash flow from core operations)
Earnings tell part of the story, but if you care about what you are really paying for GLP J-REIT you need to look at the cash flowing through the trust. Cash generation supports distributions, debt service and any comfort with that 5.14% yield.
On GLP J-REIT's cash flows alone, and without treating this as a prediction, the stock could be a whopping 38% overvalued.
GLP J-REIT: What Still Supports the Bulls
For investors leaning positive on GLP J-REIT, the headline is simple: the trust is still collecting more rent. Revenue of ¥30,454 million sits above the prior ¥26,018.357 million, which supports the idea of a sizeable, functioning logistics portfolio. Funds From Operations of ¥15,607 million are only slightly softer than ¥15,904 million. That supports the view that cash generation is broadly holding together. A newly announced buyback of up to 77,000 units, funded by asset sales, also signals management confidence in the balance between cash, assets and equity.
GLP J-REIT: Where The Bear Case Bites
The cautionary side focuses on earnings quality and coverage. Net income excluding extra items is ¥15,532 million, below ¥16,062.727 million, and basic EPS also edges lower. That combination, alongside slightly weaker FFO, points to a trust that is working harder just to stand still on per unit profitability. With the unit price down about 9% over 90 days and a buyback funded by disposals rather than surplus growth cash, critics may question how much headroom there is for both distributions and incremental expansion.
Are investors reading GLP J-REIT's buyback as real conviction, or just financial engineering to offset softer per unit metrics? Check the consensus price target analysis for GLP J-REIT.Hunt For Mispriced Cash Flows
GLP J-REIT shows how earnings, cash coverage and buybacks can leave investors debating what the current unit price really reflects. The real opportunity could sit in stocks the market has not fully revalued yet.
- Company 1 - 18% below our estimate - equips enterprise teams with form and document tools once legacy print workflows choke expanding data pipelines.
- Company 2 - 20% below our estimate - supplies grinding tools and specialty ceramics when manufacturers upgrade production lines that outgrow generic equipment.
- Company 3 - 36% below our estimate - runs PR and marketing campaigns companies turn to when they replace one-off ads with always on communication.
Those are three of them. See every one of the 14 undervalued companies on it →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com