
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
AJ Bell (LSE:AJB) Cuts Pension Fees On A Narrative That Still Sees Upside
AJ Bell (LSE:AJB) has cut the annual fee on its ready-made personal pension from 0.45% to 0.35%, creating a lower-cost, all-in option that may appeal to fee-sensitive retirement savers.
AJ Bell’s lower pension charge lands at a time when the shares trade at £5.89, with a 1-day share price return of 1.03% and a year to date share price gain of 33.26%, suggesting momentum has been building despite a softer 90-day period. The 3-year total shareholder return of 143.90% and 5-year total shareholder return of 70.63% point to a strong longer term record that fee cuts like this may be aiming to support.
Scan beyond AJ Bell and see how other fee-conscious platforms stack up using the 4 resilient stocks with low risk scores for investors who care about both costs and resilience.
AJ Bell looks like a robust platform business with fresh fee cuts that could appeal to long term pension savers. The harder question is whether that quality is already fully reflected in the £5.89 share price.
Most Popular Narrative: 8% Undervalued
On Simply Wall St’s most followed narrative, AJ Bell’s fair value is set at £6.44, a touch above the recent £5.89 close. This frames the latest fee moves as part of a bigger long term thesis.
AJ Bell's strategy to continuously improve technology and platform features, combined with a focus on ease of use, is likely to drive growth in platform customers and assets under administration, positively impacting revenue.
The company's ongoing investment in brand awareness and marketing efforts, including successful sponsorship partnerships, is expected to increase customer acquisition and retention, thereby supporting revenue growth.
See why 13 investors see AJ Bell as 9% undervalued.
Result: Fair Value of £6.44 (UNDERVALUED)
Still, the AJ Bell story could look very different if a tax heavy UK budget lifts costs, or if new pension rules unsettle customer flows.
Find out about the key risks to this AJ Bell narrative.
Another View On AJ Bell’s Valuation
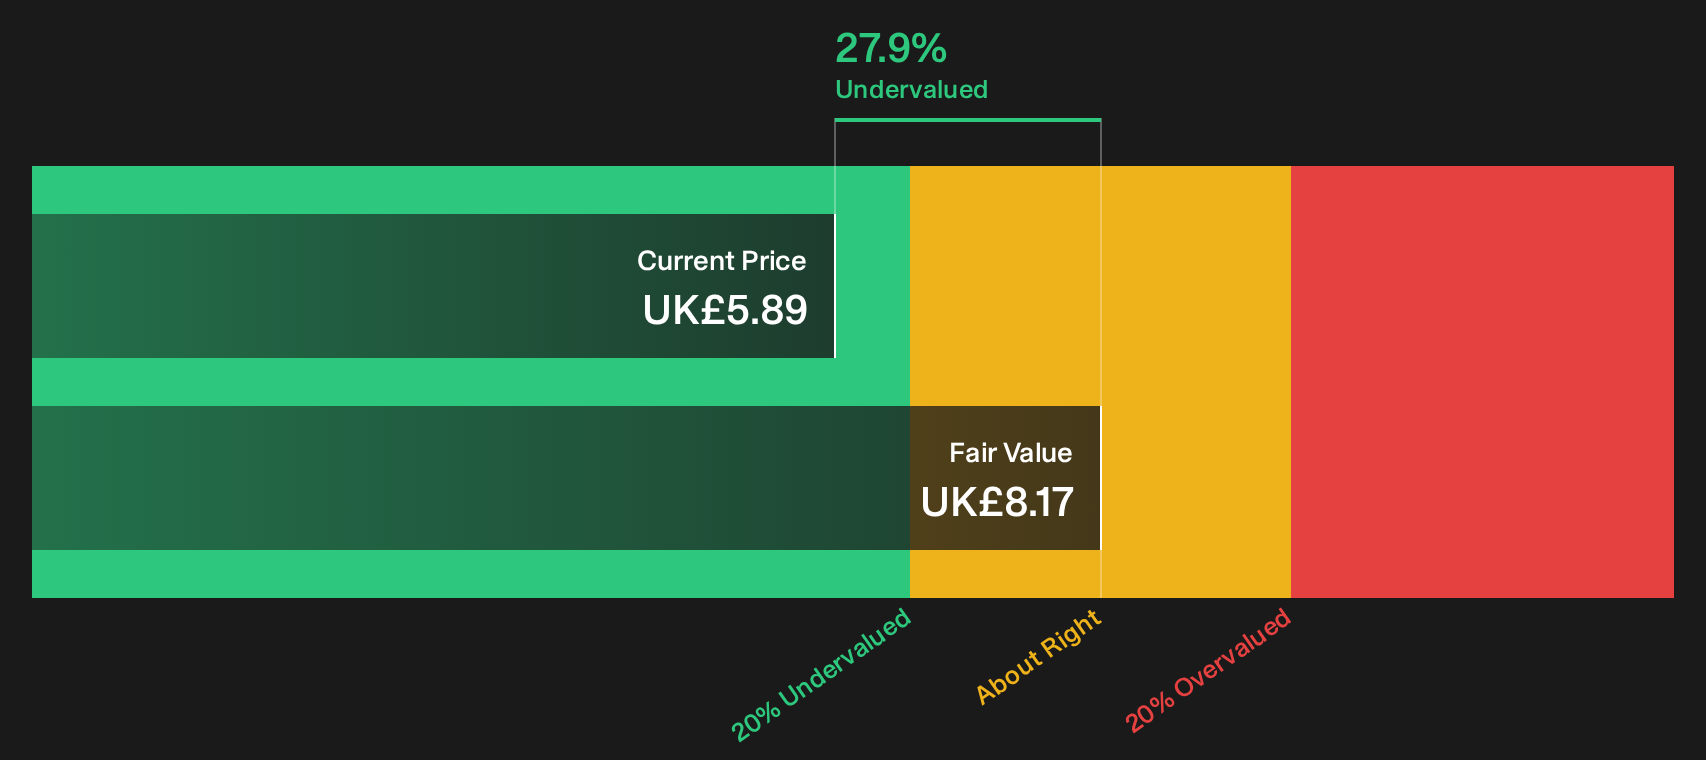
Fair value models on Simply Wall St point to AJ Bell trading at a 27.9% discount to an estimated future cash flow value of £8.17. That is a very different message compared with the relatively tight gap to the £6.44 narrative fair value, so which signal deserves more weight in your own work?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed messages on AJ Bell so far, with fee cuts, valuation gaps and a split between risks and rewards. Act while the data is fresh and pressure test the story for yourself using the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond AJ Bell?
If AJ Bell has sharpened your focus, do not stop here. Broader context across other opportunities can help you stress test and refine your plan.
- Target value with discipline and scan companies that combine quality with attractive pricing by using the 9 high quality undervalued stocks.
- Strengthen your income stream by reviewing businesses that feature resilient balance sheets and reliable payouts through the 4 dividend fortresses.
- Hunt for tomorrow's potential standouts before they are crowded by using the 5 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com