
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Bank of Queensland (ASX:BOQ) Shares Face FY Results With Profit Up But Risks Linger
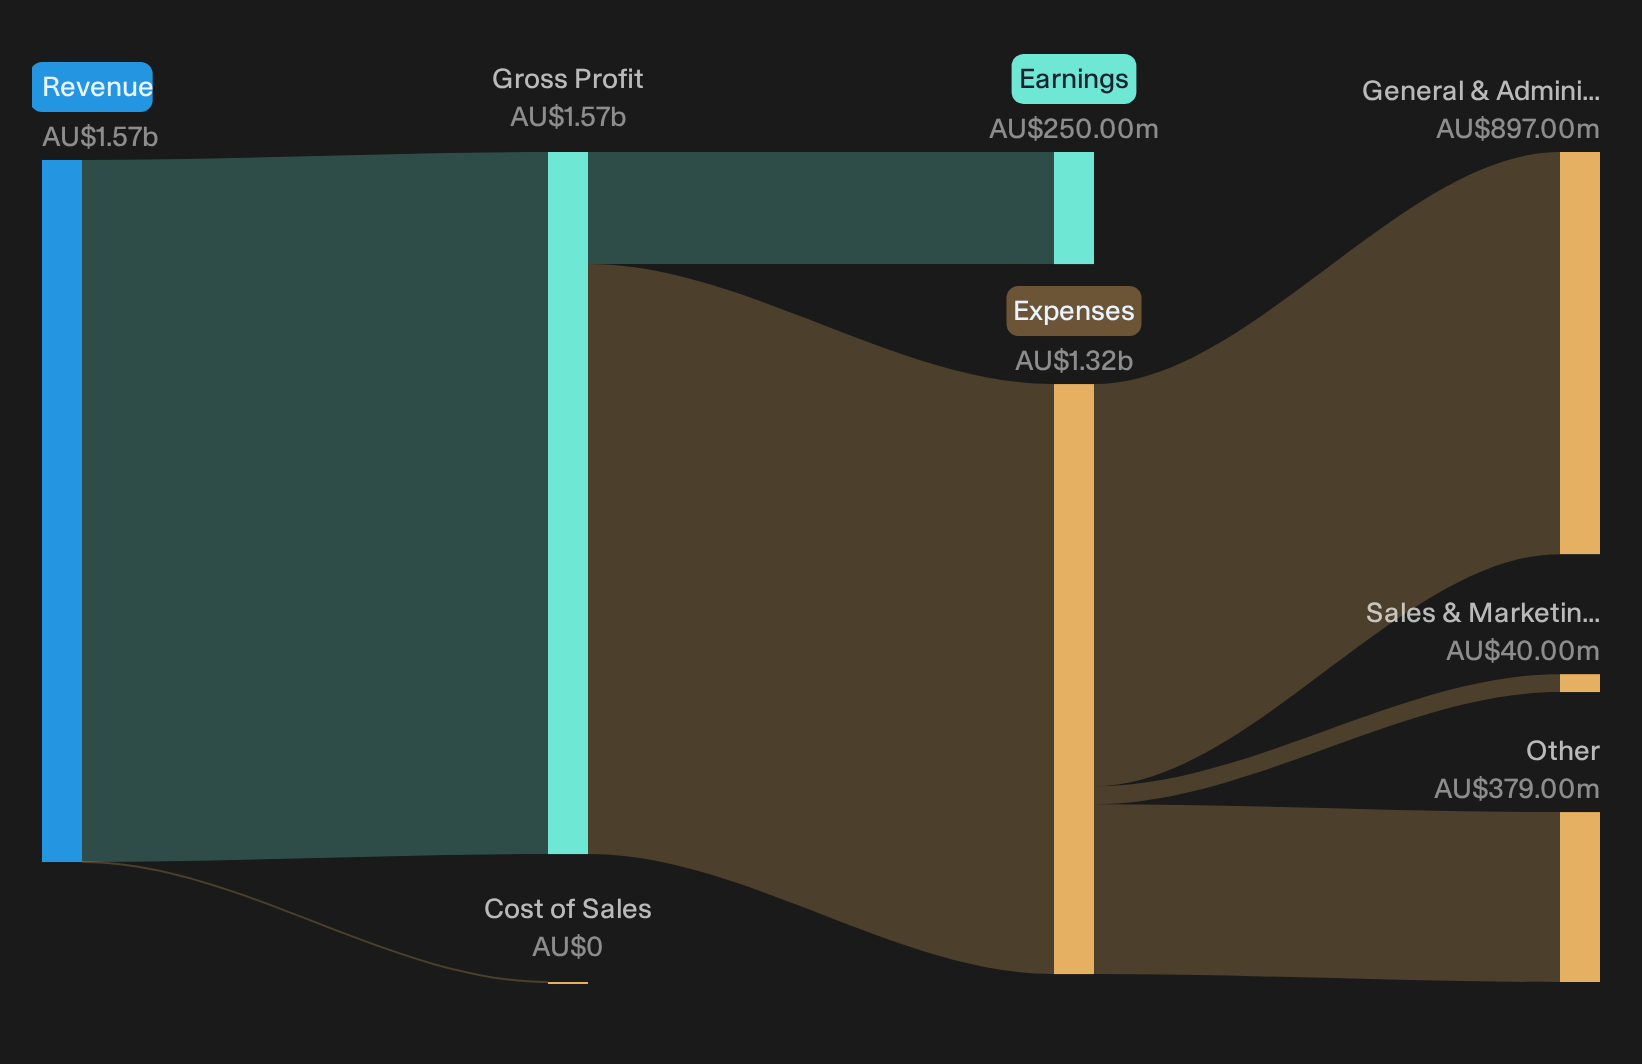
Bank of Queensland stock closed at A$6.87 today, capping a solid few weeks of gains. The fresh FY26 result on the table tells a sharper story than the share chart suggests. Statutory net profit after tax landed at A$250 million and the net profit margin sits at 16%. That level of profitability recovery is notable in banking, where small shifts in margin usually matter.
The market is trading the bounce. Over a longer horizon, the key question for Bank of Queensland is whether this improved earnings power can justify a P/E of 18x when many peers trade on lower multiples.
Like the earnings rebound at Bank of Queensland but uneasy about paying an 18x P/E for a regional lender? You can weigh that trade off against peers with sturdier fundamentals in our list of solid balance sheet and fundamentals stocks (12 results).
FY 2026 Earnings Summary
- Total Revenue (FY 2026 TTM vs. FY 2025 TTM): A$1,566 million vs. A$1,648 million (down 5.0%)
- Net Income, Excl. Extra Items (FY 2026 TTM vs. FY 2025 TTM): A$250 million vs. A$133 million (up 88.0%)
- Basic EPS (FY 2026 TTM vs. FY 2025 TTM): A$0.3806 vs. A$0.2021 (up 88.3%)
- Net Profit Margin (FY 2026 vs. FY 2025): 16.0% vs. 8.1% (improved profitability)
Ask Charlie what BOQ’s capital-light pivot really means.
BOQ transformation: progress is real, pay-off still forming
For believers in Bank of Queensland’s simplification and digital plan, the question is whether execution is turning into earnings power.
"The transformation of BOQ into a simpler, specialist bank with enhanced digital capabilities is expected to deliver improved customer experiences and efficiencies, which could drive higher revenue and margins."
Digital mortgage origination now accounts for 88% of flow and 83% of settlements, with 68% of retail customers on the digital bank. Commercial lending rose 16%, led by healthcare and agriculture, and total income edged up 1%. Yet cash earnings fell 7% and underlying profit declined 9%, so efficiency gains are not fully flowing through.
BOQ risk case: execution gains meet margin pressure
Bears focus on whether complexity and market pressure will quietly erode the benefits of the BOQ overhaul.
"The need for continuous technological advancements and potential regulatory compliance investments could increase operating expenses, potentially squeezing net earnings if not managed effectively."
Operating expenses including notables rose 7% against only 1% income growth, while loan impairment expense jumped 157% to A$54m. Management still had to absorb higher credit risk weighting in corporate and lease books and fight a deposit war with headline 6% offers. Cash NPAT excluding extra items declined 7%, which shows transformation benefits being offset by cost and credit pressures so far.
One Narrative disagrees with today's price. → See where this Narrative says Bank of Queensland should trade.
Hunt For Mispriced Earnings Power
Bank of Queensland reminded investors that sentiment may change when a turnaround becomes visible in reported figures. The real opportunity could sit in stocks the market has not fully repriced yet.
- Company 1 - 48% below our estimate - targets data center build outs and smart buildings as clients upgrade digital infrastructure capacity.
- Company 2 - 32% below our estimate - scales a multi affiliate fund platform that earns fees as additional managers connect and add assets.
- Company 3 - 49% below our estimate - wins long dated mining and civil contracts tied to demand for critical minerals and heavy infrastructure.
Those are three of them. See all 4 potentially undervalued companies →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com