
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Imperial Oil Doubters Overlooked
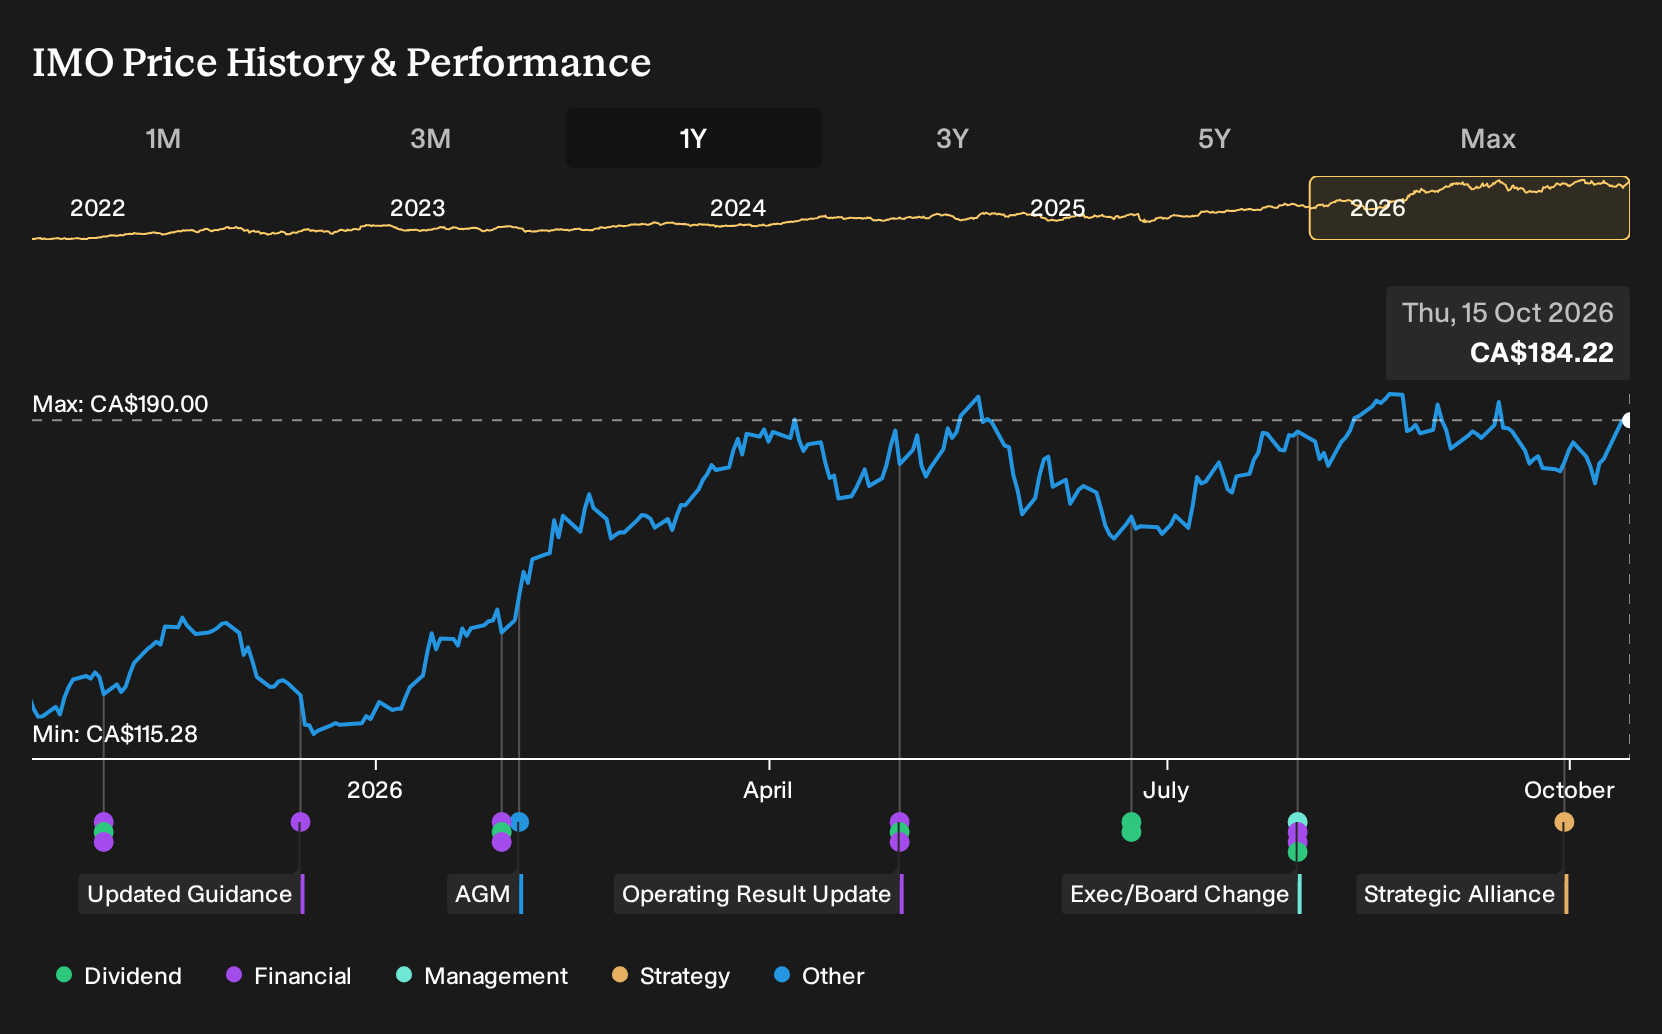
If you followed Imperial Oil through 2026, the story did not start with headlines about record quarters. It began with concrete moves such as the launch of Canada’s largest renewable diesel facility at Strathcona and analyst teams split between bullish super-cycle hopes and decarbonization worries. Investors who held Imperial Oil over the past year are up 57.9%, including dividends. If you were deciding back in October 2025, what had to be true about autonomous mining, export pipelines, and oil sands decarbonization to make that risk feel acceptable?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
If the move has made Imperial Oil harder to judge, start where the gap is still open and scan 6 high quality undervalued stocks.
What Imperial Oil Investors Were Really Arguing About
The shares cost CA$121 at the start of the period, and Imperial Oil sat between two sharply different but credible stories about its future.
The bullish narrative put fair value at CA$129, 7% above the start price. It leaned on assumptions that autonomous mining, AI driven optimization and solvent assisted processes would cut per barrel costs and support higher free cash flow conversion.
The bearish case marked fair value at CA$80.82, 33% below the start price. It focused on the risk that tightening decarbonization policy and rising carbon costs would steadily erode oil sands asset values.
What The Results Changed For The Imperial Oil Debate
Imperial Oil’s Q2 2026 figures showed revenue at CA$15,981m and net income at CA$2,190m, with net margin at 13.7% versus 8.5% in Q2 2025. That outcome backed the bullish focus on higher cash generation from large oil sands assets. At the same time, ongoing refinery downtime and carbon capture commitments kept the decarbonization risk in view, so the evidence cut both ways.
The episode turned on whether efficiency and export projects could offset policy and cost pressure. For any other producer, you would watch net margin and disclosed carbon costs side by side and test whether cleaner projects and uptime actually support both.
What Imperial Oil’s Current Price Already Assumes
Imperial Oil shares trade at CA$184 after a 57.9% gain over the past year. The selected Narrative’s Fair Value sits below the current price, which implies the recent run already builds in a generous view of how its projects and capital plans play out.
For today’s valuation to hold, you would need confidence that Imperial Oil turns complex cost savings, volume targets and refinery changes into dependable cash generation despite execution setbacks that have already appeared.
"Although Imperial Oil reports strong recent net income and cash generation, the indication that 2026 upstream volumes are now expected at the low end of the guidance range suggests that high quality oil sands assets are not fully translating into the production growth embedded in past expectations. This could cap future revenue and earnings expansion if similar underperformance recurs in later years."
One Narrative disagrees with today's price. → See where this Narrative says Imperial Oil should trade
Which Company Could Surprise You Next?
By the time a rally makes headlines, you are reading about returns someone else has already earned. Why not go straight to the source and look for your own contrarian opportunity? These three companies trade below our estimated value.
- Company 1 - 45% below our estimate - accelerates higher grade ore feed and advances new underground mine development.
- Company 2 - 23% below our estimate - expands specialty retail boutiques while introducing a new app and eCommerce upgrades.
- Company 3 - 43% below our estimate - ramps high-speed networking and AI hardware programs targeting large-scale infrastructure buyers.
Those are three of them. See every one of the 8 solid balance sheet companies →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com