
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Undiscovered Gems in Global Markets for October 2026
As global markets navigate volatility driven by Middle East tensions, fluctuating oil prices, and mixed performances across major indices, investors are increasingly looking toward small-cap stocks for potential opportunities. In this environment, identifying undiscovered gems requires a keen eye for companies that demonstrate resilience and adaptability amidst economic shifts and sector-specific challenges.
Top 10 Undiscovered Gems With Strong Fundamentals Globally
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| Ad-Sol Nissin | NA | 7.22% | 15.60% | ★★★★★★ |
| Chongqing Machinery & Electric | 18.92% | 8.43% | 26.16% | ★★★★★★ |
| Xiamen King Long Motor Group | 93.39% | 11.34% | 66.65% | ★★★★★☆ |
| Forth Smart Service | 44.85% | -3.80% | 10.19% | ★★★★★☆ |
| Silvery Dragon Group Tianjin | 25.01% | 2.55% | 25.62% | ★★★★★☆ |
| Skue Sparebank | 122.31% | 16.16% | 27.93% | ★★★★☆☆ |
| Sing Investments & Finance | 0.10% | 5.85% | 7.00% | ★★★★☆☆ |
| Shengda ResourcesLtd | 57.58% | 8.61% | 9.90% | ★★★☆☆☆ |
| Primo Global Holdings | 64.63% | 9.93% | 28.27% | ★★★☆☆☆ |
| Bastide Le Confort Médical | 263.37% | 2.00% | -22.93% | ★★★☆☆☆ |
Below we spotlight a couple of our favorites from our exclusive screener.
VBG Group (OM:VBG B)
Simply Wall St Value Rating: ★★★★★☆
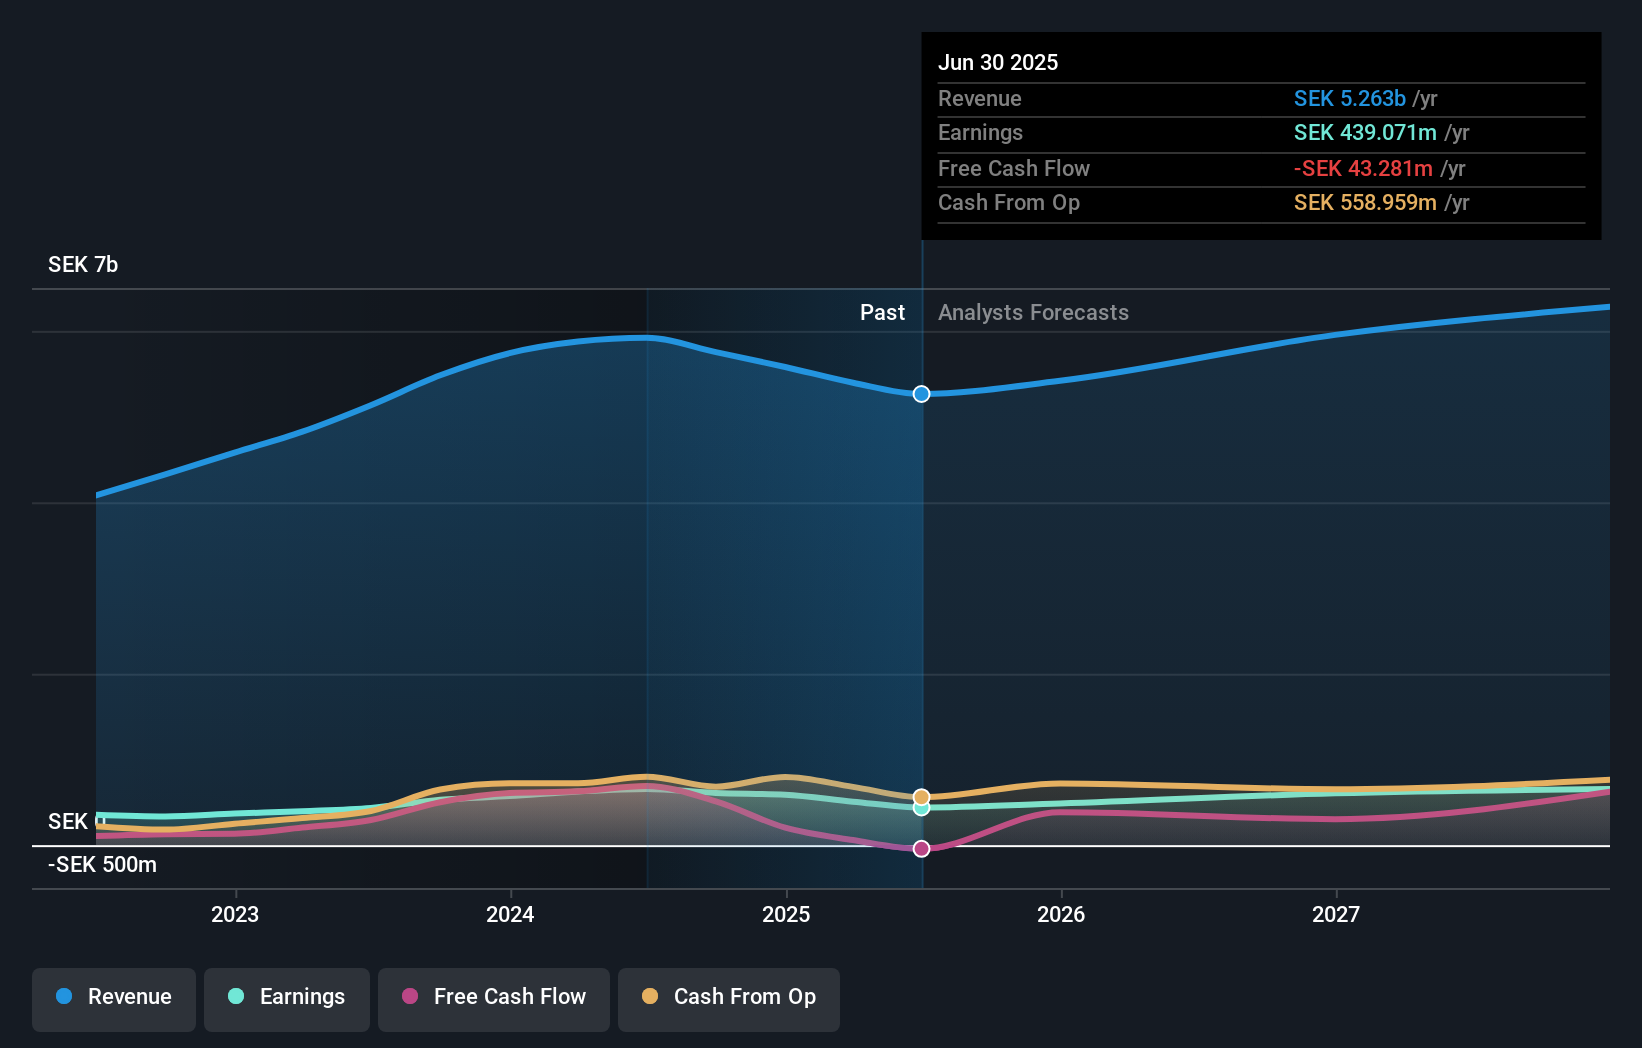
Overview: VBG Group AB (publ) is a company that develops, manufactures, markets, and sells industrial products across multiple regions including Europe, North America, and Asia with a market capitalization of approximately SEK7.85 billion.
Operations: The company's revenue is primarily generated from three segments: Mobile Thermal Solutions (SEK2.81 billion), Truck & Trailer Equipment (SEK1.64 billion), and RINGFEDER Power Transmission (SEK1.09 billion).
VBG Group, a smaller player in the machinery sector, is showing promising signs despite some challenges. Over the past year, earnings grew by 4.5%, outpacing the industry's -0.5% performance. The company trades at 56% below its estimated fair value and maintains a satisfactory net debt to equity ratio of 17.4%. While its debt to equity ratio rose from 30.6% to 41.4% over five years, interest payments are well covered by EBIT at 14 times coverage, indicating strong financial health. Recent executive changes in their Mobile Thermal Solutions division aim to bolster strategic priorities without impacting long-term direction significantly.
- Unlock comprehensive insights into our analysis of VBG Group stock in this health report.
Gain insights into VBG Group's historical performance by reviewing our past performance report.
Tachibana Eletech (TSE:8159)
Simply Wall St Value Rating: ★★★★★☆
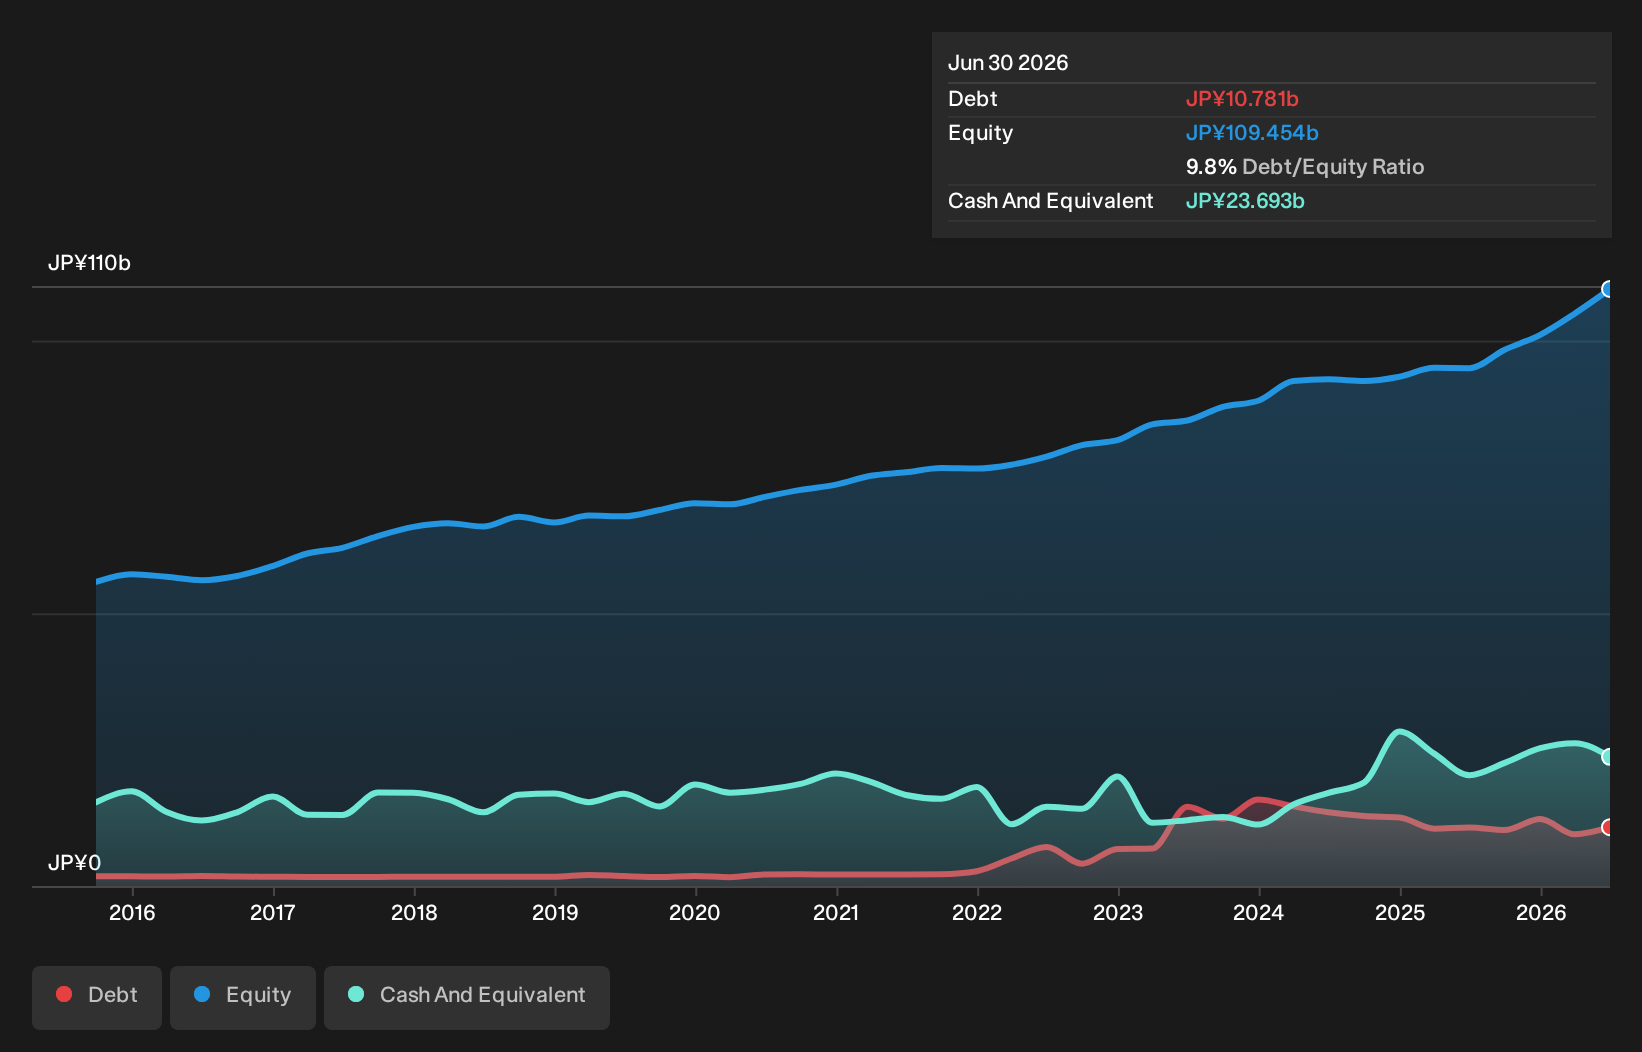
Overview: Tachibana Eletech Co., Ltd. is a technology-driven trading company operating both in Japan and internationally, with a market cap of ¥101.20 billion.
Operations: Tachibana Eletech generates revenue through its technology-driven trading operations across Japan and international markets. The company's financial performance is characterized by its net profit margin, which has shown notable trends over recent periods.
Tachibana Eletech's earnings growth of 33.9% over the past year outpaced the electronic industry average of 23.9%, showcasing its strong performance. The company holds more cash than its total debt, indicating a healthy financial position, while trading at a value 21.3% below estimated fair value suggests potential for investors seeking undervalued opportunities. Recent guidance revisions highlight an expected increase in net sales to ¥255 billion and operating profit to ¥9.5 billion for the fiscal year ending March 2027, driven by robust demand in Factory Automation Systems and Semiconductors & Electronic Devices sectors alongside improved order environments and stable supply management.
- Click here to discover the nuances of Tachibana Eletech with our detailed analytical health report.
Gain insights into Tachibana Eletech's past trends and performance with our Past report.
Maruzen Showa Unyu (TSE:9068)
Simply Wall St Value Rating: ★★★★★★
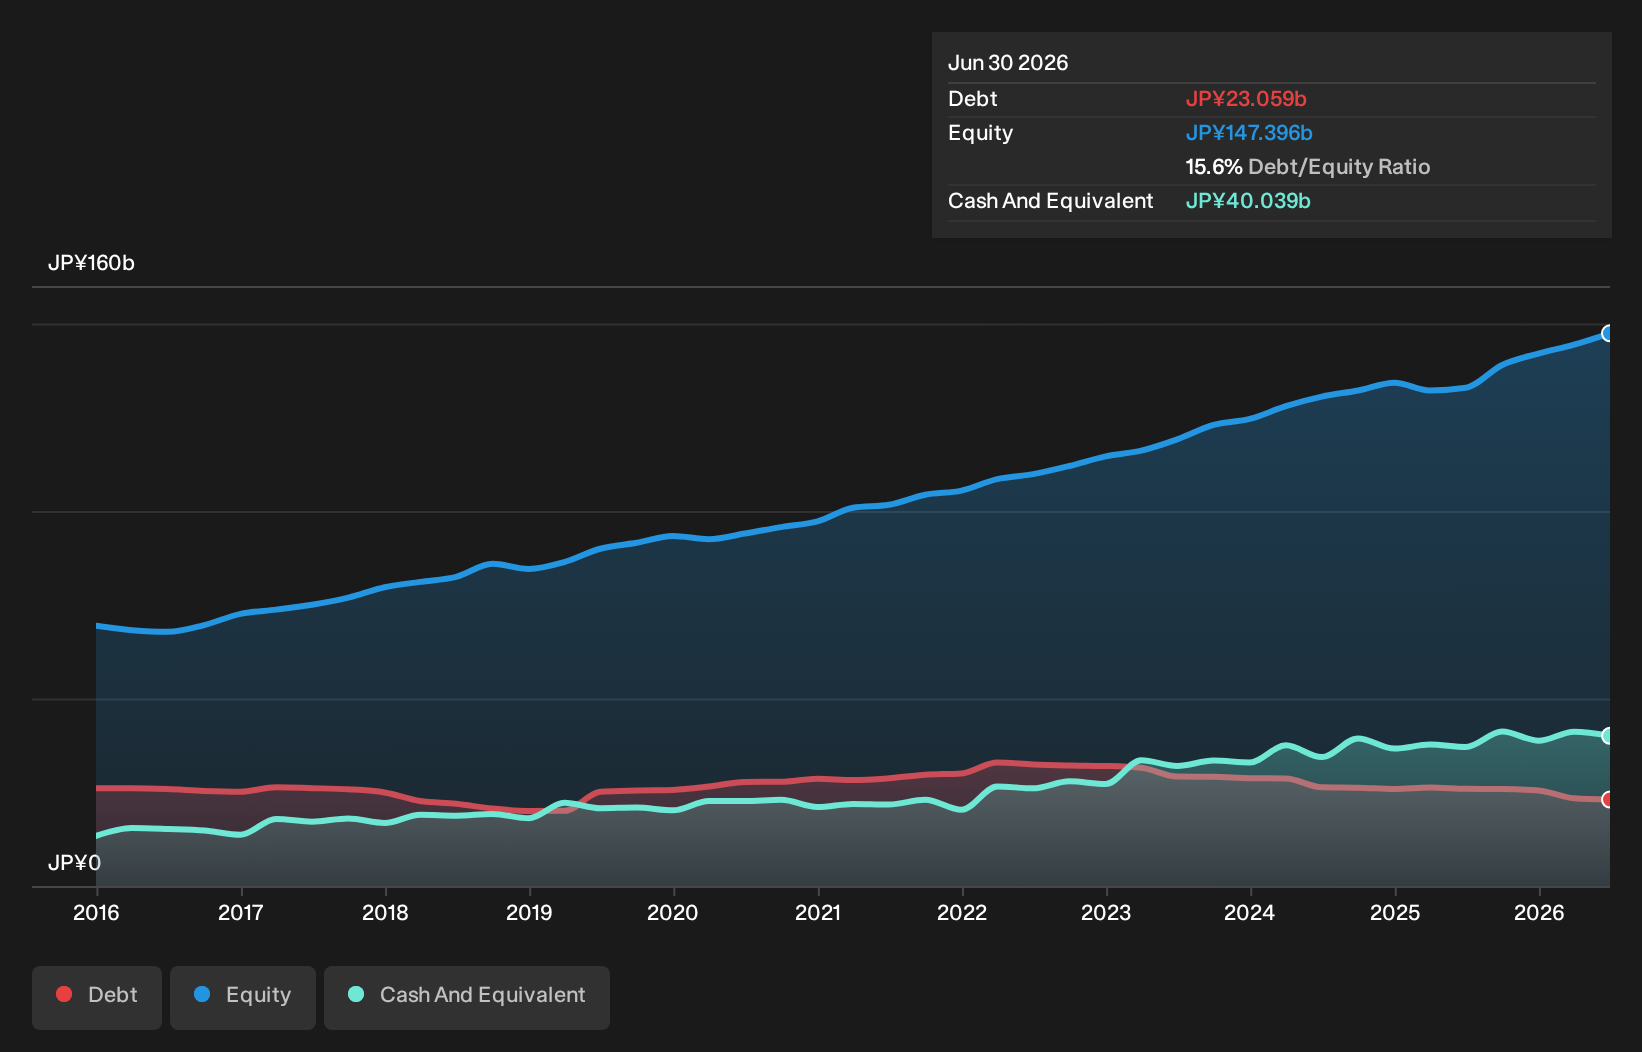
Overview: Maruzen Showa Unyu Co., Ltd. is a company involved in logistics operations both domestically and abroad, with a market capitalization of approximately ¥141.31 billion.
Operations: The primary revenue stream for Maruzen Showa Unyu comes from its logistics business, generating ¥130.92 billion, complemented by the on-site work and mechanical cargo handling segment at ¥16.97 billion. The company's net profit margin reflects its financial efficiency in managing operational costs relative to its total revenue.
Maruzen Showa Unyu, a notable player in the transportation sector, has seen its earnings grow by 24.1% over the past year, outpacing the industry's 10.6% growth rate. The company is trading at a value 20.5% below its estimated fair value and holds more cash than total debt, reflecting financial stability with a reduced debt-to-equity ratio from 28.3% to 15.6% over five years. Recent developments include a strategic move with a 2-for-1 stock split effective October 2026 and dividend guidance of JPY 220 per share for fiscal year ending March 2027, enhancing shareholder returns amidst robust financial performance indicators like high-quality earnings and positive free cash flow trends.
- Click here and access our complete health analysis report to understand the dynamics of Maruzen Showa Unyu.
Explore historical data to track Maruzen Showa Unyu's performance over time in our Past section.
Where To Now?
- Unlock our comprehensive list of 176 Global Undiscovered Gems With Strong Fundamentals by clicking here.
- Hold shares in these firms? Setup your portfolio in Simply Wall St to seamlessly track your investments and receive personalized updates on your portfolio's performance.
- Take control of your financial future using Simply Wall St, offering free, in-depth knowledge of international markets to every investor.
Ready For A Different Approach?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com