
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is UnitedHealth Group (UNH) Reasonably Priced After Raised 2026 Guidance?
UnitedHealth Group has rallied strongly in 2026, and that climb puts fresh focus on a simple question for you as a shareholder or potential buyer. Is the current share price fairly supported by the earnings power the business is generating today and is expected to produce in the years ahead?
- The stock is up 20.9% year to date, which raises the stakes on whether recent gains are fully backed by the profit stream investors are paying for.
- Recent profit and cost trends suggest the company may support expectations for future earnings and cash generation that are key to any earnings based valuation.
- The analysts covering UnitedHealth Group have run their own numbers. See what analysts think UnitedHealth Group's shares could be worth.
The issue now is whether UnitedHealth Group's current valuation can be justified by its earnings when viewed through this lens.
To see how this kind of earnings backed story compares with other opportunities, compare UnitedHealth Group with 33 high quality undervalued stocks.
Is UnitedHealth Group a Bargain on Earnings?
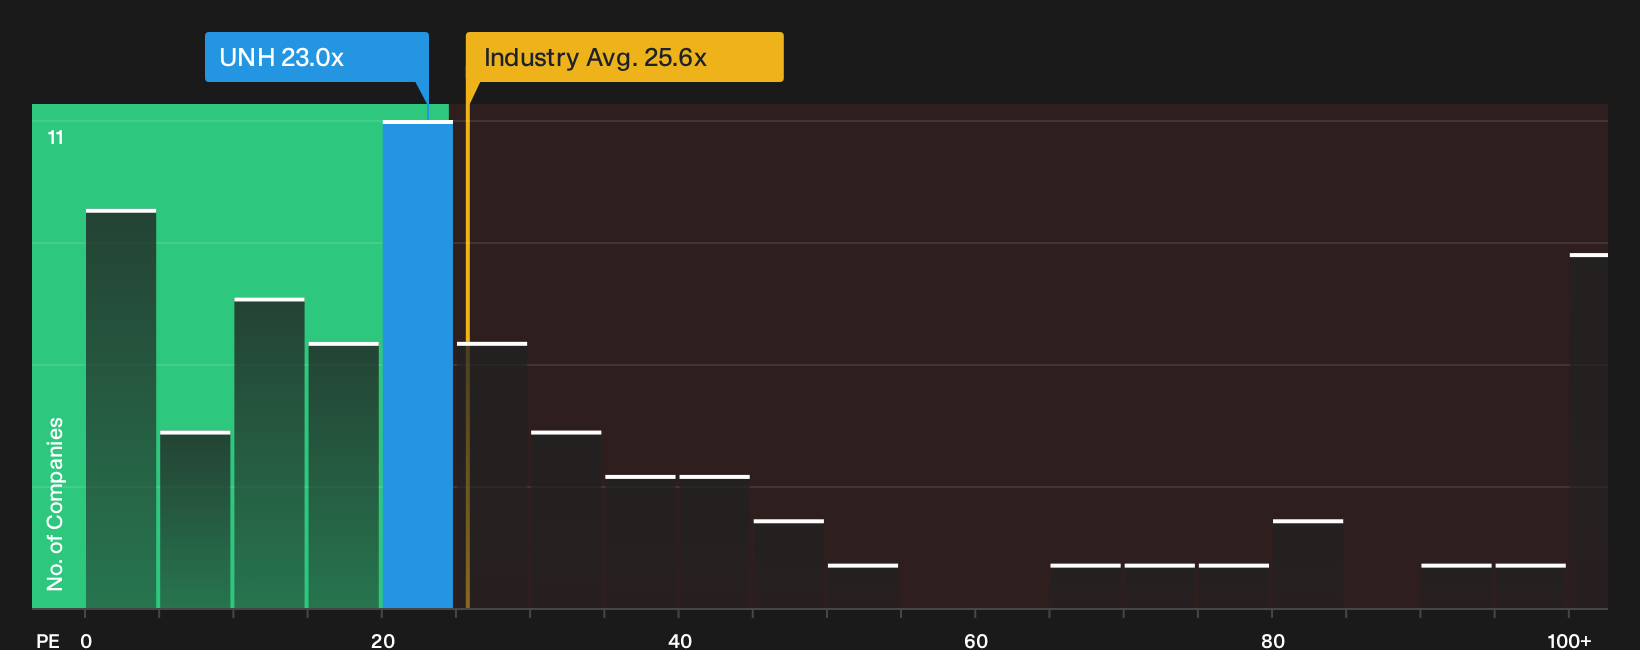
The P/E ratio works well for UnitedHealth Group because earnings are a major driver of how investors frame the business today. On current numbers, the stock trades at about 23.0x earnings, which sits below the wider Healthcare sector average of roughly 25.6x and well under the peer group on around 29.0x. That means the market is pricing each dollar of UnitedHealth Group earnings at a lower level than many comparable insurers and healthcare service providers.
Because the Fair Ratio reflects what investors might expect to pay for UnitedHealth Group given its margins, growth profile, scale and risk, the current 23.0x is below that modelled level and screens as undervalued on this framework. The recent Q3 beat and higher 2026 EPS guidance have lifted confidence, yet the P/E still reflects a discount to both the industry and closer peers. This suggests expectations for the business remain more restrained than the latest results alone might imply. Explore the numbers behind UnitedHealth Group's P/E valuation.
The UnitedHealth Group Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E question for UnitedHealth Group leaves off by outlining what combination of future growth, margins and earnings would need to materialise for the stock to be worth materially more or materially less than today's market price on the Community page. Each narrative links a fair value to a specific view of UnitedHealth Group's potential catalysts and key risks so you can track over time which storyline appears to be unfolding.
Community views on UnitedHealth Group are now split between AI-driven margin repair and integration risk that could justify a much lower multiple.
Bull case: 16% undervalued
"The company continues to invest in technology that improves physician workflows and digital engagement, and the current AI program that targets billions of dollars of G&A savings..."
Discover why this Narrative puts UnitedHealth Group at 16% undervalued.
Bear case: 32% overvalued
"The risk is not collapse, but compression, if regulatory pressure increases or if Optum’s growth slows, multiples could contract..."
Explore why this Narrative puts UnitedHealth Group at 32% overvalued.
One more UnitedHealth Group question the valuation alone cannot answer
Price multiples frame what you pay for UnitedHealth Group today, but professional estimates for earnings a few years out give you a separate reference point to compare with that sticker price. Explore where analysts expect UnitedHealth Group to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com