
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Digital Billboard Expansion Altering The Investment Case For Lamar Advertising (LAMR)?
- Lamar Advertising Company recently held its Q2 2026 earnings call, updating investors on financial performance and progress expanding its digital billboard network and advertising offerings.
- The emphasis on growing digital units and broader ad formats highlights how Lamar Advertising is trying to deepen revenue from its existing outdoor footprint.
- Next, the focus turns to how Lamar Advertising's investment narrative could be influenced by this push to scale its digital billboard network.
Scan beyond Lamar Advertising and explore other outdoor and media plays where digital formats could represent the next earnings catalyst with our hand-picked 20 high quality undiscovered gems
Lamar Advertising Investment Narrative Recap
Lamar Advertising asks you to believe in a fairly simple idea. Out of home demand keeps supporting its 362,000 plus displays, and the shift toward digital units and programmatic bookings lets the existing footprint earn more per location. The latest call reinforces that management is still leaning into digital conversion and efficiency, rather than chasing entirely new business lines.
The most important near term swing factor is execution on digital and programmatic billboards, because those already account for a meaningful share of billboard revenue. The key risk is cost creep and funding pressure, with higher revenue sharing leases, commissions and a high debt load potentially squeezing how much falls through to earnings.
The Q2 2026 update on digital billboards is the announcement to watch. Digital already delivers around one third of billboard revenue, with mid teens growth and 6.5% same board gains, and programmatic now about 10% of digital billboard revenue and up more than 50% year on year. That is where Lamar Advertising can influence yield without needing huge geographic expansion.
On the same call, management pointed to a record 49.2% EBITDA margin in Q2 2026 and a goal of keeping consolidated margins above 48% by 2028. Your focus as a shareholder is whether ERP and AI driven efficiencies, plus disciplined contracts and acquisitions, offset higher acquisition adjusted expenses and any ongoing equity issuance that dilutes per share outcomes.
Lamar Advertising's current analyst narrative points to revenues of US$2.6b and earnings of US$764.4m by 2029, based on an assumed 4.4% yearly revenue growth rate and a move from US$555.7m of earnings today to that 2029 consensus, which is an increase of about US$208.7m.
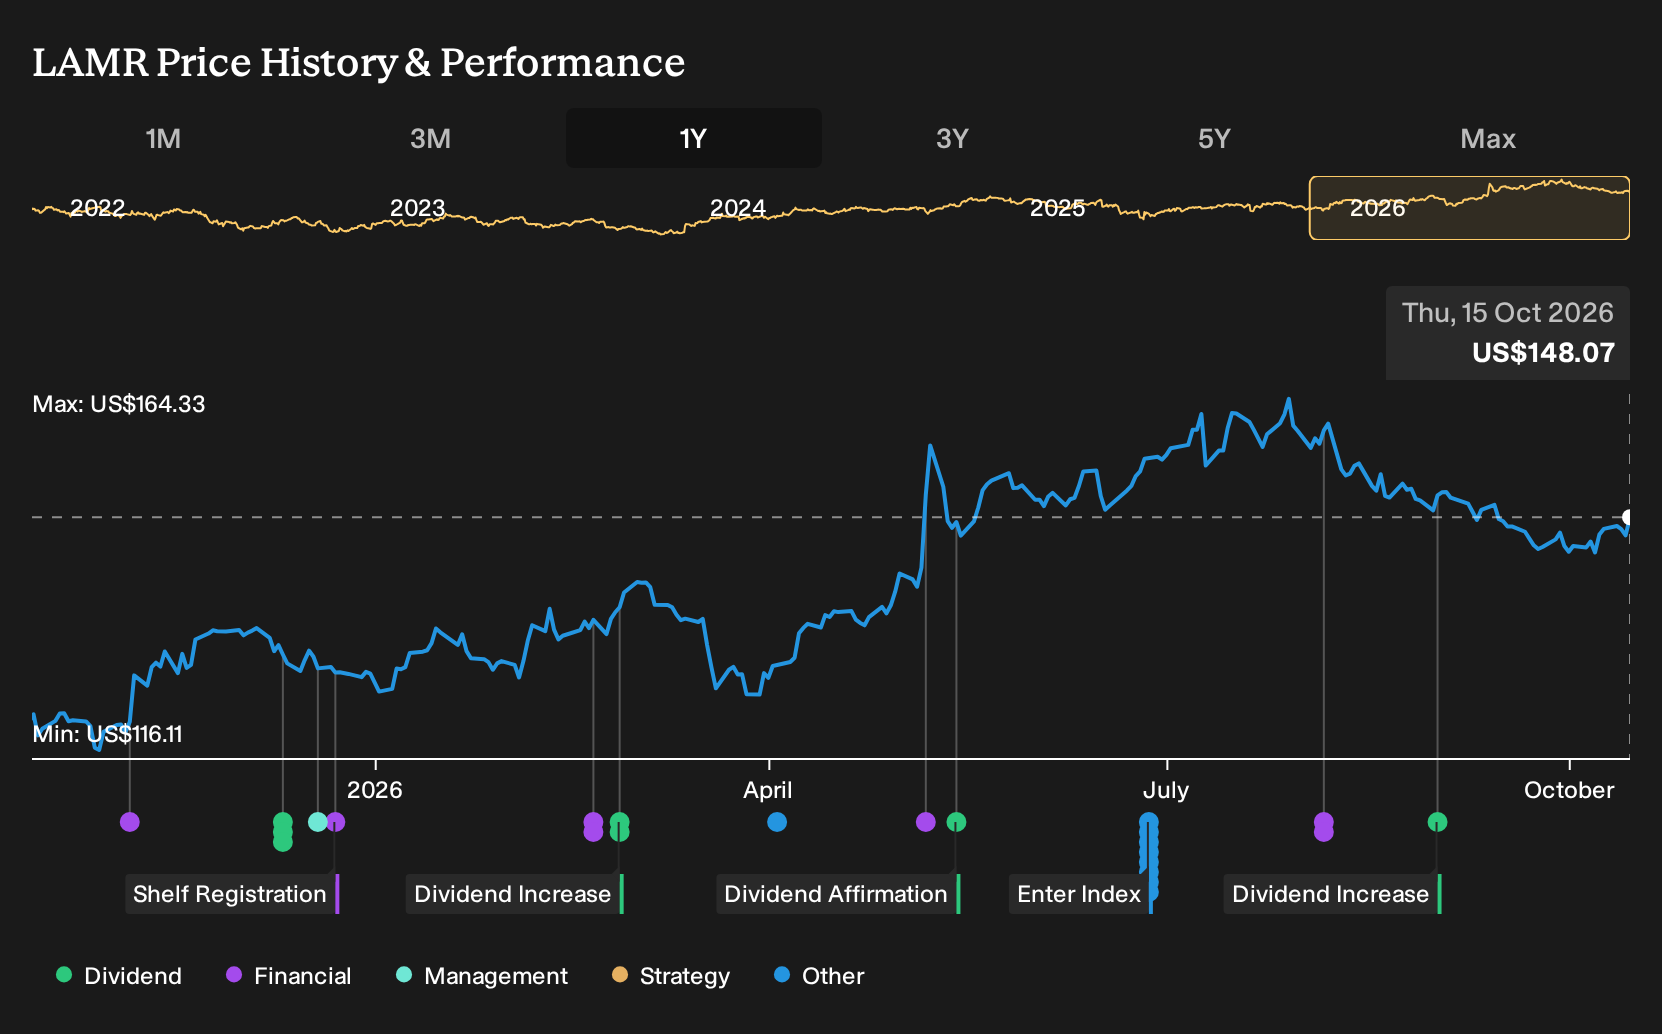
Discover how Lamar Advertising's fair value indicates a 10% potential upside to its current price that could close more quickly than many investors expect.
Exploring Other Perspectives
Lamar Advertising attracts only 2 fair value estimates from the Simply Wall St Community, yet they already span roughly US$162 to US$235 per share. That wide band, set before the Q2 2026 update, reflects fresh risks around higher expenses and dilution, as well as digital and programmatic catalysts that could influence how you think about future performance.
Explore another Lamar Advertising fair value estimate, including one that suggests it could be worth just $162.20.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Lamar Advertising research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Lamar Advertising. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Lamar Advertising's overall financial health at a glance.
Looking for more ideas beyond Lamar Advertising?
Once you have formed a view on Lamar Advertising, it often helps to compare it with a wider set of opportunities so you can decide where your next dollar of capital works hardest.
- If you want potential mispricing opportunities with quality metrics to back them up, scan through our hand picked mix of 33 high quality undervalued stocks that blend fundamentals with attractive pricing.
- Income focused investors who care about durability as much as yield can review a curated pool of 8 dividend fortresses to see which businesses might better match their payout goals.
- For those who prefer resilience first, start with a 32 resilient stocks with low risk scores that filters for companies aiming to keep risk scores in check while still offering room for upside.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com