
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Learn Why The Bull Case For Bank of Queensland Shares Could Change Following Earnings Results
- Bank of Queensland reported full year 2026 results with net interest income of A$1,527 million and net income of A$250 million, alongside basic earnings per share from continuing operations of A$0.381 and a fully franked final dividend of A$0.20 per share for the half year.
- Despite flat net interest income year on year, Bank of Queensland nearly doubled net income, which highlights a sharp shift in profitability relative to headline revenue.
- We will now look at how Bank of Queensland's investment narrative could be affected by the strong uplift in net income.
Scan beyond Bank of Queensland and compare its earnings and dividend profile with a curated 4 dividend fortresses that also focuses on income strength.
Bank of Queensland Investment Narrative Recap
To own Bank of Queensland, you need to be comfortable with a regional lender that is trying to simplify, lean into digital, and squeeze more earnings out of a relatively steady income line. The sharp uplift in net income to A$250 million, while net interest income stayed flat at A$1,527 million, suggests better efficiency and margin management. That supports the near term catalyst around executing its transformation without losing revenue momentum.
The biggest near term risk still sits in margin pressure from competition and regulation, along with any credit quality hits if conditions soften. Franchise to corporate branch conversion, tech investment and a shift in lending mix can all stress costs and capital if execution wobbles. The latest result does not remove those risks, but it does show some breathing room on profitability.
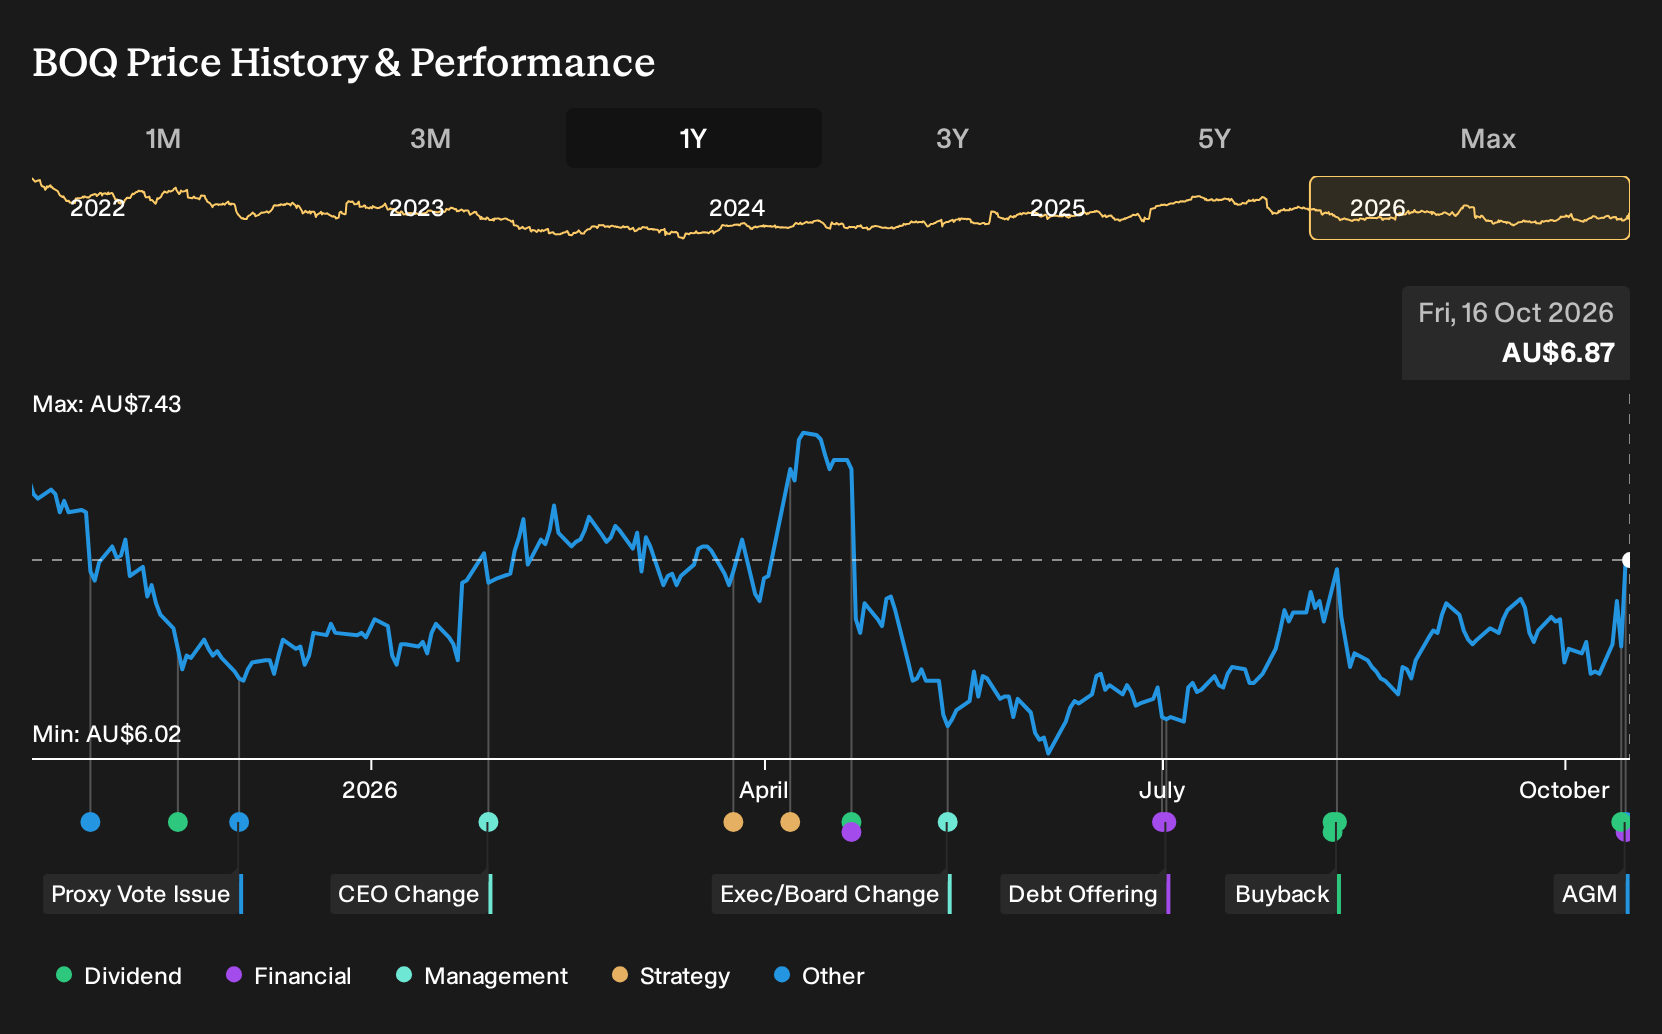
The dividend affirmation on 14 October 2026 is the most relevant piece for this earnings story. A fully franked A$0.20 per share ordinary dividend for the six months to 31 August 2026 ties the stronger net income directly to cash returning to shareholders. For an income focused holder, that matters as much as the A$0.381 basic earnings per share figure.
At the same time, external analysis flags that the dividend yield around 5.82% is not viewed as well covered by current or forecast earnings. That means payout sustainability sits right beside the digital simplification plan as a key catalyst and risk pair. If Bank of Queensland keeps improving earnings quality and cost efficiency, it gains more flexibility on maintaining that dividend through a tougher macro patch or higher regulatory spend.
Bank of Queensland's narrative projects A$1.7b revenue and A$374.8 million earnings by 2029. This assumes 1.6% yearly revenue growth and an earnings increase of about A$276.8 million from A$98.0 million today.
Discover why Bank of Queensland's fair value indicates an 8% potential downside to its current price, leaving little room for error.
Exploring Other Perspectives
Three fair value views from the Simply Wall St Community cluster tightly between A$5.92 and A$6.31, so you are not looking at wild outliers, yet opinions can still diverge sharply once fresh earnings, dividend affirmation and ongoing regulatory and competition risks are layered in. Explore those alternative takes before anchoring on one story for Bank of Queensland.
Explore 2 other Bank of Queensland fair value estimates, including one that suggests it could be worth as much as A$6.31.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Bank of Queensland research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Bank of Queensland. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Bank of Queensland's overall financial health at a glance.
Looking for more investment ideas beyond Bank of Queensland?
If you want to put Bank of Queensland in context, it helps to line it up against other companies with different income, value and balance sheet profiles. Use the Simply Wall St Screener to see how it stacks up and to surface a few fresh candidates for your watchlist.
- For investors who like to hunt at the smaller end of the market, consider scanning a focused group of 19 elite penny stocks with strong financials that already show stronger fundamentals than many peers.
- If value is your priority, compare Bank of Queensland with a 4 high quality undervalued stocks that blends quality metrics with pricing that some might see as appealing.
- For a focus on resilience, weigh this regional bank alongside a 6 resilient stocks with low risk scores that filters for sturdier balance sheets and lower overall risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com