
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Melrose Industries (LSE:MRO) Could Be 28% Undervalued On Margin Pressure And $125 Million Settlement
Melrose Industries (LSE:MRO) is back in focus after a $125 million settlement tied to GKN Aerospace's Garden Grove site and a sharp H1 2026 net margin slide from 16.6% to 4.0%.
Melrose Industries’ £4.777 share price has moved sharply in the short term, with a 7 day share price return of 8.99% and a 1 day gain of 1.23%. This comes even though the year to date share price return is down 21.69% and the 1 year total shareholder return has declined 21.42%. By contrast, the 5 year total shareholder return of 51.29% points to a much stronger long run journey and suggests recent settlement and margin headlines are being weighed against a longer history of value creation.
Stress test the Melrose Industries story against peers by reviewing hand picked 4 resilient stocks with low risk scores that prioritize balance sheet strength and tighter risk control.
After a fast rebound in Melrose Industries following the settlement and margin shock, the real tension is simple: Do you pay up for the bounce now or wait for a cheaper shot at the same earnings stream?
Most Popular Narrative: 28% Undervalued
Melrose Industries is priced at £4.78 against a widely followed fair value view of about £6.63. This frames the recent rebound as investors weighing short term margin noise against a much higher earnings and cash flow profile.
Completion of Melrose's multiyear transformation program, including global footprint consolidation, productivity initiatives, and ongoing cost optimization, is expected to yield sustained improvements in EBITDA margins and free cash flow as operational leverage and fixed-cost absorption increase across the streamlined core aerospace portfolio.
See why 37 investors see Melrose Industries as 28% undervalued.
Result: Fair Value of £6.63 (UNDERVALUED)
Still, the Melrose Industries story can break if aerospace demand stumbles or if high net debt and interest costs squeeze the already compressed net margin further.
Find out about the key risks to this Melrose Industries narrative.
Another View: What Melrose Industries’ P/E Is Telling You
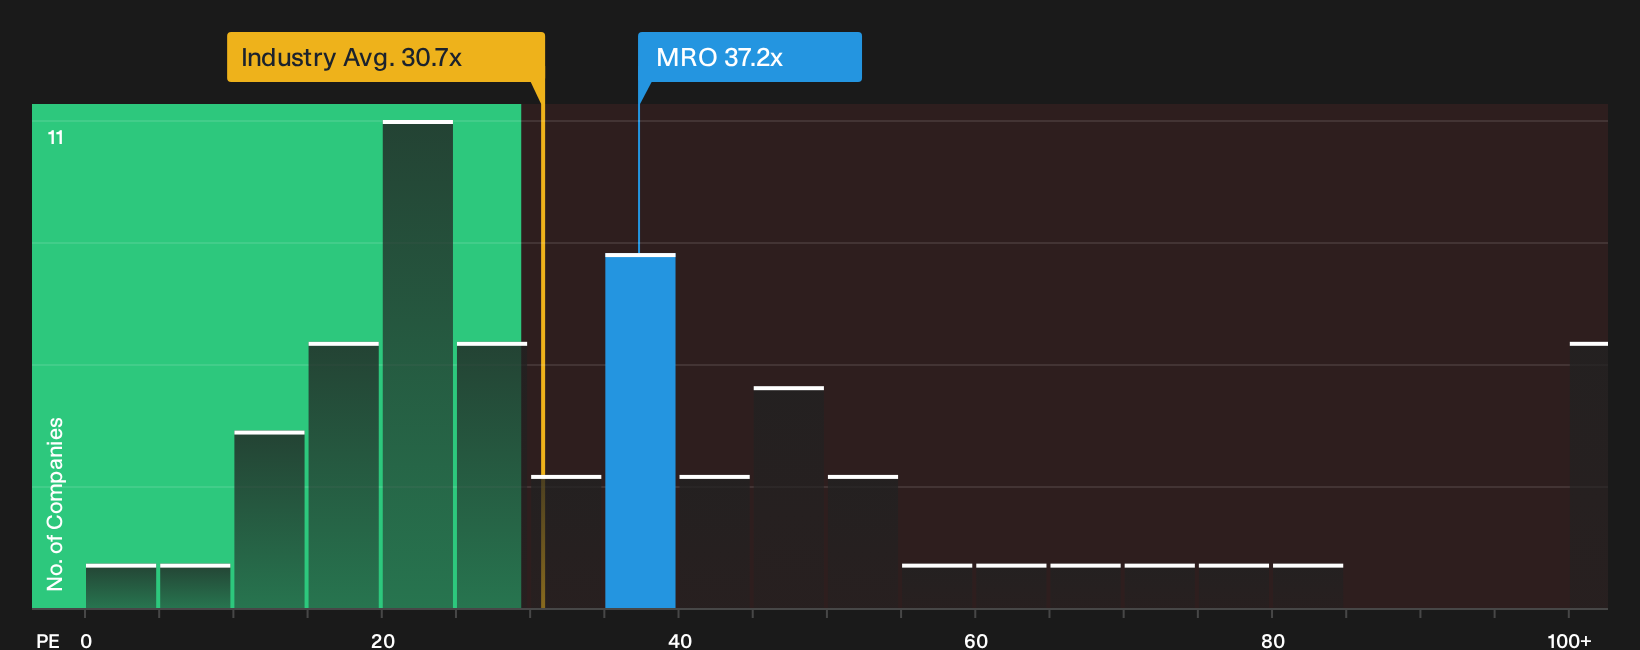
The first take paints Melrose Industries as about 31% undervalued, with fair value near £6.63 against a £4.78 share price. Yet the current P/E sits around 37x, which is higher than both the European aerospace and defense average of 30.2x and the peer group at 31.8x. That gap suggests the stock already carries a rich price tag relative to near term earnings, even if the fair ratio of 40.6x implies the market could be willing to stretch further. So the real question for you is whether to lean on the discounted cash flow style fair value or treat today’s premium multiple as a warning signal.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Melrose Industries so far. If you want to move faster than the headlines and form your own view, start by weighing the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Melrose Industries?
If Melrose Industries has sharpened your thinking, do not stop here. Broader idea flow helps you compare quality, price and risk more clearly.
- Target resilient balance sheets first and stress test your watchlist against the list of solid balance sheet and fundamentals (9 results) that already screen for financial strength.
- Spot potential mispricings early by scanning the 9 high quality undervalued stocks that blend quality fundamentals with prices that look out of line with business strength.
- Build a watchlist of potential future leaders by combing through the 5 high quality undiscovered gems that focus on strong, under the radar fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com