
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 British Penny Stocks To Watch In October 2026
Higher energy costs and Brexit related trade friction have kept many larger United Kingdom stocks in the spotlight, while a quieter story is playing out in the background. Smaller, lower priced businesses with relatively solid finances can give you targeted exposure without needing a huge outlay. This article highlights three financially fitter penny stocks from the UK market that may be worth a closer look on your watchlist.
The three stocks highlighted here offer a compelling starting point if you want exposure to lower risk early-stage businesses backed by relatively solid financial health. However, if you want the absolute best, these 13 elite penny stocks are the cream of the crop.
Baltic Classifieds Group (LSE:BCG)
Baltic Classifieds Group runs online marketplaces across autos, property, jobs, services and general classifieds in the Baltics, with auto bringing in about €31 million, real estate €26 million, jobs and services €17 million, and generalist sites €14 million, supporting a roughly €969 million market value.
Baltic Classifieds Group fits the Financially Fit Penny Stocks theme through its recurring listing and advertising income, which can underpin steadier cash flow than many early-stage peers and helps explain why investors are watching how its digital platforms evolve.
Rapid rollout of AI and data driven tools, such as smart pricing, salary estimators, fraud screening and lead management, is enhancing platform utility for buyers and sellers, which can help justify ongoing price increases and support EBIT and EBITDA.
What happens to that profit profile depends heavily on how one pressure on its core listing volumes and pricing power ultimately resolves.
How that pressure plays out is exactly what the full narrative for Baltic Classifieds Group unpacks, including where Baltic Classifieds Group could still accelerate if listing volumes stall.

Ashmore Group (LSE:ASHM)
Ashmore Group gives you exposure to emerging market bonds and equities through fee based investment management, with all of its £139 million revenue coming from providing these services and a market value of about £1.45b anchoring it firmly in the Financially Fit Penny Stocks theme.
Ashmore Group matters here because it offers access to higher risk emerging markets through a business model that leans on recurring investment fees rather than heavy borrowing. This fits the idea of targeting financially fitter penny stocks with more robust underlying franchises.
Although Ashmore Group reports higher fee margins and EBITDA margins in local offices such as Colombia and Indonesia, the group level still absorbs currency headwinds and lower performance fees. Any slowdown in these local platforms could leave overall revenue and operating margins exposed to the same pressures that pulled adjusted net revenue down 7% in FY26.
The key issue is whether a subtle shift in how that fee engine develops can keep profitability looking as resilient as it does today.
That resilience question is exactly what the full narrative for Ashmore Group unpacks, showing where Ashmore Group’s fee engine could decouple from market swings and where current headwinds might be masking potential strength.

Currys (LSE:CURY)
Currys runs a broad tech retail operation across the UK and Nordics, but what really ties it into the Financially Fit Penny Stocks theme is the recurring after sales services around repairs, credit and third party insurance layered onto mass market electronics.
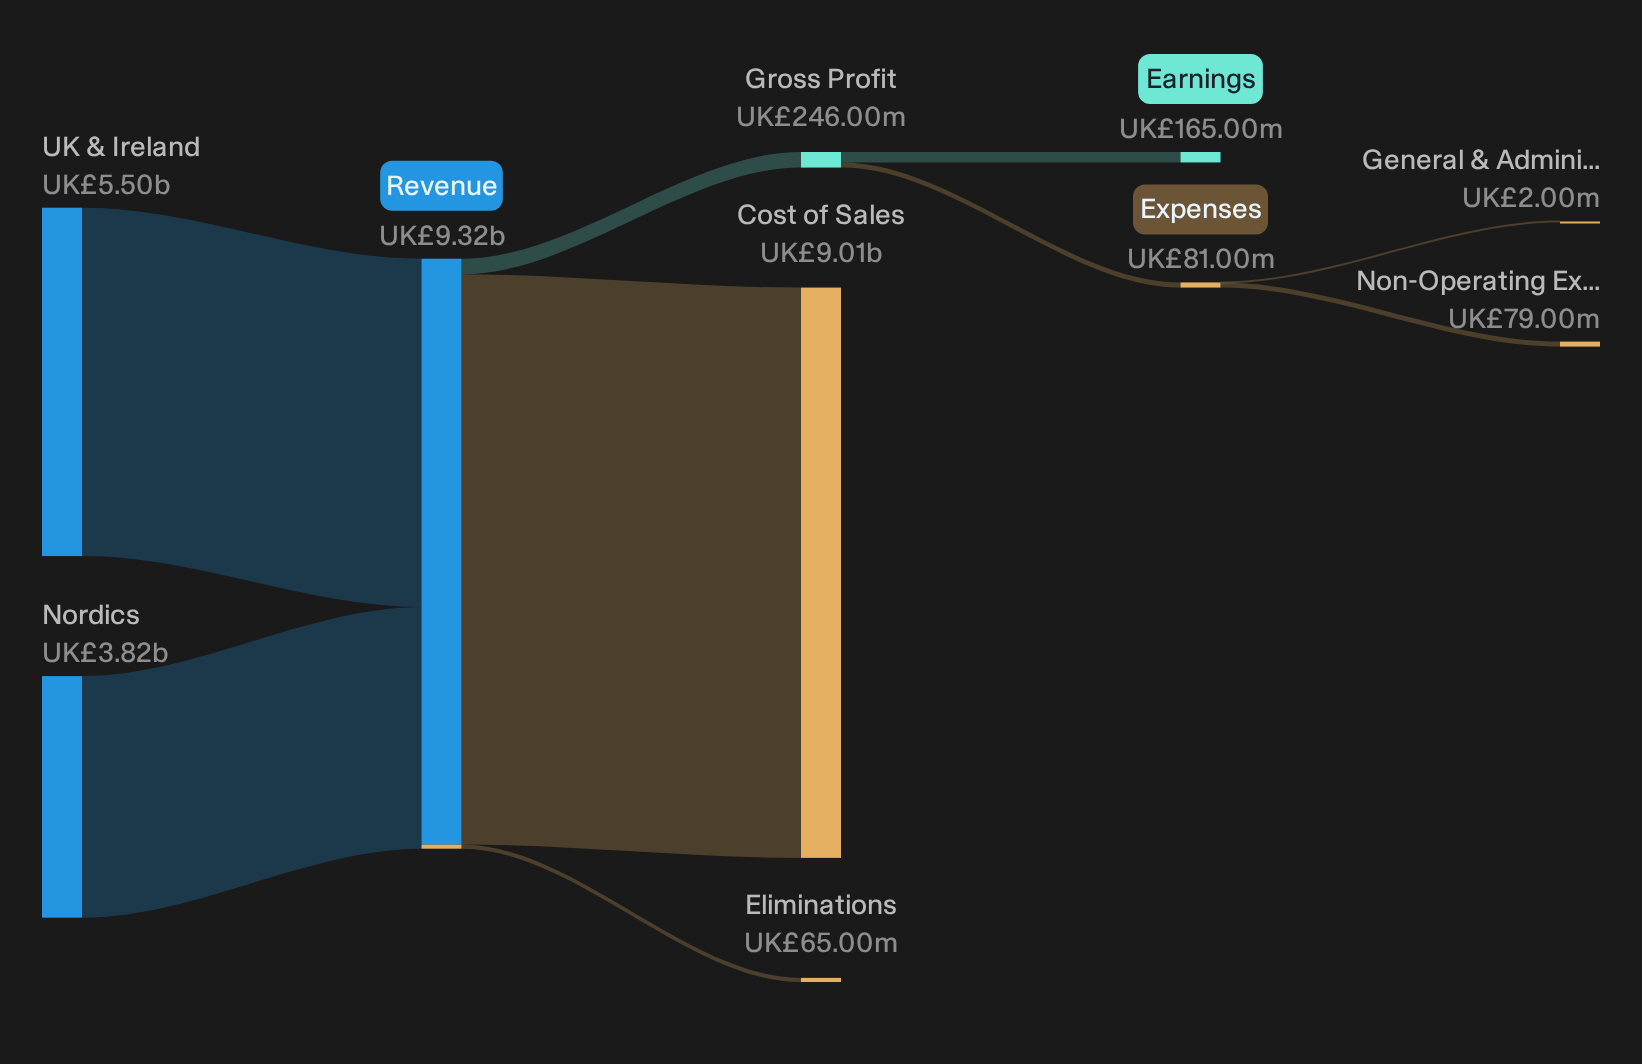
Currys generates about £5.5b from UK & Ireland and £3.8b from the Nordics, and with a market cap near £1.6b it is a sizeable listed retailer rather than a tiny gadget outlet, even though many of its products and services are low ticket and repeat purchase.
Currys brings that theme to life by selling everyday electronics, then staying in the customer’s pocket through repairs, support agreements and mobile services that can repeat over years instead of ending with a single basket.
Although Currys highlights recurring services such as credit, installations, repairs and iD Mobile as a growing share of UK sales with higher margins than product only transactions, the very small contribution of complete solutions that carry much higher margins leaves a large gap between the current mix and the level of high margin attachment implied by long term plans.
What happens if the current push to deepen those higher margin relationships either falls short or catches on faster than the market expects?
If that shift in higher margin attachment is what you are watching, read the full narrative for Currys to see how Currys’ services push could accelerate from here.
Seeking Alternatives Before Others Catch On?
Fresh ideas move first. The most interesting opportunities gain momentum while data is still under the radar for now. Scan these curated shortlists before potential breakouts and consider your options early.
- Spot resilient payers that keep income flowing by reviewing the 4 dividend fortresses before yields are chased lower by income hunters.
- Track next-wave automation leaders preparing to reshape factory floors and logistics by scanning the 91 robotics and automation stocks while expectations are still catching up.
- Explore the build out behind AI capacity by checking the 94 AI infrastructure stocks as infrastructure spending develops.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com