
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Churchill Downs (CHDN) Could Be 37% Undervalued After Argus Lifts Target Price
Argus recently raised its target price for Churchill Downs (CHDN) to $77, putting fresh attention on how the gaming and racing operator’s fundamentals align with market expectations and current share performance.
Churchill Downs has seen a sharp short-term rebound, with a 1-day share price return of 2.66% and a 7-day share price return of 7.87%. However, momentum looks fragile given the share price is down 26.62% year to date and the 5-year total shareholder return is down 34.75%, signaling that recent optimism is still set against a longer period of weak overall investor returns.
Compare Churchill Downs with a curated group of gaming and leisure operators by scanning the 20 high quality undiscovered gems that currently sit off most investors’ radar.
After Churchill Downs bounced hard in the past week but remains deeply in the red this year, the real tension is simple: Does patience for a cheaper entry beat paying up for this reset?
Most Popular Narrative: 37% Undervalued
On the most followed view, Churchill Downs screens as undervalued, with a fair value of $130.83 against a last close of $82.15. The gap between price and that narrative hinges on how management recycles capital and grows higher return assets.
The current valuation suggests the market is discounting Churchill Downs’ record free cash flow and EBITDA performance, the planned use of potential asset sale proceeds to reduce leverage and repurchase shares, and the view among some analysts that the stock is undervalued.
See why 7 investors see Churchill Downs as 37% undervalued.
Result: Fair Value of $130.83 (UNDERVALUED)
Still, the Churchill Downs story can break the wrong way if regional casino sales disappoint or if recent growth and free cash flow trends remain soft.
Find out about the key risks to this Churchill Downs narrative.
Another View: What Multiples Say About Churchill Downs
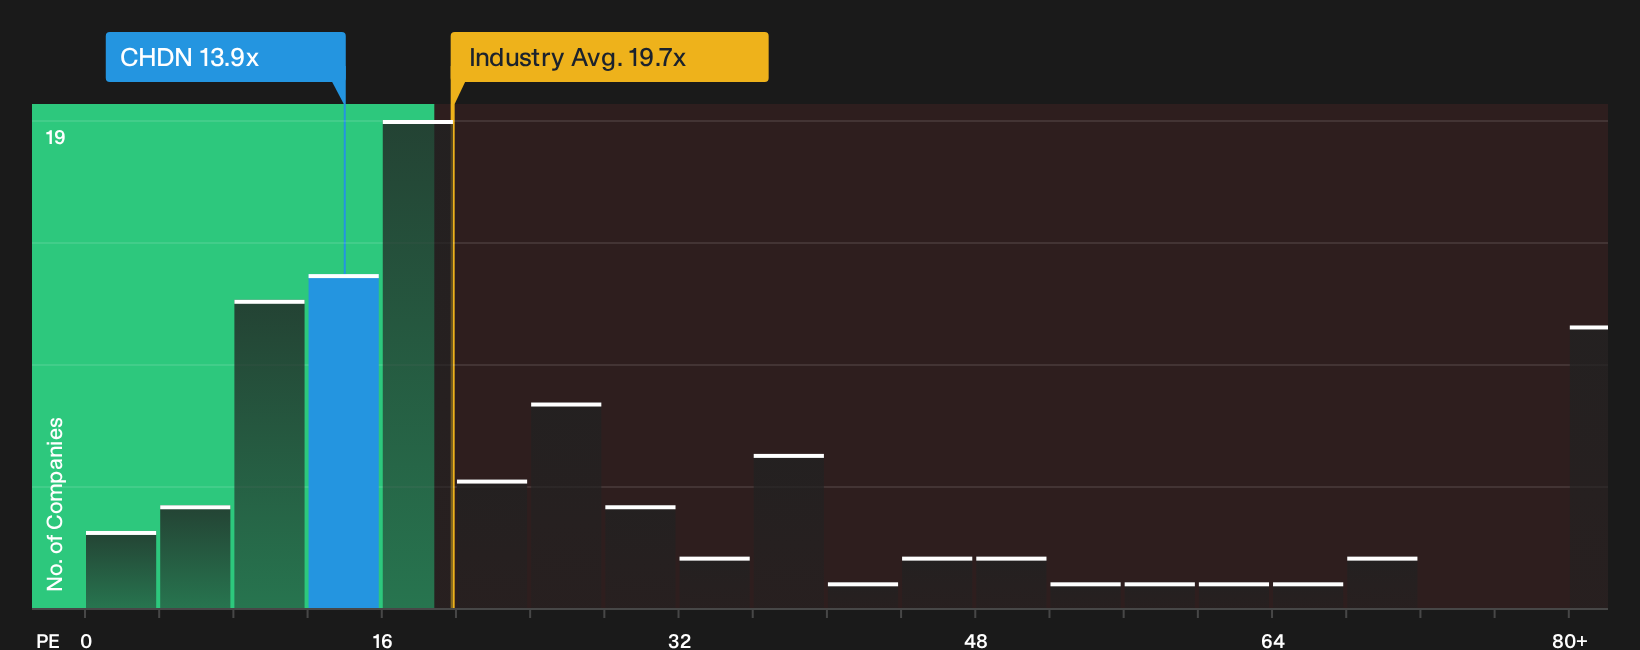
The DCF work points to upside for Churchill Downs, but the simple earnings multiple sends a cooler message. The stock trades on a P/E of 13.9x, slightly richer than direct peers at 13.3x, yet below the broader US Hospitality group at 19.8x and under a fair ratio of 19.4x. That mix of modest peer premium and wider gap to the fair ratio raises a practical question for you. Is this discount a margin of safety or a sign that the market is pricing in real execution risk?
To pressure test that view against hard numbers rather than headlines, you can compare the current P/E with our breakdown of relative valuation signals, including the fair ratio reference point, through See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If this Churchill Downs setup feels finely balanced, that is exactly the point, so move fast on the data and stress test the story for yourself. Then weigh the upside and downside in one place with the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Churchill Downs?
If the Churchill Downs setup has your attention, do not stop there. Broaden your watchlist now so you are not trailing better opportunities tomorrow.
- Target resilient balance sheets and steady fundamentals by scanning the list of solid balance sheet and fundamentals (25 results) to help anchor your portfolio when sentiment swings.
- Hunt for quality at a discount by reviewing the 33 high quality undervalued stocks that combine strong business profiles with prices that sit below their assessed worth.
- Prioritise sleep-at-night stability through the 32 resilient stocks with low risk scores that focus on businesses with more measured risk profiles and fewer financial red flags.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com