
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Why Crocs Stock Is Up 6.2% After Analyst Upgrade
- Barclays recently upgraded Crocs after the analyst highlighted clearer visibility into a broader business recovery across North America, international markets and the HEYDUDE brand.
- The focus on new product franchises beyond the Classic Clog and on continued international expansion points to a more diversified demand base for Crocs.
- Next, the investment narrative for Crocs will be weighed against Barclays' view that the planned recovery of HEYDUDE supports a broader business rebound.
Scan for other footwear and consumer brands that may be setting up for their own rebound with our curated list of 20 high quality undiscovered gems.
Crocs Investment Narrative Recap
To own Crocs, you need to be on board with a footwear portfolio that extends well beyond the Classic Clog and with a business leaning harder into direct to consumer and international demand. The key near term swing factor is whether HEYDUDE can shift from pressure to support, while tariffs and higher borrowing remain potential drags on margins.
The Barclays upgrade leans on improving visibility into that broader recovery, but it does not change the core near term catalyst or the main risks. Execution still has to show cleaner HEYDUDE trends, resilient demand in North America and overseas, and stable guidance that does not reset expectations lower.
The most relevant fresh data point here is Barclays outlining early signs of a recovery across Crocs North America, international markets and HEYDUDE. That commentary ties directly into existing catalysts around wider product franchises and a more global revenue mix, which are already key to the long term narrative for the brand.
If that recovery view proves accurate, it could support the existing plan built around sandals, Ballet Flat and Mellow, plus HEYDUDE extensions in work, boots and casual styles. If it stalls, the earlier risk list still bites, from tariff pressure on gross margin to investor focus on any softer guidance or future marketplace model changes in 2026.
Crocs' narrative projects US$4.3b revenue and US$731.6 million earnings by 2029, based on analyst assumptions of 1.7% yearly revenue growth and an earnings increase of about US$138.2 million from US$593.4 million today.
Uncover how Crocs' fair value indicates an 11% potential upside to its current price before the market closes that discount.
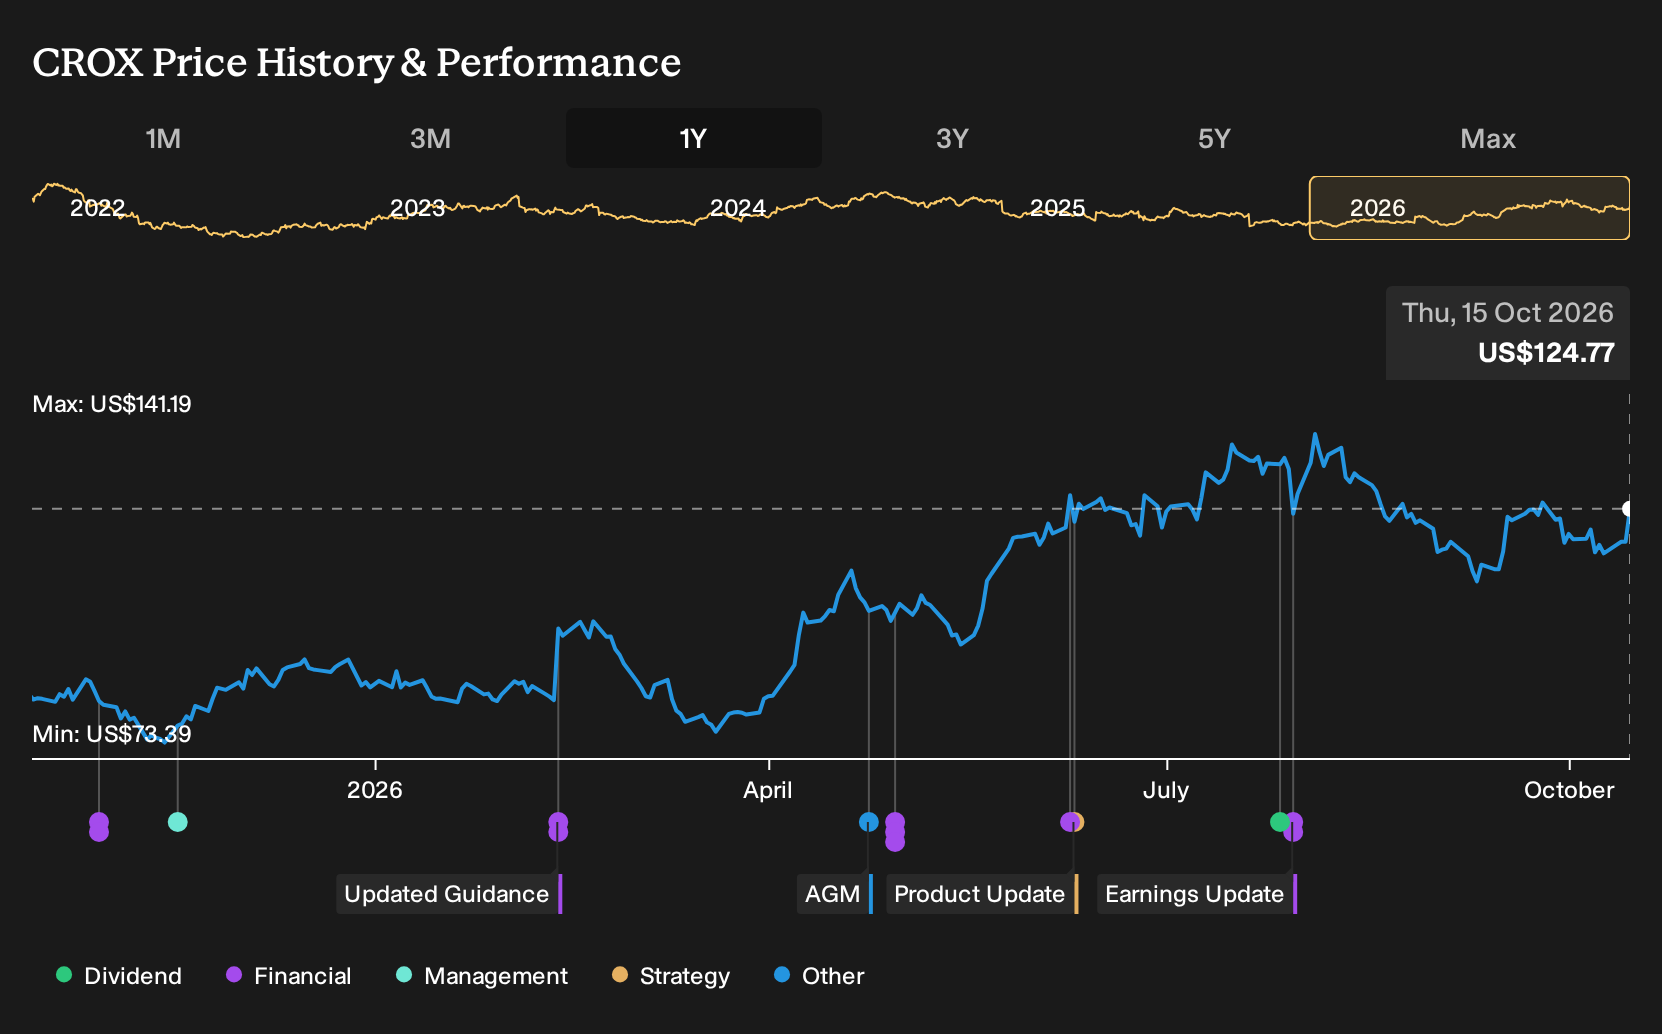
Exploring Other Perspectives
Some of the most optimistic analysts lean hard into Crocs’ digital and AI catalyst, arguing that a 10 year Infosys partnership could support higher earnings power than consensus implies. Before this Barclays news, that bullish group was already modeling about US$4.4b of 2029 revenue and US$814.5 million of earnings. You can compare those forecasts with more cautious views and decide which narrative feels closer to your own expectations, knowing this upgrade could still shift both camps.
Explore 5 other Crocs fair value estimates, including one that suggests as much as 67% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Crocs research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Crocs. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Crocs' overall financial health at a glance.
Looking For More Ideas Beyond Crocs?
If the Crocs story has sharpened your thinking and you want to apply the same lens to a broader opportunity set, the Simply Wall St Screener can help you quickly focus on stocks that fit different objectives, from value to resilience to balance sheet strength.
- If you want potential value combined with quality fundamentals, consider scanning through 33 high quality undervalued stocks that already clear a high bar on both earnings and financial stability.
- If capital preservation and steadier profiles matter more to you, filter the market using our 32 resilient stocks with low risk scores that score well on a broad mix of risk indicators.
- If you care most about financial resilience, start with the list of solid balance sheet and fundamentals (25 results) and focus on businesses with stronger cash positions and lower leverage.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com