
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Visteon Holders Got Wrong Before The Slide
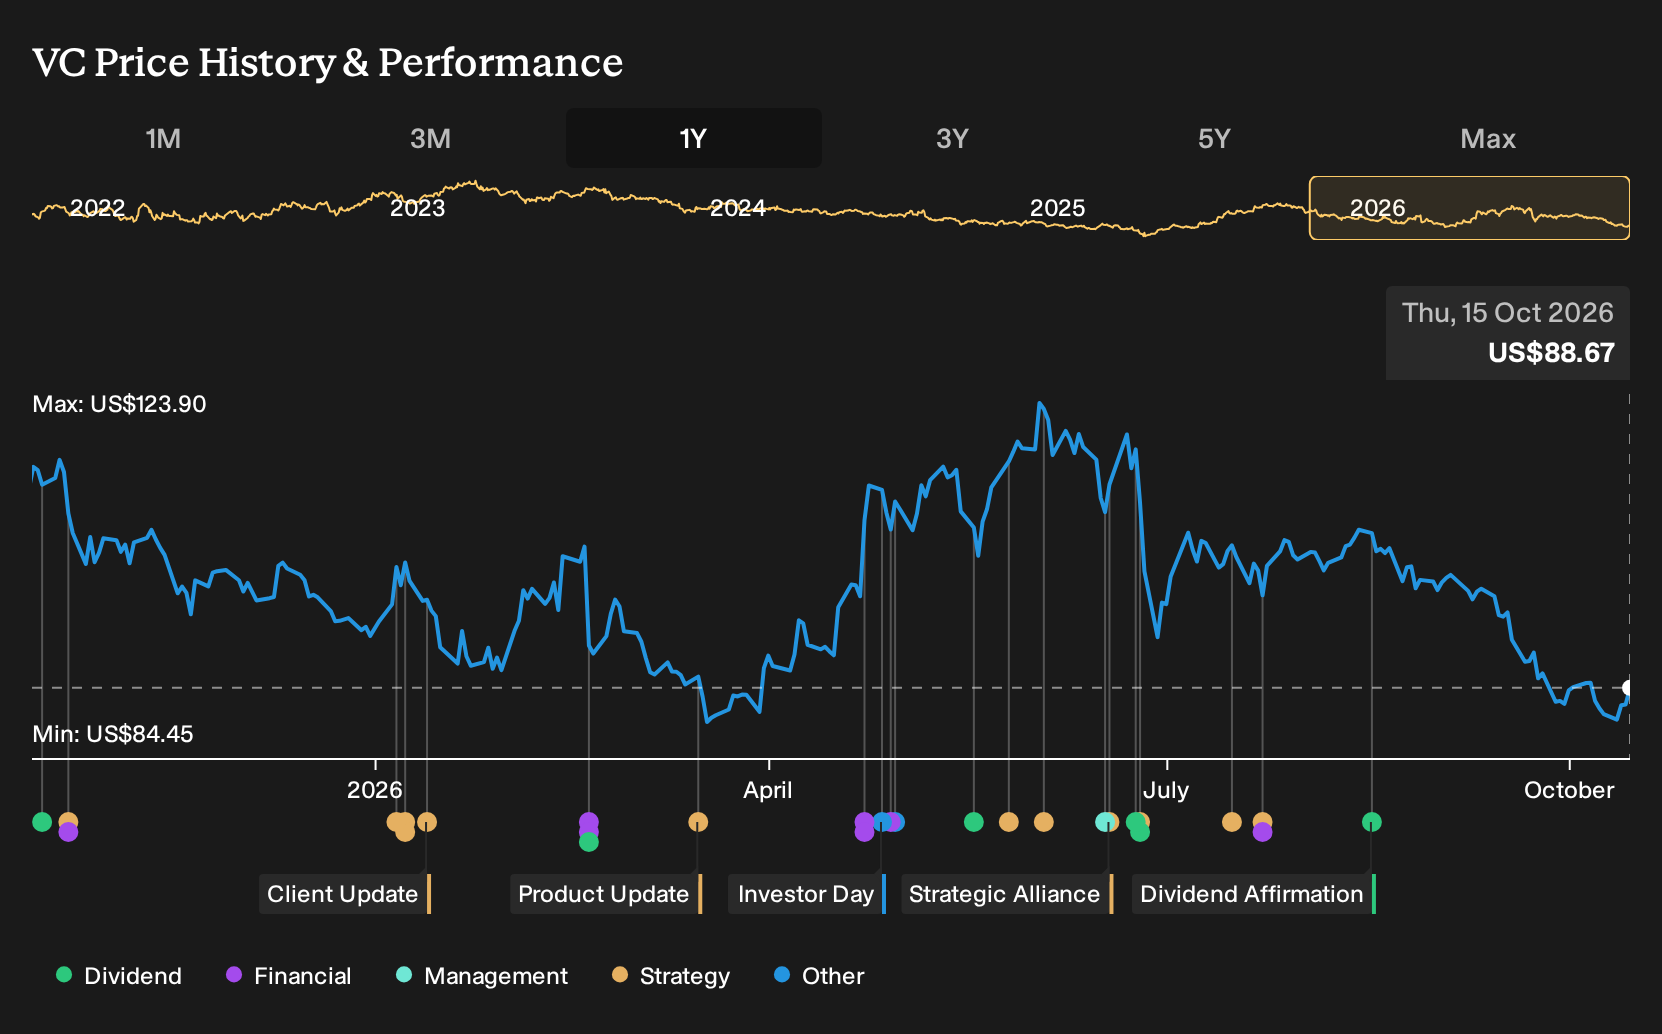
Visteon’s recent headlines have been dominated by an $800 million buyback plan, a fresh dividend and mixed quarterly results that saw revenue hold near prior levels while net margin slipped to 5.1% in Q2 2026. Holding Visteon over the past year would have meant a 22.2% loss, including dividends. If you had made that choice last October, how would you now weigh fresh AI cockpit wins and capital returns against tariff risks and OEM insourcing plans?
Visteon has already moved. See which of 33 high quality undervalued stocks still trade below our estimates.
The Two Visteon Stories Investors Had To Weigh
The shares cost US$116 at the start of the period, so every view on Visteon hinged on whether that price fit the next few years of cockpit electronics and software.
The bullish story pointed to a Fair Value of US$127, an implied upside figure based on assumptions such as 3.8% annual revenue growth and a 6.1% profit margin supported by cockpit AI and display wins.
The bearish camp argued for a Fair Value of US$82, assuming revenue growth of only 0.3% and margin pressure toward 5.3% as OEM insourcing and tariffs reduced the opportunity.
What The Evidence Did To The Visteon Argument
Visteon landing roughly US$3.0b of new AI cockpit and SmartCore business across Q1 and Q2 2026 leaned toward the bullish case that assumed wins in high performance compute and large displays. At the same time, Q2 2026 results showed revenue slipping slightly from US$969m to US$960m and net income dropping from US$71m to US$49m, with margin down to 5.1%. The evidence cut both ways.
The lesson is simple. When a thesis leans on higher profitability rather than just contract momentum, investors need to track net margin in each filing and see whether new business turns into richer earnings or just more volume.
What Visteon’s Lower Price Now Asks You To Believe
Visteon trades at US$88.67 today after a share price that declined 22.2% over the past year, while this Narrative’s Fair Value sits above the current price based on its own assumptions.
The argument centers on cockpit computing bookings, Asia-focused programs and capital returns. For the share price decline to look like an opportunity rather than a warning, a buyer must believe that booked software-defined vehicle and Asian work convert into the margins and cash generation the Narrative outlines.
"The main factor that has to go right is that Visteon converts its software defined vehicle and high growth Asian and non automotive bookings into the higher margins and free cash flow that management is targeting through 2029, despite planned memory cost headwinds and legacy program roll offs."
One Narrative disagrees with today's price. → See where this Narrative says Visteon should trade
Go Straight To The Source
Passing on this one could have spared you a loss. Where might you find the opposite surprise? Start looking for companies whose prices leave room for a better outcome than investors expect. These three trade below our estimated value.
- Company 1 - 46% below our estimate - targets gamblers moving from in-person venues toward digital wagering platforms with proprietary systems.
- Company 2 - 31% below our estimate - rides demand for specialized chips used in training complex artificial intelligence models.
- Company 3 - 33% below our estimate - runs higher cost mines extracting gold while balancing long reserves with political risk.
That is three of the list. See every one of the 25 solid balance sheet companies →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com