
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Saia (SAIA) Opens Deer Park Terminal As Network Growth Narrative Meets Valuation Debate
Saia (SAIA) just opened a new terminal in Deer Park, New York, expanding its less than truckload network deeper into Long Island and the greater New York City market.
For context, Saia shares trade at US$341.46, with a 1-year total shareholder return of 12.21%, but a 3-year total shareholder return that is down 10.36%. The 90-day share price return has fallen 21.84%, even as management continues to invest in projects like the Deer Park terminal that aim to address concerns around volumes and future earning power.
Spot opportunities beyond Saia by scanning a hand picked 33 high quality undervalued stocks featuring companies with solid cash generation and balance sheets that can better withstand pressure on volumes and returns.Bulls see Saia using Deer Park and a wider terminal buildout to reset its earnings power. Bears point to weaker volumes and returns. Which story do the current valuation markers lean toward?
Most Popular Narrative: 21% Undervalued
Saia's most followed valuation story pegs fair value at about $434 per share, compared with the recent $341.46 close. This view places significant emphasis on how the terminal buildout and cost structure interact over time.
The ongoing expansion and maturation of Saia's national terminal network, combined with densification of the 218 plus facilities added or upgraded since 2022, is still early in its ramp and is beginning to show operating ratio improvement at newer sites. This could support higher shipment volumes, revenue growth and better net margins as more terminals move from the low 90s operating ratio toward mature system levels.
See why 4 investors see Saia as 21% undervalued.
Result: Fair Value of $434 (UNDERVALUED)
Still, the story can break if fuel and wage inflation keep outpacing Saia's pricing power, or if rising claims and insurance costs erode margin progress.
Find out about the key risks to this Saia narrative.
Another View: Cash Flows Point The Other Way
The popular Saia story leans on a fair value of about $434 per share, yet the SWS DCF model paints a very different picture. On that cash flow view, Saia at $341.46 trades well above an estimated future cash flow value of $146.43, which screens as overvalued rather than cheap.
For investors, that gap raises a practical question: Do you lean more on earnings driven narratives or on a cash flow model that suggests the market might be paying up for those same expectations?
Look into how the SWS DCF model arrives at its fair value.
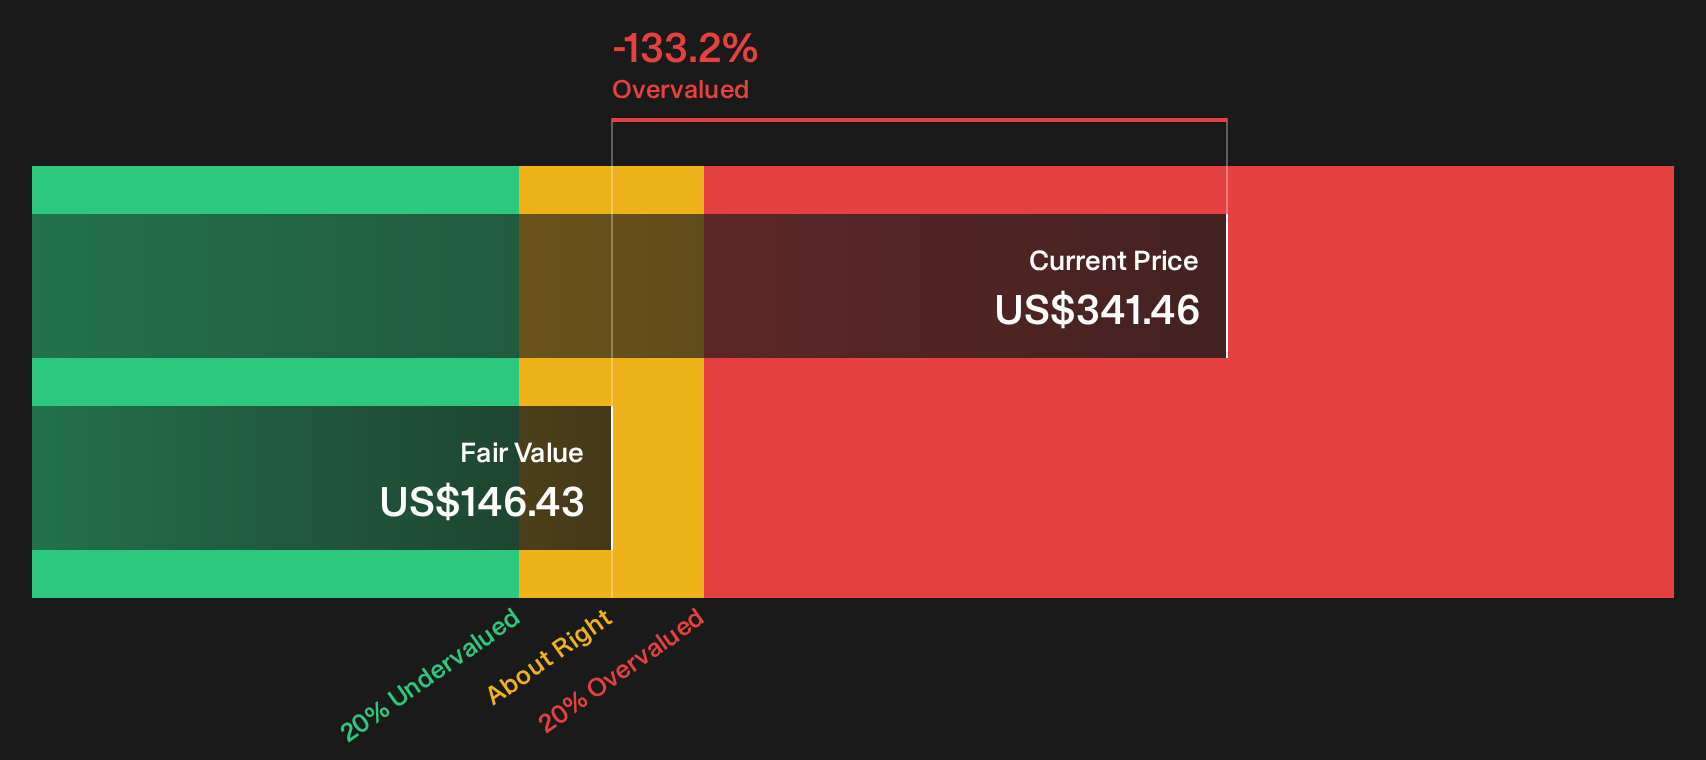
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Saia for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages in the Saia story so far. If you want to move fast and test the numbers yourself, start by weighing the 2 key rewards.
Looking for more Saia sized investment ideas?
Saia is only one story. If you want a fuller watchlist, use the same tools to uncover fresh ideas before they move out of reach.
- Target stability first by scanning a 32 resilient stocks with low risk scores that filters for resilience when markets test your patience.
- Hunt for value by reviewing a 33 high quality undervalued stocks that surfaces businesses with strong fundamentals trading below their implied worth.
- Spot future standouts early through a 20 high quality undiscovered gems focused on under the radar companies with quality financial profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com