
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Zenas BioPharma (ZBIO) INDIGO Data Puts Its Bull Case Back In Focus
Obexelimab data puts Zenas BioPharma in focus
Zenas BioPharma (ZBIO) is back on investor radar after releasing new Phase 3 INDIGO data for obexelimab in IgG4-related disease at an international medical symposium.
The fresh INDIGO data lands after a choppy stretch for Zenas BioPharma’s equity, with the share price falling about 20% over the past month and 26% year to date, even as the 1-year total shareholder return is slightly positive at roughly 5%. Recent pressure in the chart points to fading momentum in the near term. At the same time, the 2.17% 1-day share price return around the latest announcement hints that investors are reassessing both the growth potential of obexelimab and the risk profile implied by earlier declines.
Scan beyond Zenas BioPharma and compare this autoimmune-focused story with a curated group of potential peers in our 34 healthcare AI stocks to see how the wider opportunity set stacks up.
The share price slide against upbeat INDIGO data leaves Zenas BioPharma caught between a cautious chart and a stronger-looking asset story. Is this mostly sentiment whiplash, or a fair reset before valuation work starts?
Most Popular Narrative: 57% Undervalued
On the most followed view, Zenas BioPharma’s fair value of $59 is far above the last close at $25.40. This view puts heavy weight on what obexelimab could mean for the business over the next several years.
Positive Phase 3 INDIGO data with reduced flare risk and a favorable safety profile positions obexelimab for use in patients who require continuous maintenance therapy in IgG4-RD, which could broaden the treated population and lift long term revenue potential.
See why 1 investors see Zenas BioPharma as 57% undervalued.
Result: Fair Value of $59 (UNDERVALUED)
Still, rising quarterly losses and reliance on external financing leave Zenas BioPharma exposed if access to fresh capital tightens or if milestone cash arrives later than expected.
Find out about the key risks to this Zenas BioPharma narrative.
Another View: Zenas BioPharma Through a P/B Lens
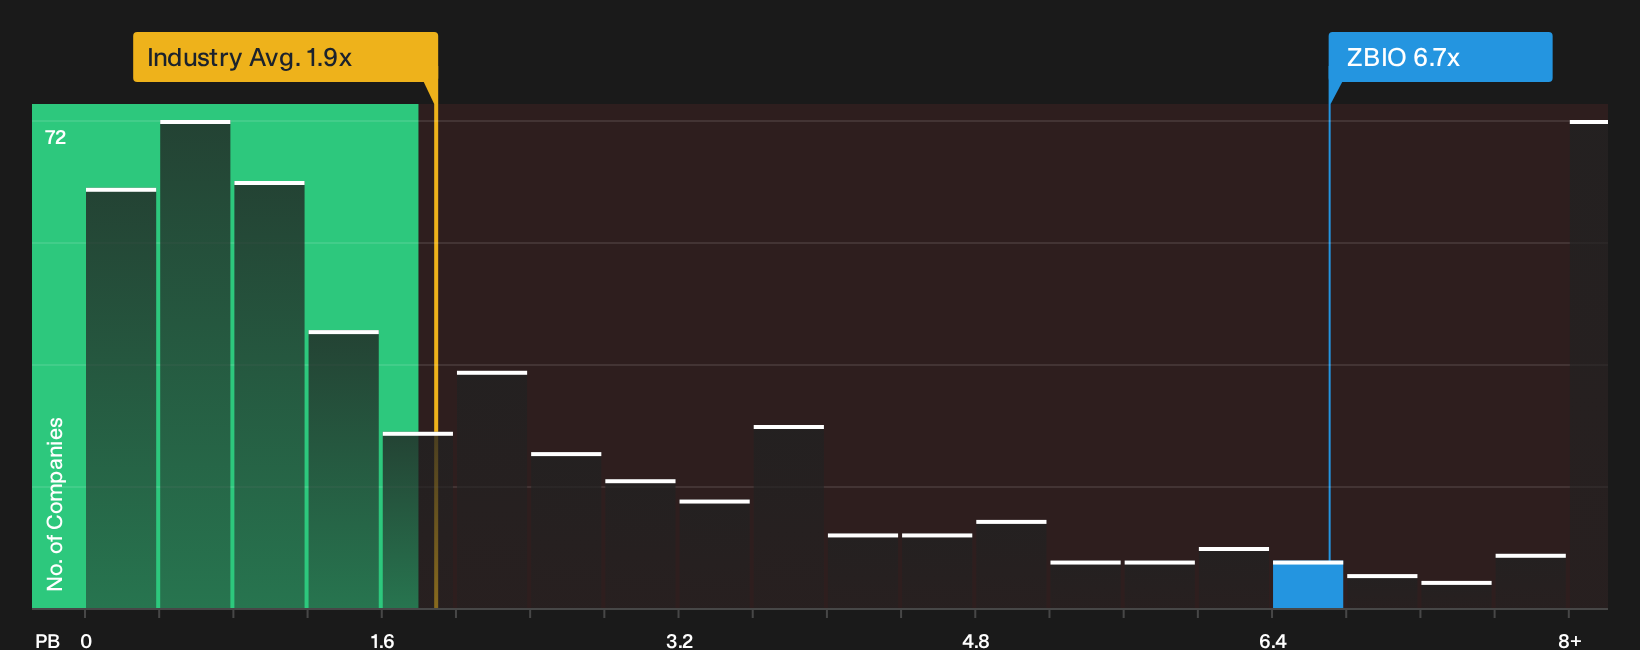
That $59 fair value narrative leans heavily on future earnings. A simpler yardstick, the current P/B of 6.7x, paints a different picture. It is rich against the US Biotechs average of 1.9x yet cheaper than peer levels at 9.1x. Is the premium justified, or is balance sheet risk being priced in early?
To see how this price tag lines up against the underlying numbers, including what the market might move toward as a fair ratio, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed feelings on Zenas BioPharma so far, with both risk flags and upside angles in play, means your own review matters more than ever. Pressure test the numbers, weigh both sides of the story, and then ground your view in the 1 key reward and 3 important warning signs.
Looking for more investment ideas beyond Zenas BioPharma?
If you stop with Zenas BioPharma, you only see one angle. Cast a wider net with fresh ideas surfaced by the Simply Wall St Screener in minutes.
- Target resilient compounding potential by focusing on businesses with robust finances and low leverage through a curated list of solid balance sheet and fundamentals (25 results) that keeps quality front and center.
- Spot potential mispricing by scanning a hand picked universe of 33 high quality undervalued stocks where strong fundamentals and appealing prices line up in one place.
- Prioritize stability and income by zeroing in on 8 dividend fortresses designed for investors who want yields backed by sturdy balance sheets and consistent cash flows.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com