
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
OEM International (OM:OEM B) Reports Higher Sales And Profit, Is It Fully Valued?
OEM International (OM:OEM B) just posted new third quarter figures, reporting sales of SEK 1,582 million and net income of SEK 201 million, alongside higher nine-month totals versus the prior year.
The latest earnings update appears to have reset expectations around OEM International, with the share price up 3.96% on the day and 8.37% over the past month. The year-to-date share price return of 33.38% and 1-year total shareholder return of 34.57% suggest momentum has been building rather than fading.
Scan how OEM International’s recent move compares with peers by running it alongside our curated list of 198 high quality undervalued stocks that also pair earnings strength with robust balance sheets.
For OEM International, that sharp post earnings rally could either echo a sturdier operating story or simply reflect investors warming up again. The next step is to see what the current valuation actually implies.
Price-to-Earnings of 38.2x: Is it justified?
OEM International just re-rated after the quarterly figures, yet the valuation already reflects a rich P/E of 38.2x at the last close of SEK183.8. That multiple sits well above several reference points in the sector, which raises the question of what kind of earnings profile the market is paying up for.
The P/E ratio compares the current share price with the earnings per share. For a distributor of industrial automation components like OEM International, investors often use this measure to judge how much they are paying for each krona of current profit, especially when earnings are already positive and forecast to expand.
Here, the market value looks stretched. The stock trades at a P/E of 38.2x while the European Trade Distributors industry average sits at 16.9x and the peer group sits around 35.1x. The estimated fair P/E based on the SWS fair ratio framework is 21.1x, which is far lower than where OEM International is currently priced and points to a level that the valuation could move toward if expectations cool.
Explore the SWS fair ratio for OEM International.
Result: Price-to-Earnings of 38.2x (OVERVALUED)
Still, if OEM International delivers weaker revenue or net income than the annual figures of SEK 5,639.4m and SEK 667.7m imply, sentiment could reverse quickly.
Find out about the key risks to this OEM International narrative.
Another view on OEM International’s value
A different lens tells a softer story. Our DCF model points to a fair value of about SEK190.04 per share compared with the current SEK183.8. That suggests OEM International trades roughly 3.3% below that estimate, which raises a simple question for you: is the higher 38.2x P/E too harsh on this cash flow view, or is the DCF being generous?
Look into how the SWS DCF model arrives at its fair value.
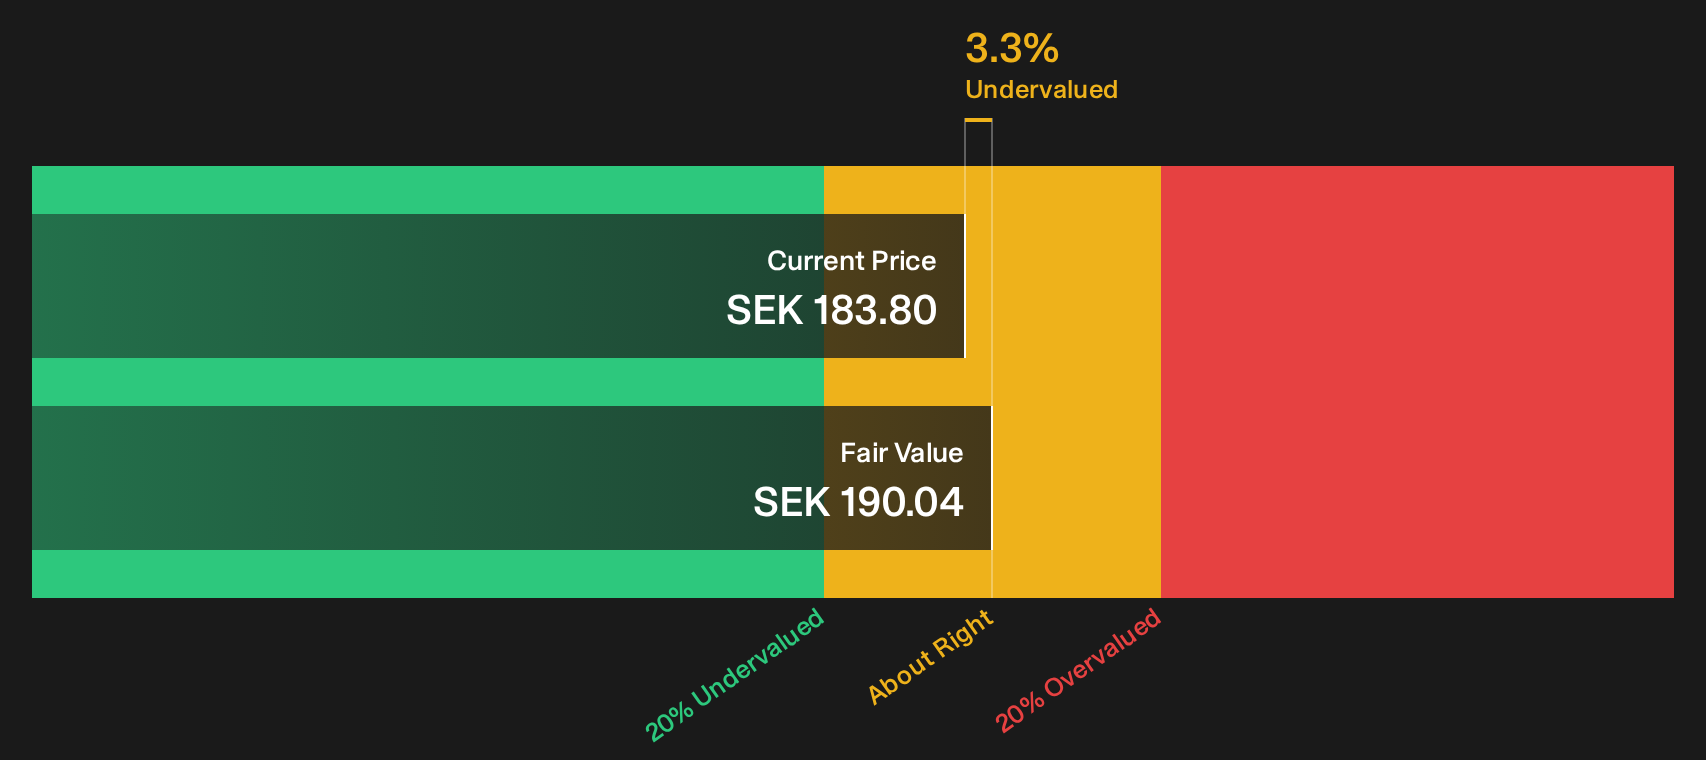
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out OEM International for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 198 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this combination of a high P/E ratio and a modest DCF difference leaves you uncertain, quickly review OEM International’s numbers against your own checklist. Then balance that perspective by considering the 3 key rewards.
Looking for more OEM International investment ideas?
If OEM International has sharpened your focus on quality, do not stop here. Broaden your watchlist now so you are not late to the next opportunity.
- Target resilient cash generators by scanning a 220 dividend fortresses that prioritize income strength alongside business durability.
- Hunt for mispriced opportunities using a 613 high quality undiscovered gems that highlights strong fundamentals before they attract wider attention.
- Protect your downside first by filtering a 225 resilient stocks with low risk scores designed to spotlight businesses with more robust risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com