
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Wise Group (WSE) Lifted Guidance, Is The Stock Already Fully Valued?
Wise Group (WSE) has drawn fresh attention after lifting its outlook for fiscal 2027 net revenue growth and keeping income before tax margin guidance near the top of its stated range.
Recent trading reflects that stronger guidance. The 1-month share price return of 3.91% and 7-day gain of 3.55% suggest building momentum from the upgraded outlook and new product launches, even though the 1-year total shareholder return is still down 9.54% and the 3-year total shareholder return is 44.85%.
Scan for other fast-growing financial platforms showing strong customer momentum with our hand-picked 33 high quality undervalued stocks, which may be comparable to Wise Group's latest outlook upgrade.
Wise Group now looks like a powerful cross border payments franchise, with refreshed guidance and new products helping sentiment. The real task is simpler: Are you paying a fair price for that strength today?
Most Popular Narrative: 29% Undervalued
Against the last close at $12.10, the most followed narrative pegs Wise Group's fair value materially higher, which puts the focus squarely on how durable its earnings drivers look over time.
Customer balances of US$39b, including US$9b held through Wise Assets, together with an interest income framework that targets sharing 80% of yield above 1% with customers, create a recurring income stream that can support net revenue while still allowing for margin discipline.
See why 3 investors see Wise Group as 29% undervalued.
Result: Fair Value of $16.94 (UNDERVALUED)
Still, Wise Group’s reliance on interest income and its plan to keep trimming transfer pricing could pressure margins if cost efficiencies or customer activity disappoint.
Find out about the key risks to this Wise Group narrative.
Another View On Wise Group’s Valuation
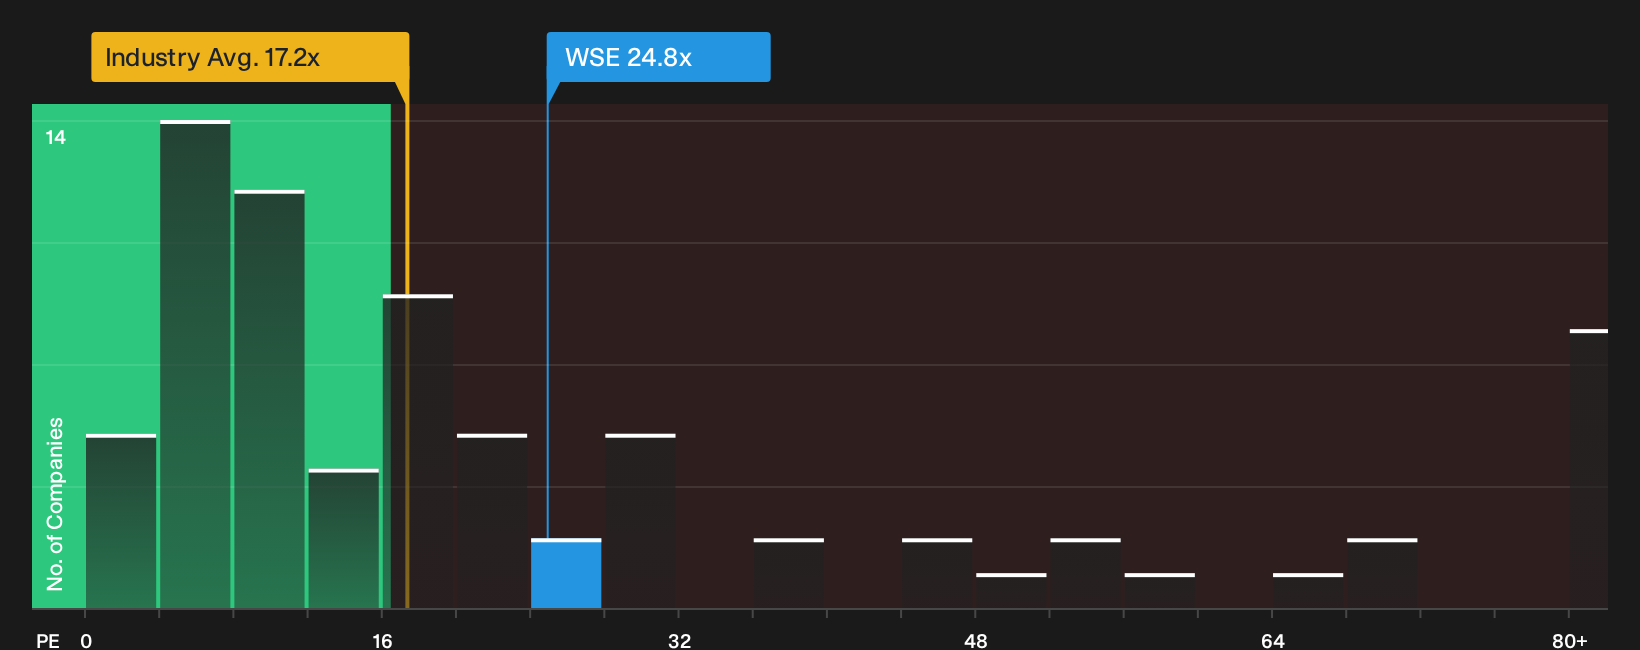
The fair value estimate of $16.94 paints Wise Group as undervalued, yet the P/E of 24.8x tells a stricter story. That figure sits well above the US Diversified Financial industry at 17x and the fair ratio of 14.9x. Paying that kind of premium raises the question of how much cushion is really left if growth or margins fall short.
To see how that premium lines up with the underlying numbers, it helps to walk through the valuation breakdown in detail, including how Wise Group compares to peers on earnings power and pricing risk, via the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Optimistic about Wise Group or still unconvinced by the mixed signals? Move quickly, review the numbers yourself, and weigh the 3 key rewards.
Looking for more investment ideas beyond Wise Group?
Do not stop with Wise Group. Broaden your opportunity set with a few targeted stock lists that can help you pressure test your portfolio and spot fresh ideas early.
- Target reliable income streams by scanning companies that aim to combine high yields with staying power using the 8 dividend fortresses.
- Pressure test your watchlist against a 32 resilient stocks with low risk scores to see which businesses pair resilience with lower risk scores.
- Hunt for potential future leaders before the crowd catches on through a curated set of 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com