
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How First Quarter Earnings At Create SD Holdings Stock Has Changed Its Investment Story
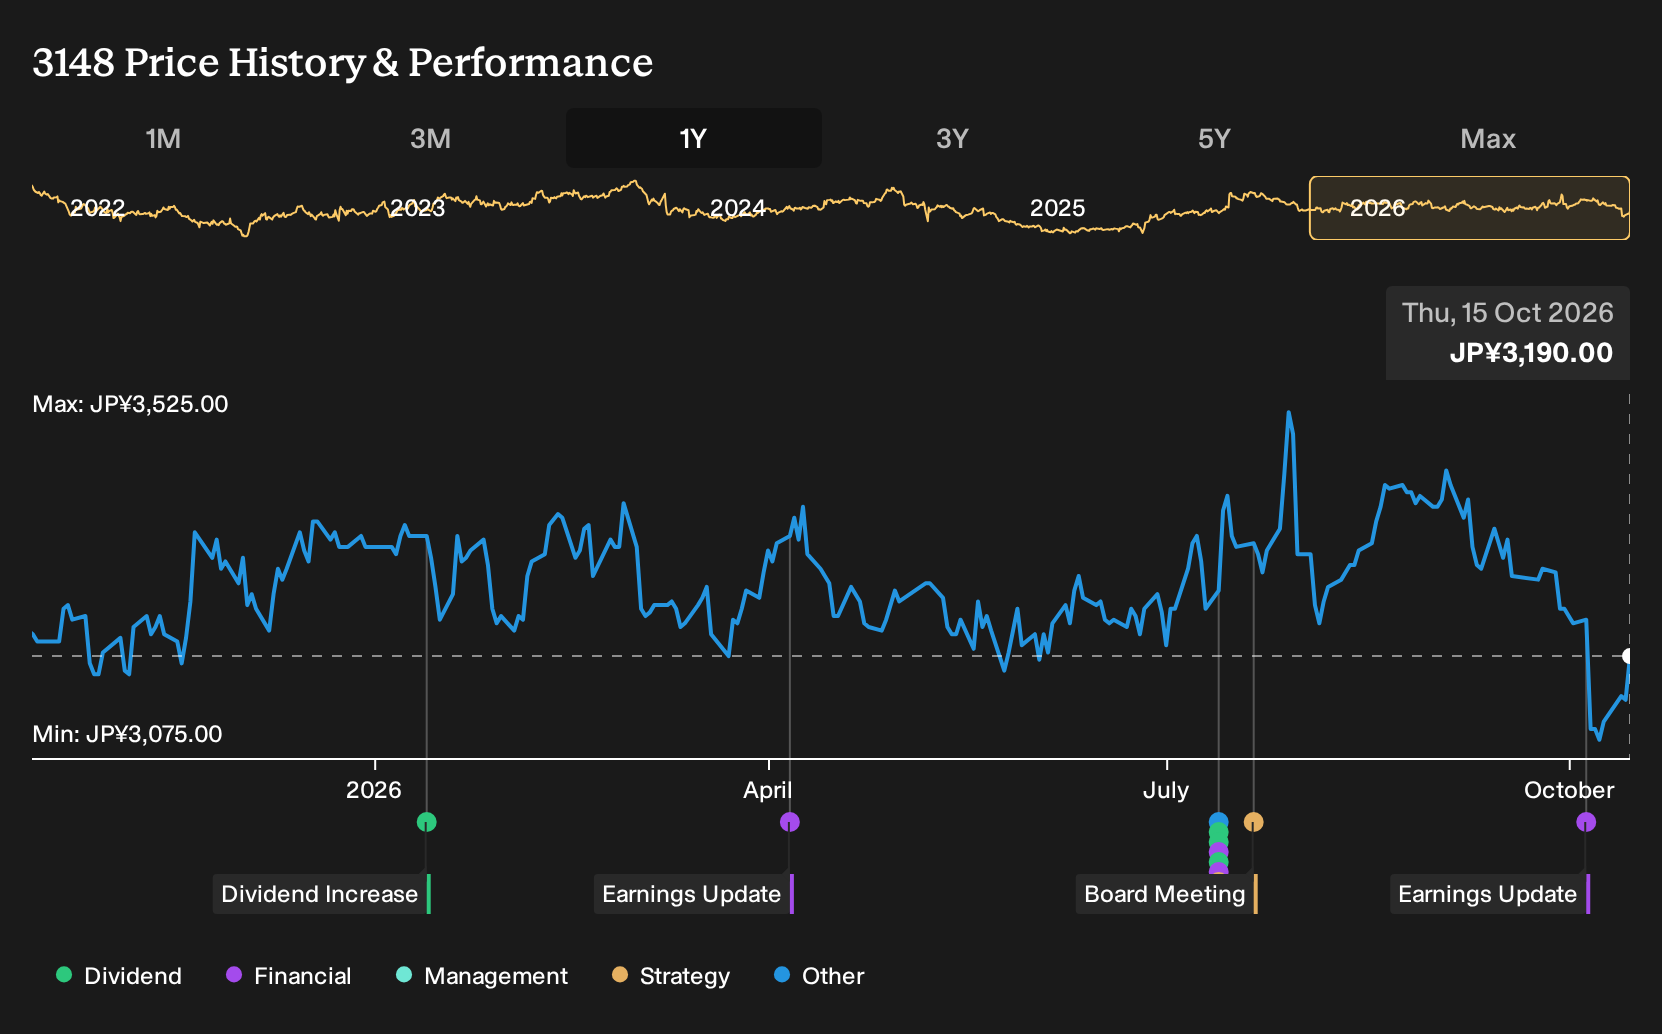
- Create SD Holdings reported first quarter results for the period ended August 31, 2026, with sales of JPY 129,540 million, net income of JPY 3,788 million, and basic earnings per share of JPY 58.64 from continuing operations.
- The quarter mixed higher sales with a softer bottom line, which highlights pressure on profitability and cost control even as demand supported top line growth.
- The focus now turns to how Create SD Holdings' investment narrative incorporates stronger sales alongside weaker net income in the latest quarter.
See how Create SD Holdings' latest quarter compares with other retailers balancing sales momentum against thinner earnings in our curated set of 15 high quality undervalued stocks.
What Is Create SD Holdings' Investment Narrative?
Create SD Holdings asks you to believe in a fairly straightforward story. A broad drugstore and prescription footprint in Japan, steady consumer demand for daily necessities and healthcare items, and an operating model that can convert that traffic into consistent earnings over time. The latest quarter fits that picture only partially. Sales moved to ¥129,540 million while net income softened to ¥3,788 million, and earnings per share from continuing operations slipped to ¥58.64. That mix reinforces the idea that execution and cost discipline matter as much as store count or ticket size.
In the short term, the key swing factors are pricing power in core categories, expense control in a still competitive retail market, and how much capital needs to go into new locations or care facilities to keep revenue moving. The slight net margin pressure mirrors earlier data that profit growth has slowed to 3.2% over the past year compared with a 5 year pace of 7.8%. A P/E of 12.3x below both the JP market and Consumer Retailing averages suggests expectations are not stretched. At the same time, the weaker first quarter earnings keep the focus on whether Create SD Holdings can defend profitability while still investing in growth projects.
Even so, there is a less comfortable angle once you factor in ...
There's only one way to know the right time to buy, sell or hold Create SD Holdings. Head to Simply Wall St's company report for the latest analysis of Create SD Holdings's Fair Value.
Form Your Own Verdict
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so consider your own judgment carefully.
- A great starting point for your Create SD Holdings research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Create SD Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate Create SD Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond Create SD Holdings?
If the Create SD Holdings update has you rethinking where new capital should go, it can help to scan a broader set of opportunities using structured filters rather than gut feel alone.
- If resilience matters most to you, start with a basket of companies that screen as relatively robust on risk metrics through our 21 resilient stocks with low risk scores.
- For investors who care about balance sheet strength and fundamentals, there is a focused list of solid balance sheet and fundamentals (21 results) that keeps financial quality front and center.
- If you are hunting for under-the-radar opportunities, broaden your watchlist with a curated 72 high quality undiscovered gems that surfaces lesser known businesses with solid underpinnings.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com