
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Simmons First National (SFNC) Heads Into Q3 Earnings With Its Undervalued Narrative In Focus
Simmons First National (SFNC) heads into its Q3 earnings release this Thursday after market hours, with attention squarely on whether revenue momentum can match expectations despite forecasts for slower year-on-year growth.
Recent trading has been choppy for Simmons First National, with the share price down 4.05% over the past 30 days and 3.01% over 90 days. However, the year-to-date share price return of 18.28% and 1-year total shareholder return of 28.73% point to stronger momentum over a longer stretch, which hints that investors have gradually grown more comfortable with the bank’s risk and earnings profile ahead of the Q3 release.
Compare Simmons First National with a curated group of regional banks that pair earnings sensitivity with balance sheet support through our list of solid balance sheet and fundamentals (25 results) before this Q3 season moves on.
Simmons First National has already handed investors a strong run this year, yet the shares still trade below analyst targets and an estimated intrinsic value. How much of the upside is already in the rearview mirror, and how much might be left?
Most Popular Narrative: 14% Undervalued
Simmons First National last closed at $22.26, while the most followed narrative anchors on a fair value of $25.93. This frames the current debate around how durable the earnings rebuild can be.
The ongoing efficiency program that has already cut corporate and branch square footage by 8.5% toward a 15% target, together with vendor savings and planned closure of 26 branches, is set to hold noninterest expense growth below earlier guidance and improve the efficiency ratio.
See why 6 investors see Simmons First National as 14% undervalued.
Result: Fair Value of $25.93 (UNDERVALUED)
Still, this Simmons First National story can be knocked off course if fierce deposit competition keeps funding costs elevated or if slower loan growth limits the benefit of repricing.
Find out about the key risks to this Simmons First National narrative.
Another View: Simmons First National Through The P/B Lens
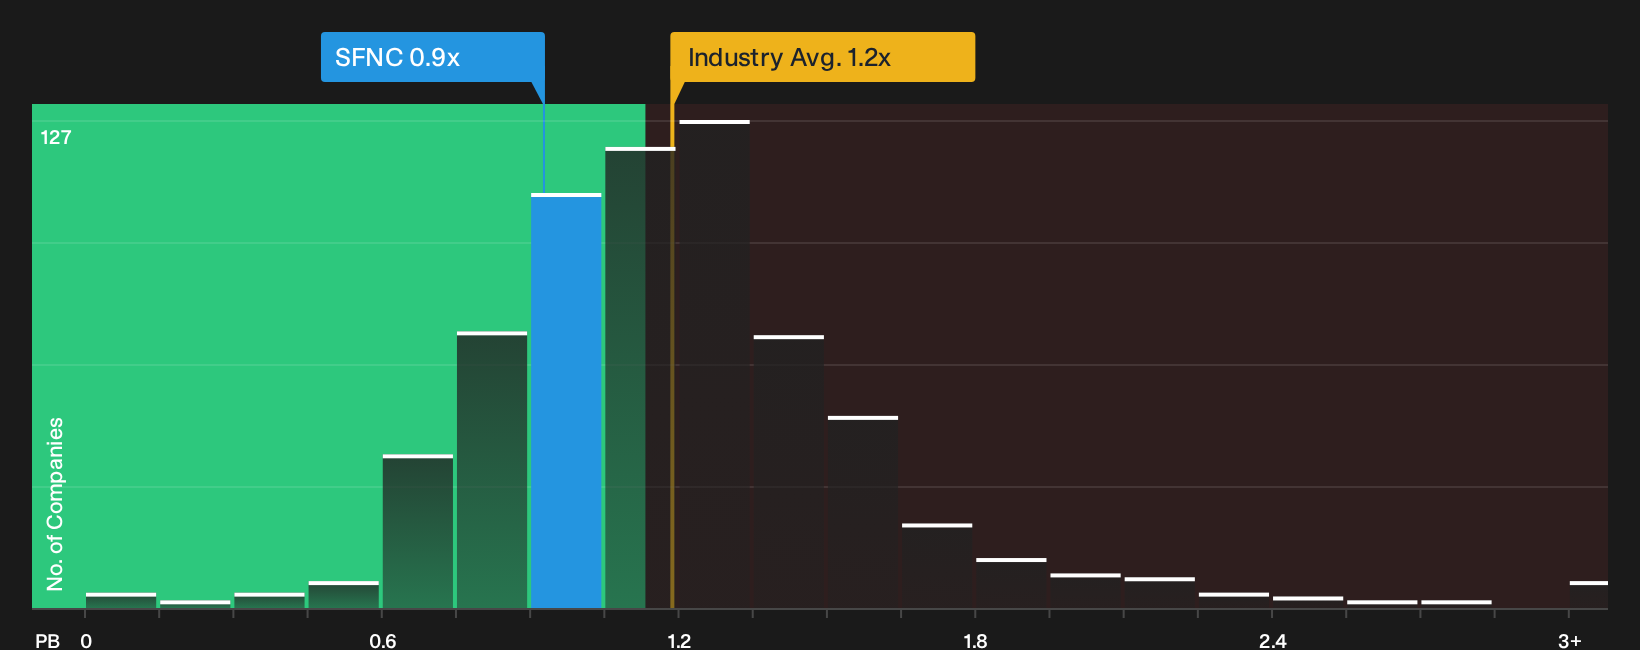
The first narrative leans on a fair value of $25.93, yet the market is telling a different story when you focus on price against book value. Simmons First National trades on a P/B of 0.9x, which matches its direct peer average of 0.9x but sits below the wider US Banks group at 1.2x.
That gap suggests the stock carries less of a valuation premium than the broader sector, even though the fair value model flags Simmons First National as trading 39.4% below an implied intrinsic worth and below an estimated future cash flow value of $36.72. The question is whether you think that discount is compensation for real risks or a window that could close if the story improves.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Simmons First National story so far. Act while the Q3 conversation is fresh and pressure test the upside and downside using the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Simmons First National?
If you only stop at Simmons First National, you risk missing other setups that might fit your goals even better. Broaden your watchlist before the next move.
- Target reliable income streams by scanning for potential high-yield opportunities through the 8 dividend fortresses that could complement a bank-focused portfolio.
- Hunt for pricing gaps where quality fundamentals meet attractive entry points using the 33 high quality undervalued stocks and compare those valuations with Simmons First National.
- Prioritise capital protection by filtering for steadier profiles with the 32 resilient stocks with low risk scores so short term swings do not derail your longer term plan.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com