
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors May Respond To MP Materials Stock Rare Earth Expansion
- MP Materials is ramping up its Mountain Pass rare earth mine into a fuller processing and magnet manufacturing operation, supported by significant capital commitments from Apple and the US Department of Defense to expand downstream capacity in the United States.
- The shift from selling mainly raw materials toward producing finished magnets gives MP Materials more control over its cost structure and contracts, tying its fortunes more directly to long-term demand from electric vehicles, wind turbines, and defense hardware.
- We will now look at how MP Materials' expanded rare earth processing and magnet capacity could influence the existing investment narrative.
Scan other rare earth and critical materials opportunities on our hand picked list of 32 best rare earth metal stocks, which sit beside MP Materials in the supply chain for EVs, wind turbines, and defense hardware.
MP Materials Investment Narrative Recap
To own MP Materials, you need to believe the rare earth mining, processing, and magnet operations at Mountain Pass can scale efficiently, and that customer demand from EVs, wind, and defense translates into steady orders over time. The near term story still hinges on how quickly the expanded processing and magnet capacity can be utilized. The latest expansion news does not change that core thesis; it simply reinforces where management is putting capital and attention.
The biggest short term swing factor is execution on these downstream facilities. Any hiccups at the 10X magnetics plant or in heavy rare earth separation could pressure margins and keep the business loss making for longer. Customer concentration and contract limits remain key risks if order timing, policy, or pricing shift while MP Materials is still absorbing heavy upfront investment.
The most relevant recent announcement is the long term, government backed Department of Defense offtake agreement, which includes a price floor and minimum EBITDA on magnet output. That contract ties directly into the expansion of MP Materials' processing and magnet capabilities. It is essentially the commercial backbone for the scale up investors are watching.
Those DoD terms help reduce revenue volatility and support planning for the 10X plant and recycling facilities, though they also cap MP Materials' upside to global price swings and restrict certain end markets, including sales to China. For you as a shareholder, the contract sharpens the focus on one thing: Can management deliver reliable volumes, on time and on budget, to the handful of large customers that now matter most to this story?
MP Materials Analyst Assumptions and Valuation Check
Analyst models for MP Materials have a clear through line. They tie the expanded processing and magnet footprint directly to higher revenue, a swing back to profitability, and a richer valuation multiple if everything goes to plan.
On the top line, the consensus view assumes revenue grows by 38.9% a year over the next three years. That is a steep trajectory for any miner that is also building out manufacturing and recycling capacity. It tells you these forecasts lean heavily on the idea that magnet volumes, government backed contracts, and large tech customers keep the new facilities busy.
Earnings expectations are even more aggressive. Analysts pencil in a move from a loss of US$60.6 million today to earnings of US$297.1 million by 2029. That is a swing of about US$358 million, with the average forecast sitting roughly in the middle of a wide band that runs from US$167 million on the low side to US$537.4 million at the top end. The range underlines how much uncertainty still surrounds execution at Mountain Pass and the timing of downstream ramp up.
Underlying margins have to reshape materially for those numbers to hold. Forecasts point to profit margins shifting from a loss of 14.6% today to a positive 26.6% in three years. For you, that means the MP Materials story is not just about selling more product. It is about turning a capital heavy buildout into better unit economics across mining, separation, and magnets.
Those earnings forecasts then feed straight into valuation. To line up with the analyst consensus targets, MP Materials would need to deliver 2029 revenue of about US$1.1b and earnings of US$297.1 million. On those figures, the stock would be trading on a P/E of 57.6x, which sits well above the current 19.8x P/E quoted for the wider US metals and mining industry.
That gap matters. A 57.6x multiple effectively assumes investors are willing to pay a premium for the rare earth and magnet exposure, the government and Apple contracts, and the shift into value added products. It also assumes the current reported loss converts into the forecast profit pool without major delays or cost blowouts that could sap confidence in those out year numbers.
Analysts also bake in a slow drift higher in the share count, with projected dilution of about 0.49% per year over the next three years. The effect looks modest on paper, although it still means future per share metrics rely not just on higher absolute earnings but also on management holding the line on new issuance beyond what is already forecast.
MP Materials' narrative projects about US$1.1b in revenue and US$297.1 million in earnings by 2029. This assumes 38.9% yearly revenue growth and an earnings swing of roughly US$358 million from a current loss of US$60.6 million.
Uncover why MP Materials' fair value indicates a 75% potential upside to its current price that may not last much longer.
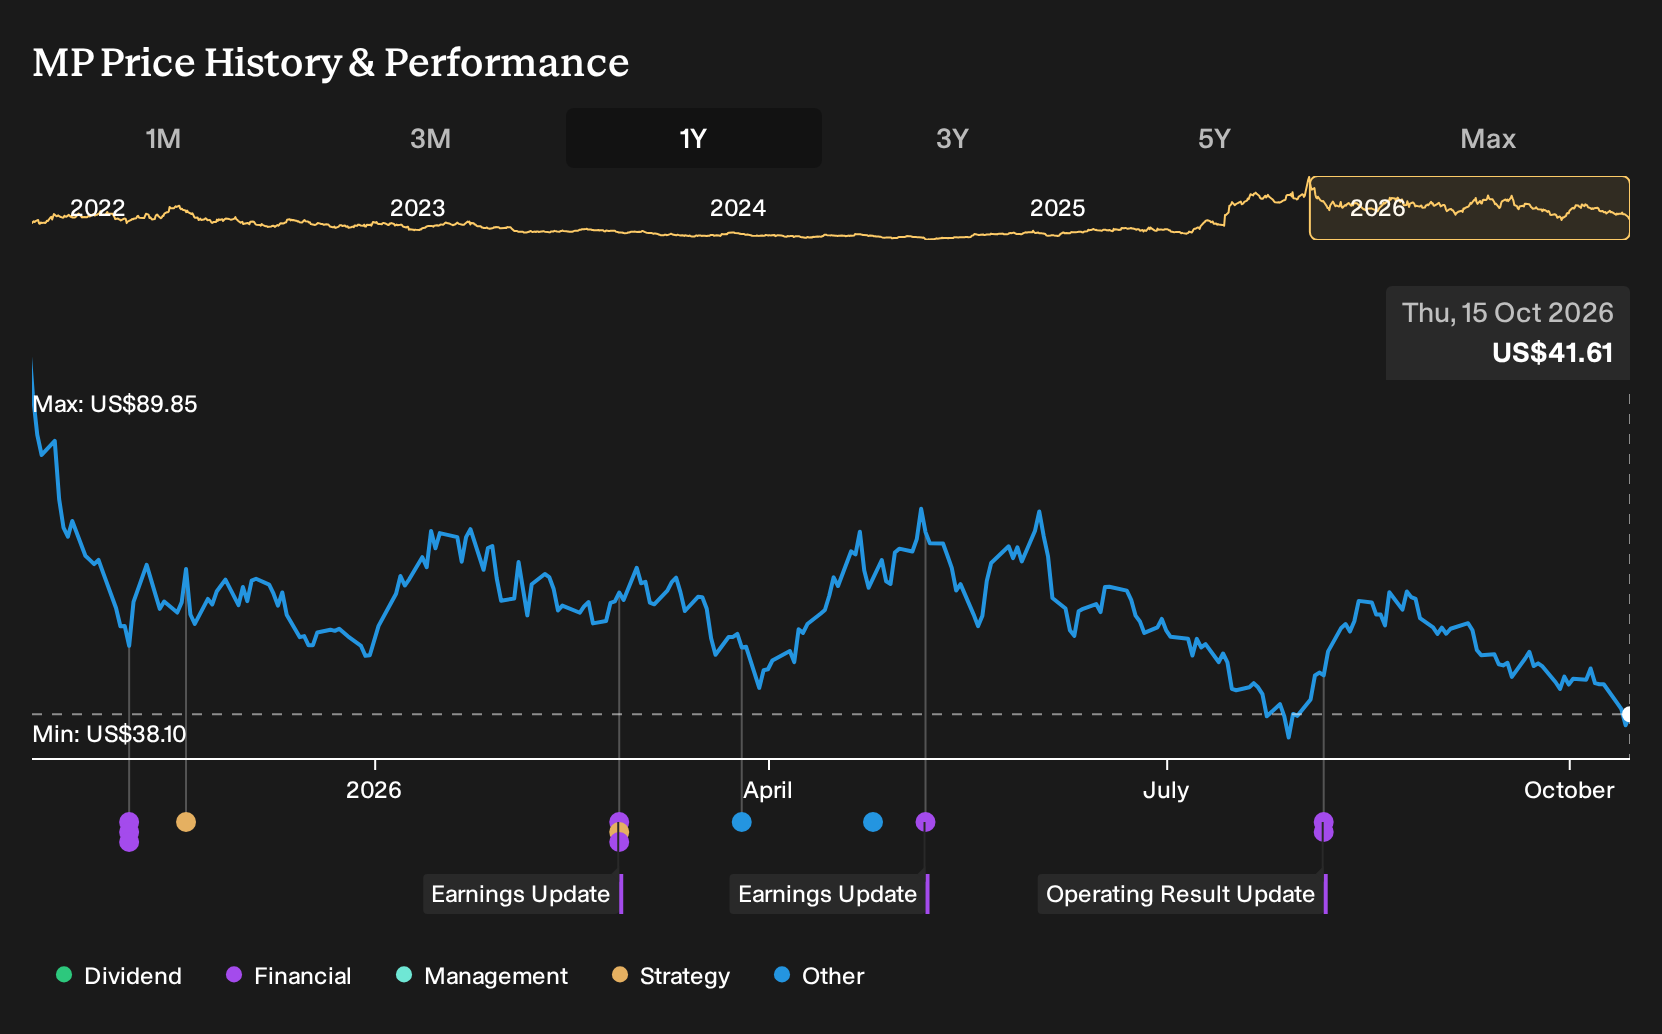
Exploring Other Perspectives
One alternate angle on MP Materials centers on the bullish view that magnet capacity is already effectively pre-sold. The most optimistic analysts were expecting about US$1.5b of revenue and US$489.8 million of earnings by 2029, well above consensus. Those estimates came before this expansion news, so opinions and forecasts may shift as details become clearer.
Explore 9 other MP Materials fair value estimates, including one that suggests potential upside of up to 350% from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your MP Materials research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for MP Materials. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate MP Materials' overall financial health at a glance.
Looking For More Investment Ideas Beyond MP Materials?
If MP Materials has sharpened your focus on where capital could work hardest, it can be useful to line it up against other opportunities that fit very different checklists on quality, value, and risk.
- If you want to aim at potential upside while staying mindful of fundamentals, start with a curated batch of 20 high quality undiscovered gems that many investors may not be watching yet.
- For those who care most about resilience and capital preservation, focus on companies screened as 32 resilient stocks with low risk scores to see which businesses score well on stability metrics.
- If balance sheet strength is your first filter, compare MP Materials with our list of solid balance sheet and fundamentals (25 results) and see which stocks match your tolerance for leverage and cash flow support.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com