
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
American Express (AXP) Moved Higher, What Is Driving Attention Now?
American Express (AXP) is back in the regulatory spotlight after a Federal Reserve enforcement action over anti money laundering deficiencies, just as it rolls out its AI driven Intent Intelligence Framework.
Recent news has arrived in a mixed backdrop for American Express. The share price is around $313.87 after a 1-day share price return of 2.25% and a 7-day share price return of 1.87%. However, the 30-day and 90-day share price returns declined 3.25% and 11.67% as investors weigh the enforcement action against the rollout of the AI driven Intent Intelligence Framework and other product updates.
Scan how American Express fits alongside other payment and AI beneficiaries by reviewing a curated set of 33 high quality undervalued stocks that combine quality fundamentals with discounted prices.
American Express now trades around $313.87 while models and analyst targets point higher, leaving a visible gap. Does fair value lean closer to recent price action, or to those optimistic estimates?
Most Popular Narrative: 29% Undervalued
According to the most followed narrative on American Express, the current $313.87 share price sits well below an estimated fair value of $444.11, which puts the enforcement risk and business strength on a direct collision course in the valuation story.
American Express has spent 176 years proving that trust is not a sentimental accessory added after the financial analysis. Trust is the productive asset. It is what allows the company to convert a customer's reputation into merchant fees, interest income, annual fees, and enormous purchasing volume.
See why 7 investors see American Express as 29% undervalued.
Result: Fair Value of $444.11 (UNDERVALUED)
Still, the pending anti money laundering enforcement and American Express moving into tougher Category II oversight could both pressure returns and challenge the 29% undervalued thesis.
Find out about the key risks to this American Express narrative.
Another View: What P/E Says About American Express
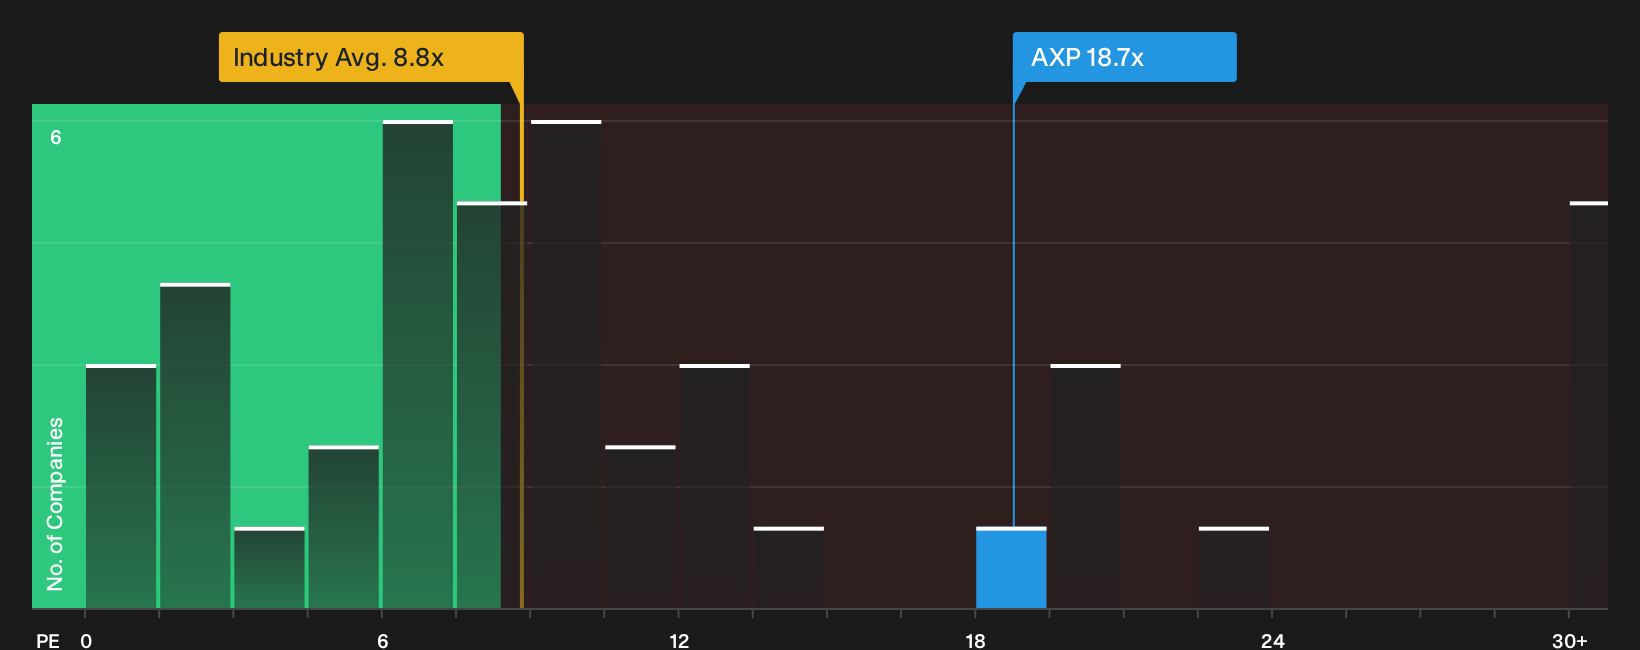
DCF work suggests American Express is trading below an estimated fair value, yet the P/E picture sounds more cautious. The stock changes hands at 18.7x earnings, above the US Consumer Finance industry on 8.8x and above its own fair ratio of 17.4x. That premium can signal quality, or it can mean less margin for error if the AML outcome tightens the story. Which signal do you trust more right now?
To see how strongly the current valuation leans on earnings multiples, and how that could shift if sentiment changes, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals around American Express will always pull opinions in different directions, so move fast, stress test the numbers yourself, and weigh both sides of the story by reviewing the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond American Express?
If American Express has sharpened your focus, do not stop here. Broaden your opportunity set with a few targeted stock ideas built from the Simply Wall St screener.
- Spot potential bargains early by scanning a curated pool of quality companies trading at marked-down prices through the 33 high quality undervalued stocks.
- Prioritize resilience in choppy markets by filtering for companies with stronger finances using the list of solid balance sheet and fundamentals (25 results).
- Hunt for lesser known opportunities with robust fundamentals by reviewing the 20 high quality undiscovered gems before others catch on.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com