
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
PACS Group (PACS) Expands In Florida As Undervalued Narrative Faces A Fresh Test
PACS Group (PACS) just took over 32 skilled nursing facilities in Florida from a prior operator, expanding its footprint as those locations move under its existing master lease with Omega Healthcare Investors.
The transition news landed alongside strong momentum in PACS Group’s shares, with the stock closing at US$47.75 and posting a 1-month share price return of 13.45% and a year-to-date share price gain of 20.86%. The 1-year total shareholder return of 283.53% points to powerful longer term sentiment already in play.
Scan PACS Group’s peers riding similar facility expansion themes by checking out list of solid balance sheet and fundamentals (25 results), which could also benefit from disciplined growth and robust financial footing.
PACS Group now trades well below the average analyst price target, yet above some intrinsic value estimates. After this Florida expansion, where does a reasonable fair value range really fall for the shares today?
Most Popular Narrative: 20% Undervalued
The most followed narrative currently places PACS Group's fair value at about $59.75, comfortably above the last close at $47.75. This frames the Florida facility handover as one more test of whether the market is underpricing execution.
Rising demand for post-acute and long-term care from an aging U.S. population, combined with PACS Group's expanding footprint of over 35,000 beds, creates room for continued top line growth as occupancy and patient volumes increase, supporting higher revenue and earnings.
See why 12 investors see PACS Group as 20% undervalued.
Result: Fair Value of $59.75 (UNDERVALUED)
Still, PACS Group faces real pressure if newly acquired facilities take longer to improve or if reimbursement frameworks in key states become less supportive.
Find out about the key risks to this PACS Group narrative.
Another View: PACS Group Through The P/E Lens
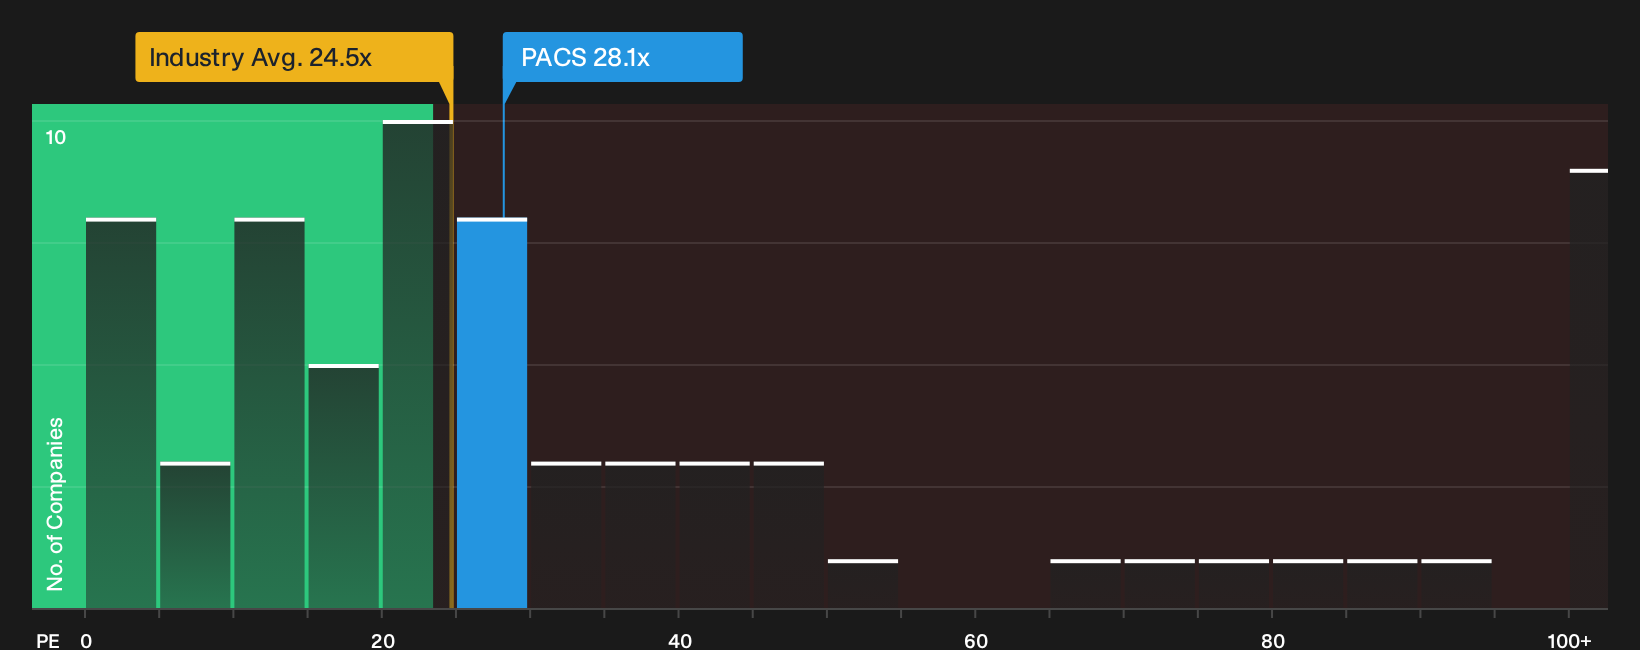
Analysts framing PACS Group as about 20% undervalued on fair value estimates run into a very different picture when looking at the current P/E. The shares trade on 28.1x earnings, higher than both the US Healthcare industry on 24.5x and peer average on 20.2x, while the fair ratio sits at a much richer 40.5x.
That spread suggests the stock screens expensive against today’s sector and peer benchmarks, yet comparatively cheap if the market ever prices it closer to the fair ratio. Which reference point do you trust more when you think about risk and reward over the next few years?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Feeling torn between PACS Group’s upbeat pricing narrative and the pockets of concern around its newest facilities and reimbursement backdrop? Act quickly on that tension by digging into both sides of the story through 3 key rewards and 1 important warning sign.
Looking for more PACS Group style investment ideas?
Do not stop with PACS Group. Broaden your watchlist with targeted stock ideas that match your risk appetite and income goals using the Simply Wall Street Screener.
- Target resilience by scanning companies with strong balance sheets and steady fundamentals through the list of solid balance sheet and fundamentals (25 results).
- Hunt for quality at a reasonable price by reviewing the 33 high quality undervalued stocks that meet strict cash flow and balance sheet tests.
- Build a cash-focused portfolio by checking the 8 dividend fortresses that combine higher yields with an emphasis on stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com