
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
World Bank Funding Could Lift Core Lithium Stock And Emerging EV Materials Plays
World Bank plans to pour up to $19b into critical minerals between 2026 and 2030, and that kind of capital can quickly reshape which battery and EV materials producers thrive or fall behind. Investors who spot which emerging market players are most exposed to this policy shift could get an early read on where money and attention might cluster next. This article walks through 3 stocks from the screener that appear well placed and explains how this news may matter for your portfolio decisions.
The stocks covered below are just a small sample from this theme, and the full screen surfaced 33 more emerging market producers with equally compelling battery and EV materials stories that are not discussed here. To go straight to the source and identify, compare, and analyze potential high conviction ideas, head into the Emerging-Market Battery & EV Materials Producers screener.
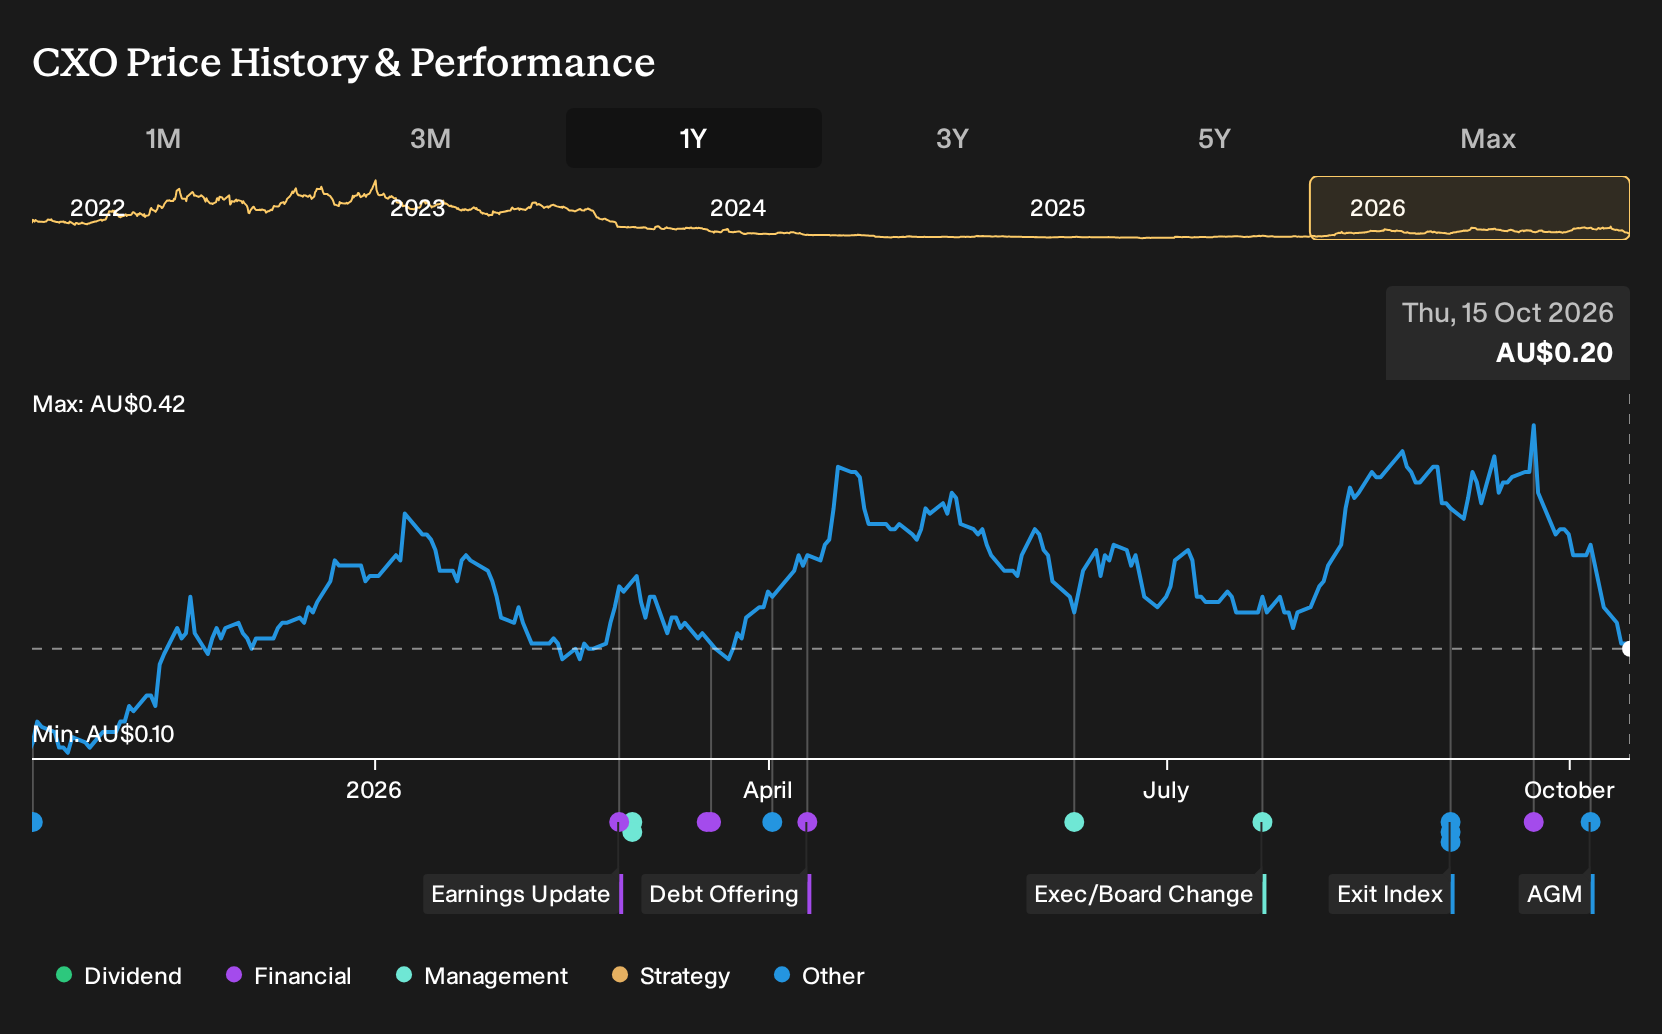
Core Lithium (ASX:CXO)
Overview: Core Lithium is an Australian junior miner focused on developing the Finniss hard rock lithium project that feeds directly into EV battery material supply.
Operations: Core Lithium generated about A$17.8 million in revenue from the Finniss Lithium Project in Australia, reflecting its single asset, single country focus.
Market Cap: A$664 million
Core Lithium sits squarely in the EV materials theme, with Finniss offering direct exposure to lithium supply at a size where new critical-mineral funding can still move the needle.
"The restart plan depends heavily on Grants open pit generating early cash flow before BP33 is producing. Any disruption to mining rates, wet season access or ore quality could leave the plant underutilised and put pressure on revenue and liquidity."
What happens to Core Lithium’s appeal within this theme hinges on how one unseen pressure ultimately feeds through to cash generation and margins.
That pressure point is exactly where the story could flip for Core Lithium, and the full narrative for Core Lithium lays out how execution risk could be masking future upside.
Elevra Lithium (ASX:ELV)
Overview: Elevra Lithium is an Australian miner developing lithium focused projects in Canada and Australia that supply EV battery materials.
Operations: Elevra Lithium generated about US$201.7 million from its North American Lithium project, selling primarily into China and the United States.
Market Cap: A$753 million
Elevra Lithium matters to this screener theme because North American Lithium already feeds into the EV supply chain, and management is trying to turn an early producing asset into a larger, lower cost source of battery raw materials.
"North American Lithium is moving through a staged expansion plan designed to add production capacity earlier through debottlenecking."
What happens to Elevra Lithium’s appeal here hinges on whether one underappreciated shift in its cost base actually lands as planned.
If that cost shift is the real hinge for Elevra Lithium, the full narrative for Elevra Lithium shows whether expansion risk is masking an accelerating opportunity.

Yunnan Jinxun Resources (SEHK:3636)
Overview: Yunnan Jinxun Resources processes and trades copper and cobalt across China, the DRC, Zambia, and Peru, linking emerging-market metals supply to battery and EV material demand.
Operations: Yunnan Jinxun Resources records about CN¥595 million from Chinese Mainland activities, with smaller reported contributions from Zambia and Peru plus segment adjustments.
Market Cap: HK$2.4 billion
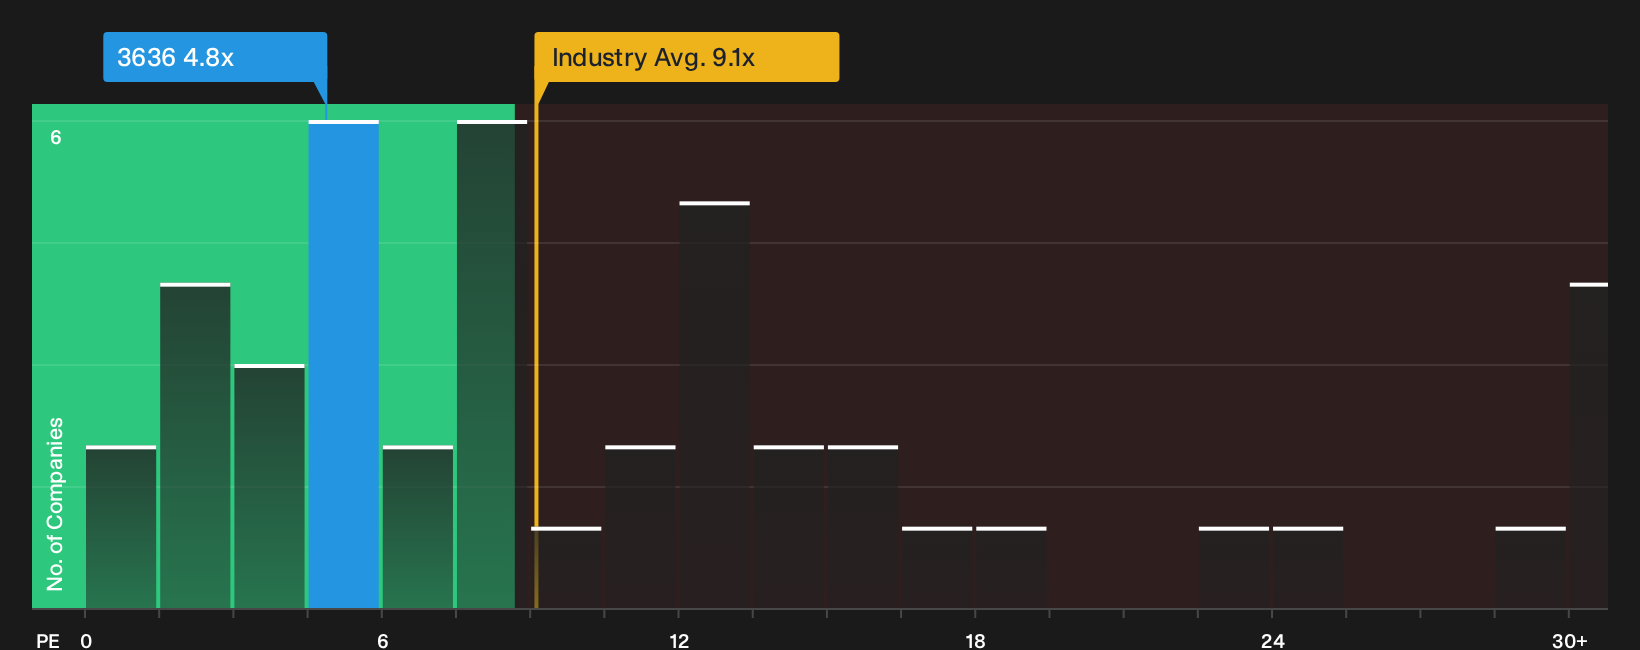
Yunnan Jinxun Resources offers focused exposure to copper and cobalt processing in countries that are important for battery supply chains. The stock trades on a 4.8x P/E, with recent earnings supporting a reported 20.5% ROE. This mix of reported profitability, valuation, and exposure to critical minerals funding supported by the World Bank may be particularly noteworthy if the recent shift in earnings quality proves sustainable.
If that earnings quality holds, go straight to the 4 key rewards and 2 important warning signs (1 is major!) to see where Yunnan Jinxun Resources’ current numbers might be masking the real swing factor.
Seeking Alternatives Before The Crowd
Fresh stock ideas move fast. Momentum builds, prices move, and clean entries get caught or drop away while you watch. Scan these curated lists while it matters and act now.
- Spot potential turnaround stories early by tracking cash rich underdogs using the list of solid balance sheet and fundamentals (12 results). Get a feel for which businesses have room to absorb shocks.
- Analyze ongoing demand for precious metals by reviewing the 35 elite gold producer stocks before interest increases more widely. Review the fundamentals of producers while they remain less widely followed for now.
- Monitor AI infrastructure developments by scanning the 94 AI infrastructure stocks and see which builders already show momentum in the numbers. Consider your timing if you want a cleaner entry.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com