
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Rocket Companies (RKT) Undervalued Following The Drop In Treasury Yields?
A sharp drop in the 10 year Treasury yield has pulled fresh attention to Rocket Companies (RKT), as lower benchmark rates ease funding costs for mortgage originators and may lift demand for home loans.
Recent rate swings have left Rocket Companies’ 1 day share price return up 5.13% to US$11.07. However, the 30 day share price return is down 16.07% and the year to date share price return is down 44.32%, while the 3 year total shareholder return of 57.44% hints that sentiment has cooled after a strong earlier run.
Scan other mortgage exposed and rate sensitive stocks that could be next to react by reviewing our hand picked list of 32 high quality undervalued stocks.
Rocket Companies has rebounded following the recent rate move, yet the stock remains well below its level at the start of the year. Does that create a more attractive entry point now, or is it better to remain patient until the valuation appears more straightforward?
Most Popular Narrative: 36% Undervalued
Against the last close of $11.07, the most followed valuation narrative puts Rocket Companies closer to $17.27. This frames the recent pullback in a very different light for anyone focused on long term cash generation rather than just near term rate moves.
The move to a revenue mix where more than 70% comes from servicing, purchase, home equity, personal loans, Redfin and Rocket Money subscriptions shifts Rocket Companies further away from pure rate driven refinance exposure and can support a steadier base for revenue and earnings.
The build out of AI tools that cut prospecting time, raise conversion and support roughly US$300b of fixed origination capacity with fewer production staff gives Rocket Companies room to add volume without matching growth in expenses, which can support net margins.
See why 35 investors see Rocket Companies as 36% undervalued.
Result: Fair Value of $17.27 (UNDERVALUED)
Still, the bullish Rocket Companies story can be knocked off course if mortgage rates stay elevated and integration of Redfin and Mr. Cooper delivers weaker cross sell than expected.
Find out about the key risks to this Rocket Companies narrative.
Another View: Rocket Companies On Earnings Multiples
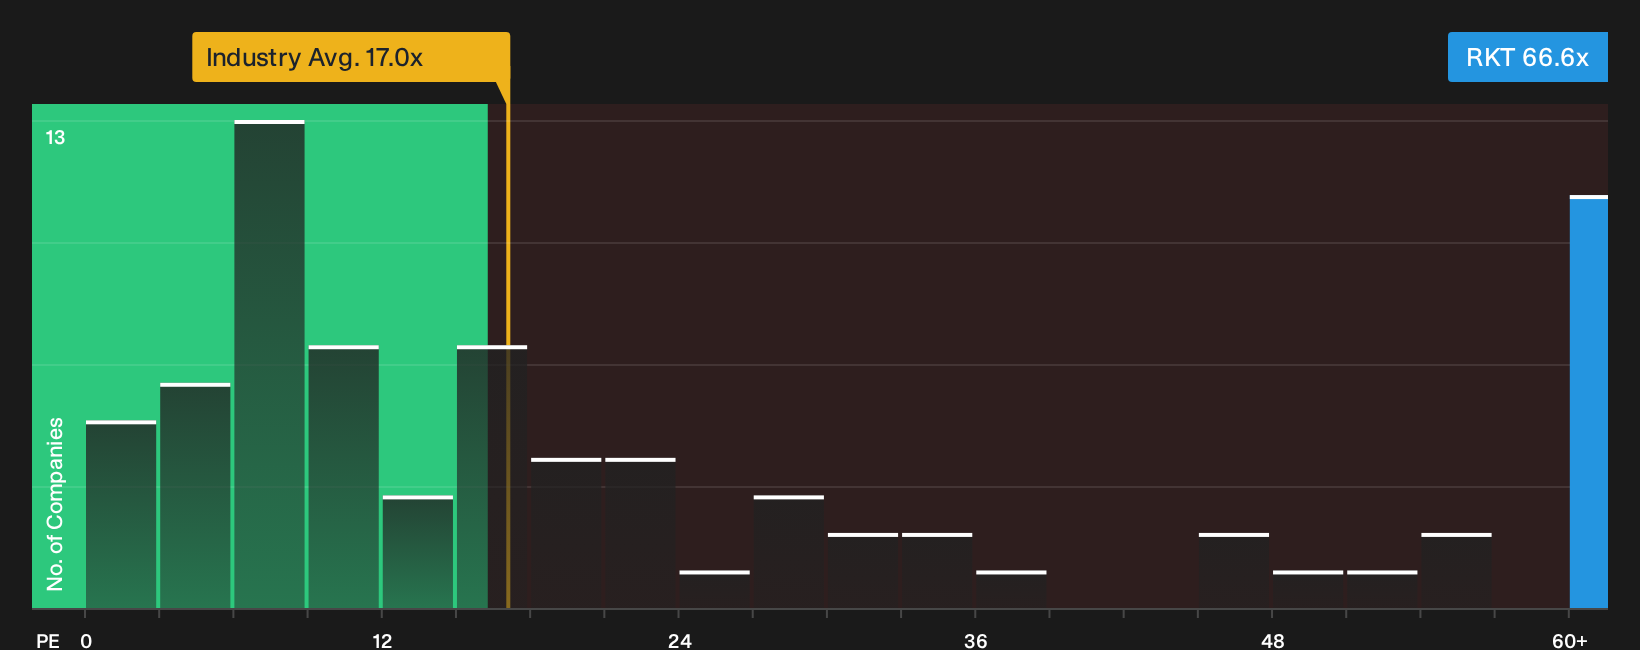
The fair value narrative for Rocket Companies points to $17.27, yet the current P/E of 66.6x tells a different story. That multiple is high compared with the estimated fair ratio of 26.2x, the US Diversified Financial industry on 17x, and peers at 29.5x, which suggests valuation risk if sentiment cools.
If the market edges closer to that fair ratio or to industry and peer levels, pricing could look very different to today. The question then becomes which signal you treat as more important when you weigh Rocket Companies.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views on Rocket Companies so far. If you want to move quickly and rely on your own judgment, weigh up the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Rocket Companies?
Do not stop at Rocket Companies if you want a broader watchlist. Use a few focused stock shortlists to spot opportunities that fit your style faster.
- Target potential upside early by scanning 13 elite penny stocks with strong financials that already pair small size with stronger financial footing.
- Seek value with quality by reviewing the 32 high quality undervalued stocks that combine solid cash generation and supportive balance sheets.
- Prioritise resilience by filtering for 32 resilient stocks with low risk scores that score well on financial strength and lower risk signals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com