
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How French IT Upgrade Win Will Impact CGI Stock Investors
- CGI Inc. reported that France's Ministry of Agriculture, Agri-Food and Food Sovereignty selected the firm, after an open tender, to modernize more than 70 citizen and employee applications using its CGI MAP solution and Digital Innovation Centre in France.
- This French government win highlights CGI's role in large public-sector modernisation work, where requirements span accessibility, user experience, eco-design, resilience and long-term system sustainability.
- Next, the focus shifts to how CGI's French ministry contract, built around CGI MAP driven modernization, could reshape the broader investment narrative.
Scan beyond CGI and see how other listed contractors are pursuing large-scale government digital upgrades with the hand picked 8 resilient stocks with low risk scores.
CGI Investment Narrative Recap
Owning CGI means believing its mix of consulting, managed services and proprietary software can keep turning a large backlog into steady earnings, even as decision cycles in Europe and government budgets move slowly. The French ministry award fits that view because it reinforces CGI’s role in complex public sector work where recurring services usually matter more than one off projects.
In the near term, the key swing factor is how effectively CGI converts booked work into margins while tax rates run in the 26% to 27% range and revenue growth expectations sit in the low single digits. The biggest risk still appears tied to delayed enterprise and government decisions rather than this specific contract, so the news reads as supportive, not transformational.
The French agriculture ministry mandate aligns closely with CGI’s push into application modernization, AI enabled automation and managed IT. It directly references the CGI MAP tooling the group is already weaving into proposals, which indicates how the business is trying to scale its own intellectual property instead of only selling time and materials projects.
For catalysts, that matters because more IP driven modernization work can support recurring services and potentially steadier cash generation alongside the existing backlog of about CA$31.8b. It also intersects with growing demand for secure, resilient public sector systems, although the usual government related risks around budget cycles, rebids and policy shifts still apply to contracts like this one.
What The Current CGI Forecasts Assume
CGI's narrative projects CA$18.0b in revenue and CA$2.2b in earnings by 2029, based on analyst models that tie directly into the kind of long duration government work illustrated by the new French agriculture ministry mandate. This profile assumes revenue growth of 3.1% per year and an earnings increase of about CA$0.5b from the current CA$1.7b base.
Uncover how CGI's fair value indicates a 14% potential upside to its current price that may not last much longer.
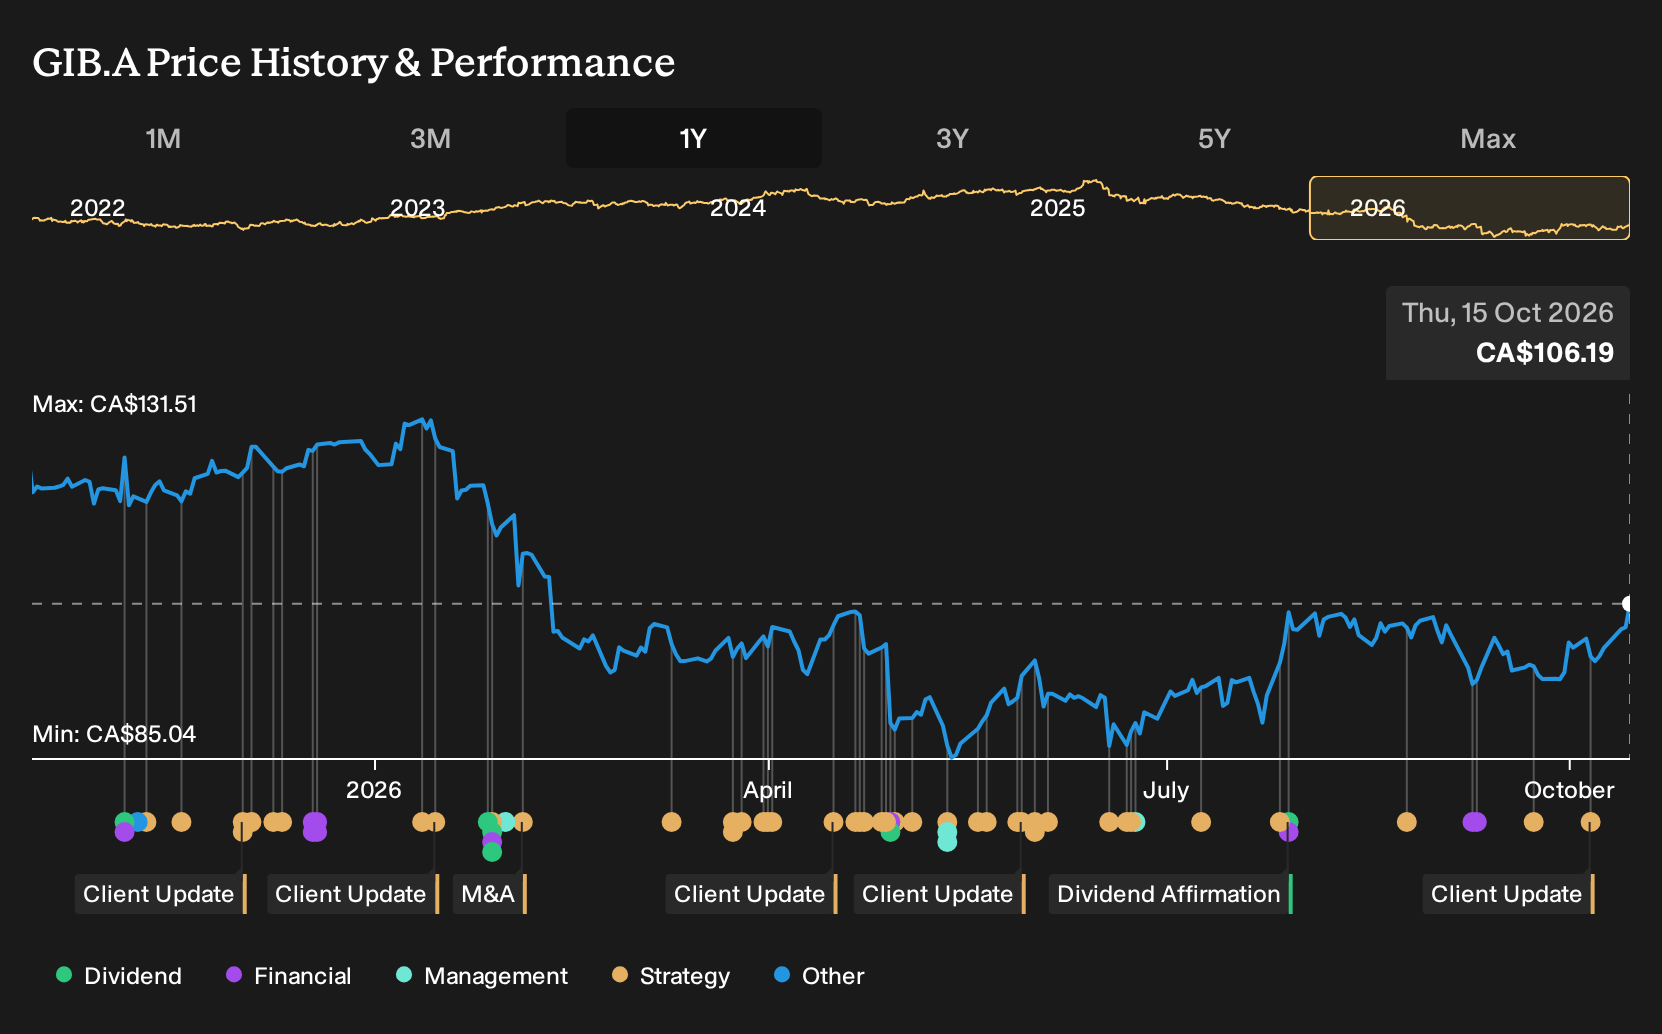
Exploring Other Perspectives
One alternate view says the real swing factor for CGI is AI heavy managed services rather than government tenders like this French ministry win. Some analysts were already penciling in CA$18.1b of revenue and CA$2.3b of earnings by 2029. You can compare those pre news assumptions with your own read and consider how this contract might reshape them.
Explore 4 other CGI fair value estimates, including one that suggests as much as 60% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your CGI research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for CGI. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CGI's overall financial health at a glance.
Looking For More Ideas Beyond CGI?
Once you have formed a view on CGI, it can help to widen the lens and compare it with other listed companies that share similar qualities or offer different types of risk and income profiles. The Simply Wall St Screener is built for that kind of side by side work so you can stress test your thesis against a broader opportunity set.
- For investors focused on capital preservation with measured upside potential, review a curated 8 resilient stocks with low risk scores to see which businesses score well on resilience.
- If the priority is long term compounding at reasonable prices, scan a 10 high quality undiscovered gems that may not yet be widely followed.
- For those who want income on top of potential price appreciation, check out a 3 dividend fortresses that combines higher yields with a focus on durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com