
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Could Earnings Upgrade Alter The Investment Case For Holcim Stock?
- JPMorgan recently placed Holcim on its Positive Catalyst Watch ahead of the October 23 Q3 report, pointing to like for like EBIT growth expectations of 13% compared with existing 10% guidance, despite softer sector volumes and rising costs.
- The focus on Holcim’s ability to manage cost inflation while still targeting higher profitability highlights how its product mix, pricing discipline, and operational execution are being tested against cautious assumptions for European building materials demand.
- We will now see how Holcim's investment narrative could be shaped by JPMorgan's expectation of like for like EBIT outperformance.
Scan how Holcim handles building material headwinds, then size up other resilient players with list of solid balance sheet and fundamentals (202 results) in similar sectors.
Holcim Investment Narrative Recap
Owning Holcim means believing this cement and building solutions group can convert its broad product range and sustainability push into steadier earnings, even when volumes soften and input costs bite. In the short term, the key factor is execution. Investors are watching whether pricing, product mix and efficiency can keep like for like EBIT moving in the right direction against weaker European demand.
The biggest near term risk sits on the cost and regulation side. Higher energy and carbon related expenses could squeeze already lower net margins if price discipline or premium green products do not fully offset that pressure. JPMorgan’s Positive Catalyst Watch raises expectations but does not fundamentally change these operational questions.
With formal company announcements thin around this news, the most relevant reference point is Holcim’s ongoing communication about expanding ECOPact, ECOPlanet and ECOCycle. These ranges matter because they aim for higher value, lower carbon materials where customers may accept stronger pricing, which directly ties into the EBIT resilience narrative that JPMorgan is examining this quarter.
If demand for sustainable mixes holds up while traditional volumes stay softer, that mix shift could become a key earnings driver, especially alongside bolt on building solutions deals. The flip side is clear for you as an investor. If adoption of these products or integration of acquisitions underwhelms, the catalysts around margin strength and future earnings growth could appear far more fragile.
Holcim's current consensus narrative points to CHF 19.1b in revenue and CHF 2.6b in earnings by 2029, based on analysts’ assumption of 6.7% yearly revenue growth and an earnings increase of about CHF 2.2b from CHF 389.0m today.
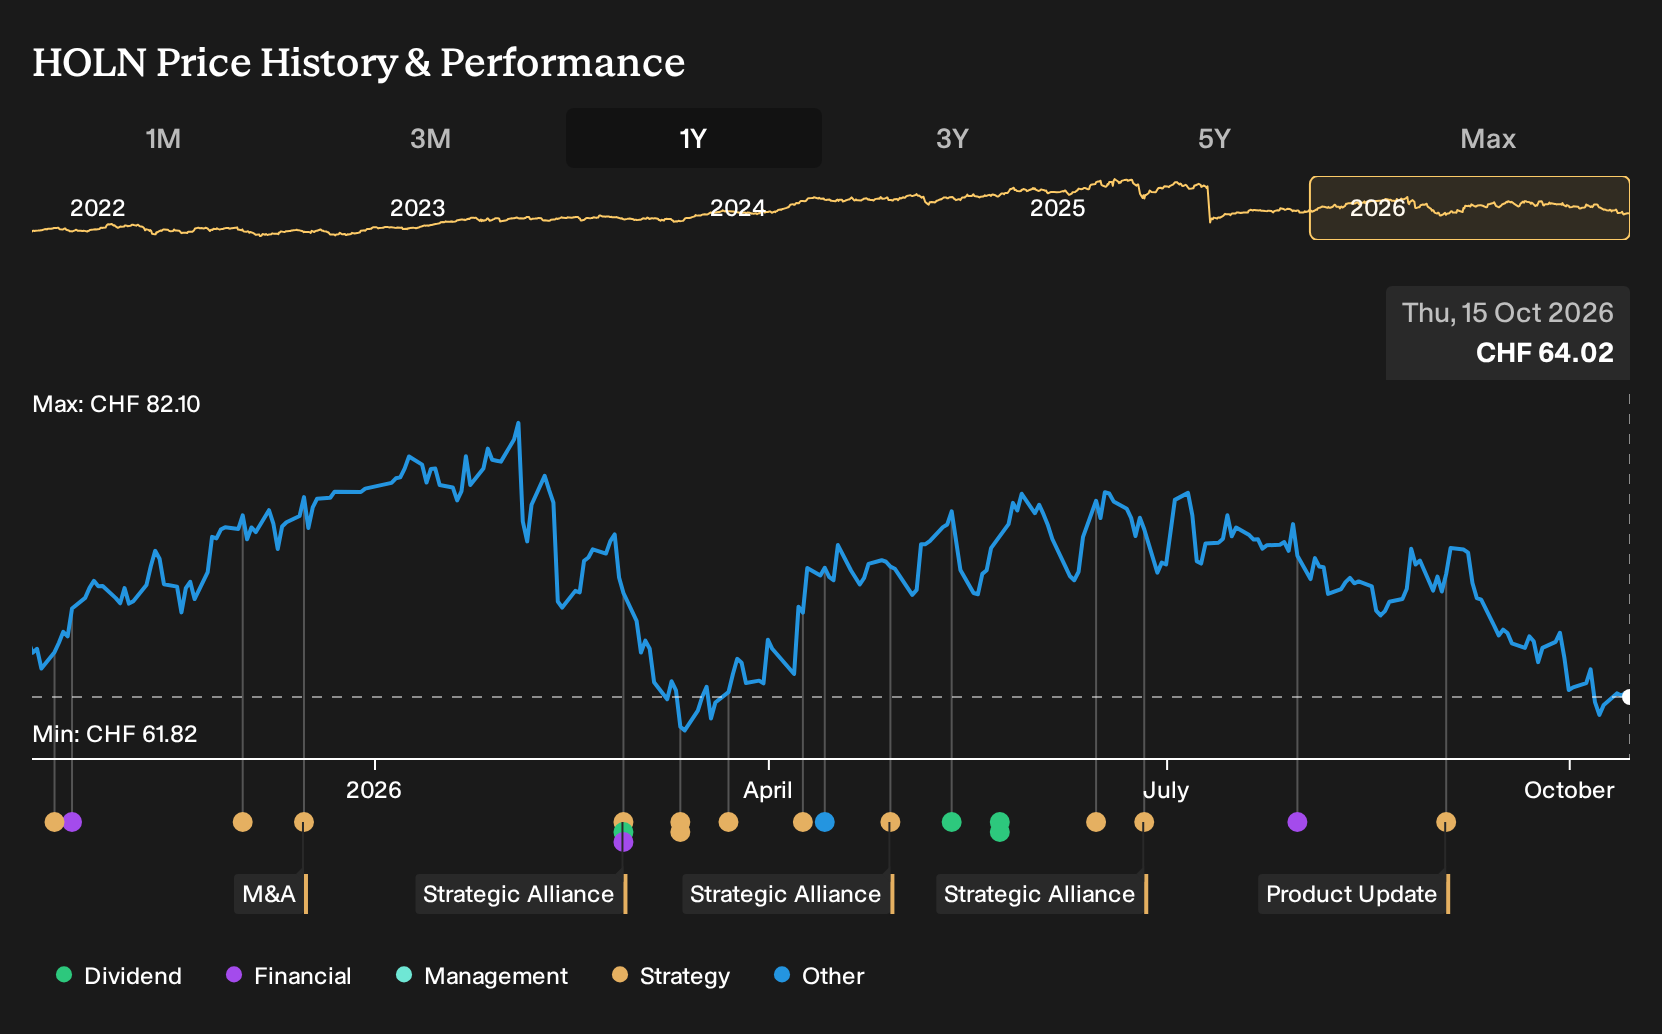
Uncover how Holcim's fair value indicates a 27% potential upside to its current price, which could narrow quickly as expectations catch up.
Exploring Other Perspectives
One alternate view fixates on the legal overhang from the terrorism verdict. That group worries Holcim’s ESG profile could limit premium project wins. These analysts were still pencilling in around CHF 19.4b of 2029 revenue and CHF 2.8b of earnings, yet saw little upside. Use that spread to test your own expectations before this news potentially reshapes the story.
Explore 4 other Holcim fair value estimates, including one that suggests it could be worth just CHF 64.48.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Holcim research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Holcim. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Holcim's overall financial health at a glance.
Looking for more investment ideas beyond Holcim?
If this Holcim update has sharpened your view on building materials, you can apply that same approach across the market by filtering for balance sheets, cash generation and income profiles that suit your own risk tolerance.
- If you want potential mispricings where quality and valuation meet, start with a focused set of 197 high quality undervalued stocks that already clear basic fundamental checks.
- For readers who care more about steadier profiles and capital protection, narrow your search to a 225 resilient stocks with low risk scores that screens for resilience first and upside second.
- If income is the priority and you are weighing Holcim against other payers, compare its profile with a curated group of 220 dividend fortresses that combine higher yields with supporting fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com