
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Indian Growth Stocks To Own In October 2026
AI linked companies have grabbed headlines recently after TSMC reported record profit supported by what it called extremely robust demand for AI chips. This kind of capital spending and computing buildout needs fast growing partners across many parts of the Indian market. Investors looking for future facing growth stories are watching closely. This article highlights three India focused high growth stocks that analysts and management both appear confident about.
The three stocks covered next are only a sample, since the full screen surfaced 37 more India focused companies with equally compelling AI linked growth stories and management commentary that are not covered here.
If you want to identify and analyze the highest conviction ideas right away, head straight into the High Growth High Conviction screener
Rubicon Research (NSEI:RUBICON)
Overview: Rubicon Research is a specialty pharmaceutical company that uses proprietary RubiReten and RubiSRL delivery platforms to develop differentiated complex therapies.
Operations: Rubicon Research generates about ₹19,358 million in revenue from pharmaceutical products including generics, specialty formulations, APIs, and related services.
Market Cap: ₹244.5 billion
For the High Growth High Conviction theme, Rubicon Research matters because its drug delivery platforms give it a focused way to build higher value specialty therapies rather than just chase volume in crowded generic categories.
"Consistent R&D investment at roughly 10% to 11% of revenue, together with a track record of commercialising 88% of approved products, points to a deeper product basket that can support future revenue and earnings visibility."
What really decides how that conviction plays out is how one pressure on future pricing power and margin mix ultimately resolves.
That pricing pressure is only half the story, and the full narrative for Rubicon Research explains how Rubicon Research could still compound through product mix shifts and accelerating pipeline launches.

Atlanta Electricals (NSEI:ATLANTAELE)
Overview: Atlanta Electricals manufactures and sells power and special duty transformers across Indian transmission, infrastructure, industrial and solar projects, with after-sales support.
Operations: The business generates about ₹20,027 million in revenue from manufacturing power and special duty transformers, almost entirely from customers within India.
Market Cap: ₹131.6 billion
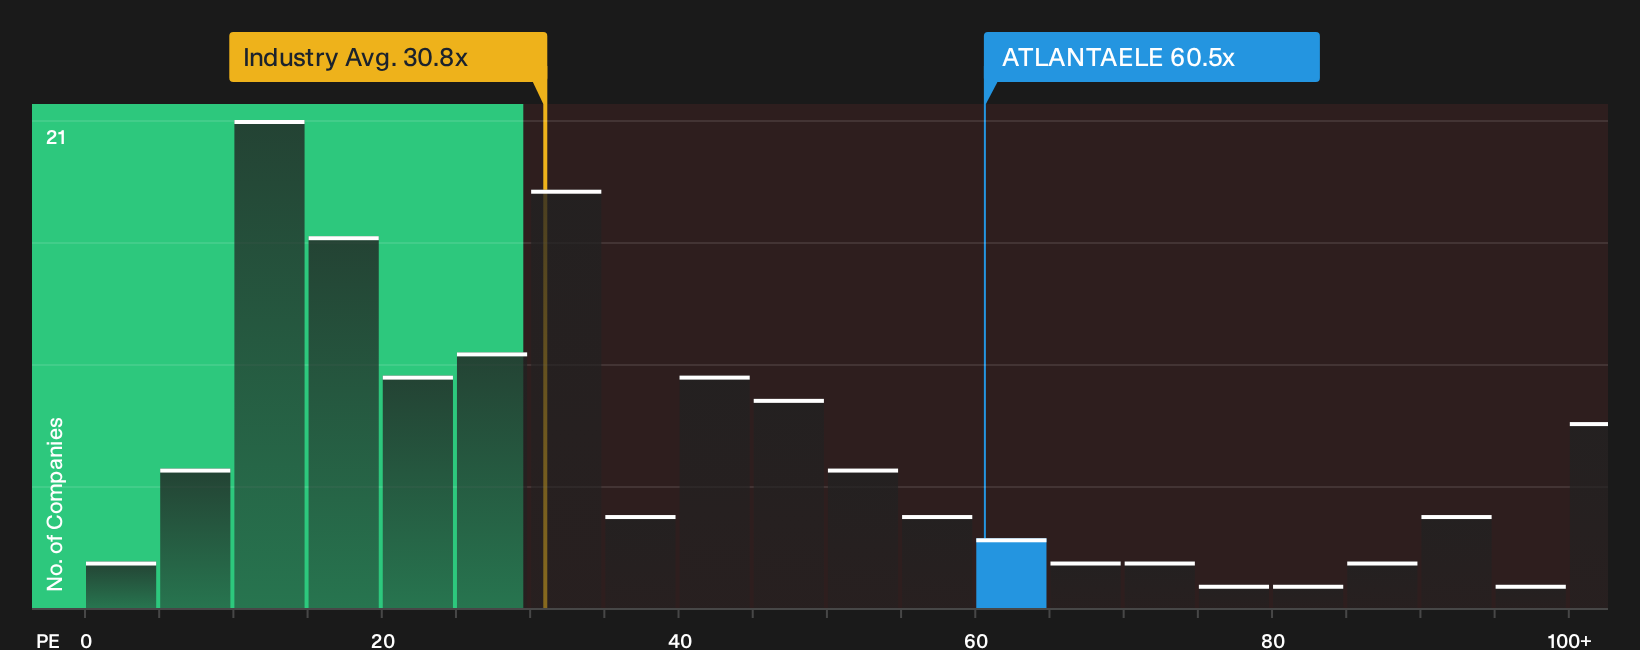
Atlanta Electricals plugs directly into the High Growth High Conviction theme through transformer manufacturing for grid expansion. Earnings were up 74.1% last year and forecast top-line growth is also described as strong. High ROE near 23.4% and improving margins point to quality. However, investors still need to watch what happens if one key pressure on its premium P/E ever shifts.
If that premium ever starts to wobble, the 2 key rewards and 1 important warning sign shows how Atlanta Electricals' quality and risk profile really stack up against those expectations
Bajel Projects (NSEI:BAJEL)
Overview: Bajel Projects runs EPC power transmission and distribution projects, supplying turnkey EHV lines, substations, poles and related electrification infrastructure.
Operations: Bajel Projects earns about ₹27,508 million in revenue from power transmission and power distribution EPC contracts and related infrastructure work.
Market Cap: ₹18.2 billion
Bajel Projects is positioned within the High Growth High Conviction theme through its EHV transmission EPC work, with revenue forecast at 27% a year and earnings projected at 57.67% a year. Recent mega contracts in India and Egypt focus execution risk in a single pressure point that could influence how much of that optimism ultimately benefits shareholders.
That concentration risk is exactly why the 2 key rewards and 1 important warning sign can help you weigh Bajel Projects' contract pipeline against what the market might be missing.

Seeking Alternatives Before The Crowd
Fresh ideas tend to move first. Stocks with real momentum can start moving before most investors notice, while quieter opportunities may remain under the radar for now. Consider doing your research early.
- Target reliable cash generators by running the list of solid balance sheet and fundamentals (202 results) and focus your watchlist on companies that pair sturdy finances with room for the story to develop.
- Research secular themes in digital assets through the 19 cryptocurrency and blockchain stocks and track businesses involved with blockchain-related activity while the story is still forming.
- Focus on consistent income potential with the 220 dividend fortresses and review companies aiming to maintain payouts while prices have not fully reflected that income profile.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com