
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
AI Partnerships Might Change The Case For Lumen Stock
- Lumen Technologies announced collaborations with Snowflake and Eminence Grey to combine its programmable network and fiber footprint with partner platforms for secure AI data movement, governance, and sovereign infrastructure across clouds, data centers, and edge locations.
- The partnerships push Lumen Technologies deeper into AI-centric, higher-value connectivity and security workloads, directly aligned with its pivot away from legacy services toward enterprise data infrastructure that depends on complex, programmable private networks.
- We will examine how Lumen Technologies’ investment narrative is shaped by its new AI-focused data connectivity and sovereignty partnerships.
Lumen Technologies Investment Narrative Recap
To own Lumen Technologies, you need to believe the shift away from shrinking legacy services toward AI oriented private connectivity and platform contracts can eventually outweigh revenue declines and current losses. In the short term, the operational focus still sits on stabilising the top line while keeping capital spending and debt service under control in the face of negative equity and ongoing unprofitability.
The new Snowflake and Eminence Grey collaborations plug directly into that pivot, but they do not immediately change the main near term swing factors. Execution on large AI data infrastructure deals and Network as a Service adoption remains the key potential catalyst. The biggest risk stays the same, that legacy declines and high leverage continue to pressure cash generation.
The Snowflake AI Data Cloud collaboration looks most relevant for near term catalysts. It ties Lumen Technologies’ programmable network and fiber footprint directly into how enterprises move and govern AI data across clouds. That lines up with the existing pipeline of AI driven infrastructure and Platform Connectivity Fiber contracts and could strengthen Lumen’s position with hyperscalers and large enterprises if deployments scale effectively.
What matters operationally is whether this partnership helps fill the network with repeatable, higher value traffic that offsets erosion in Nurture and Harvest legacy products. There is also concentration risk if a small group of large cloud and data center customers ends up driving a significant share of usage. Execution quality on secure, automated private connectivity will likely influence how investors view the sustainability of any future improvement in revenue mix and margins.
Lumen Technologies' narrative projects US$10.4b revenue and US$923.7m earnings by 2029. This projection assumes revenue declines at 4.1% per year and an earnings improvement of about US$1.9b from a loss of US$1.0b today.
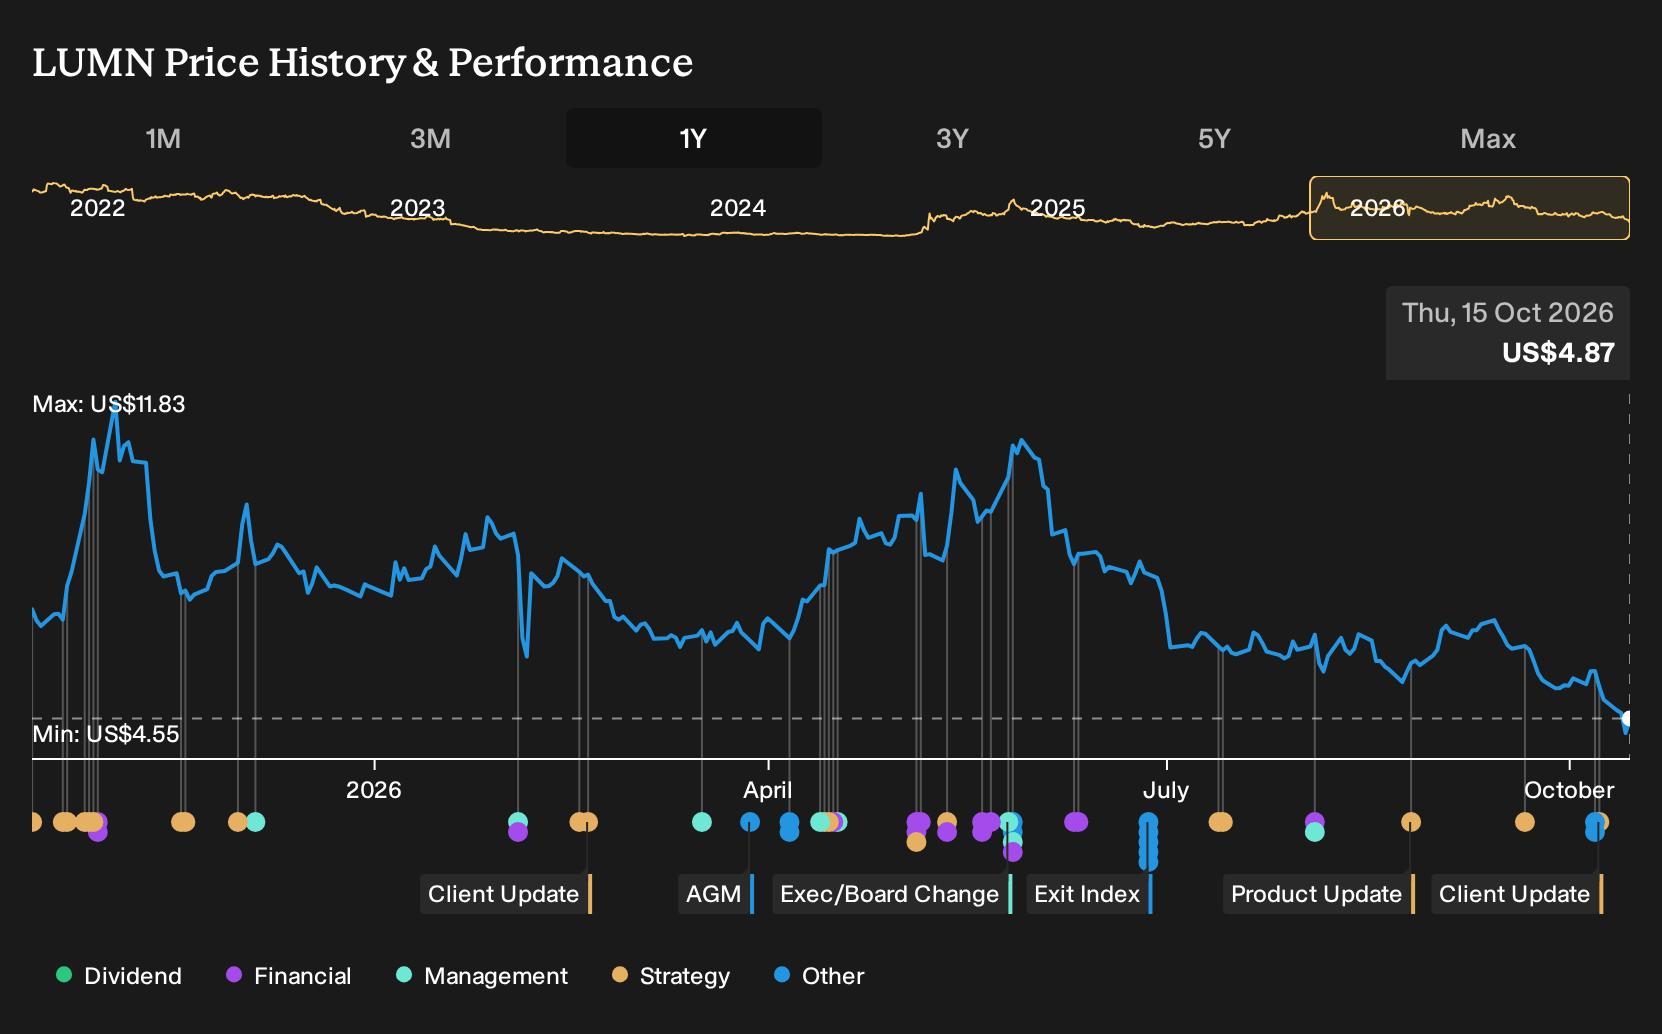
Uncover why Lumen Technologies' fair value indicates a 54% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Some of the most optimistic analysts frame the Eminence Grey sovereign AI partnership as the real swing factor for Lumen Technologies, arguing that sensitive workloads could justify richer contracts. They were already modeling about US$10.7b revenue and US$946.5m earnings by 2029. Those views predate this Snowflake news, so you may see forecasts shift again.
Explore 5 other Lumen Technologies fair value estimates, including one that suggests as much as 85% upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Lumen Technologies research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Lumen Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Lumen Technologies' overall financial health at a glance.
Looking For More Investment Ideas Beyond Lumen Technologies?
Once you have formed a view on Lumen Technologies, it can help to compare it with other companies that match your risk tolerance, income needs, and focus on financial strength. The Simply Wall St Screener gives you a way to filter for those profiles quickly so you can build a watchlist that actually fits your plan.
- If you want potential value opportunities with solid fundamentals, scan through 32 high quality undervalued stocks that already meet strict quality checks.
- If capital preservation and steadier profiles matter more to you, narrow your search using 32 resilient stocks with low risk scores that score well on financial risk metrics.
- If strong balance sheets are your priority, start with a curated list of solid balance sheet and fundamentals (25 results) and compare how each business stacks up on debt and cash.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com