
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors May Respond To Intact Financial (TSX:IFC) Severe Weather Losses
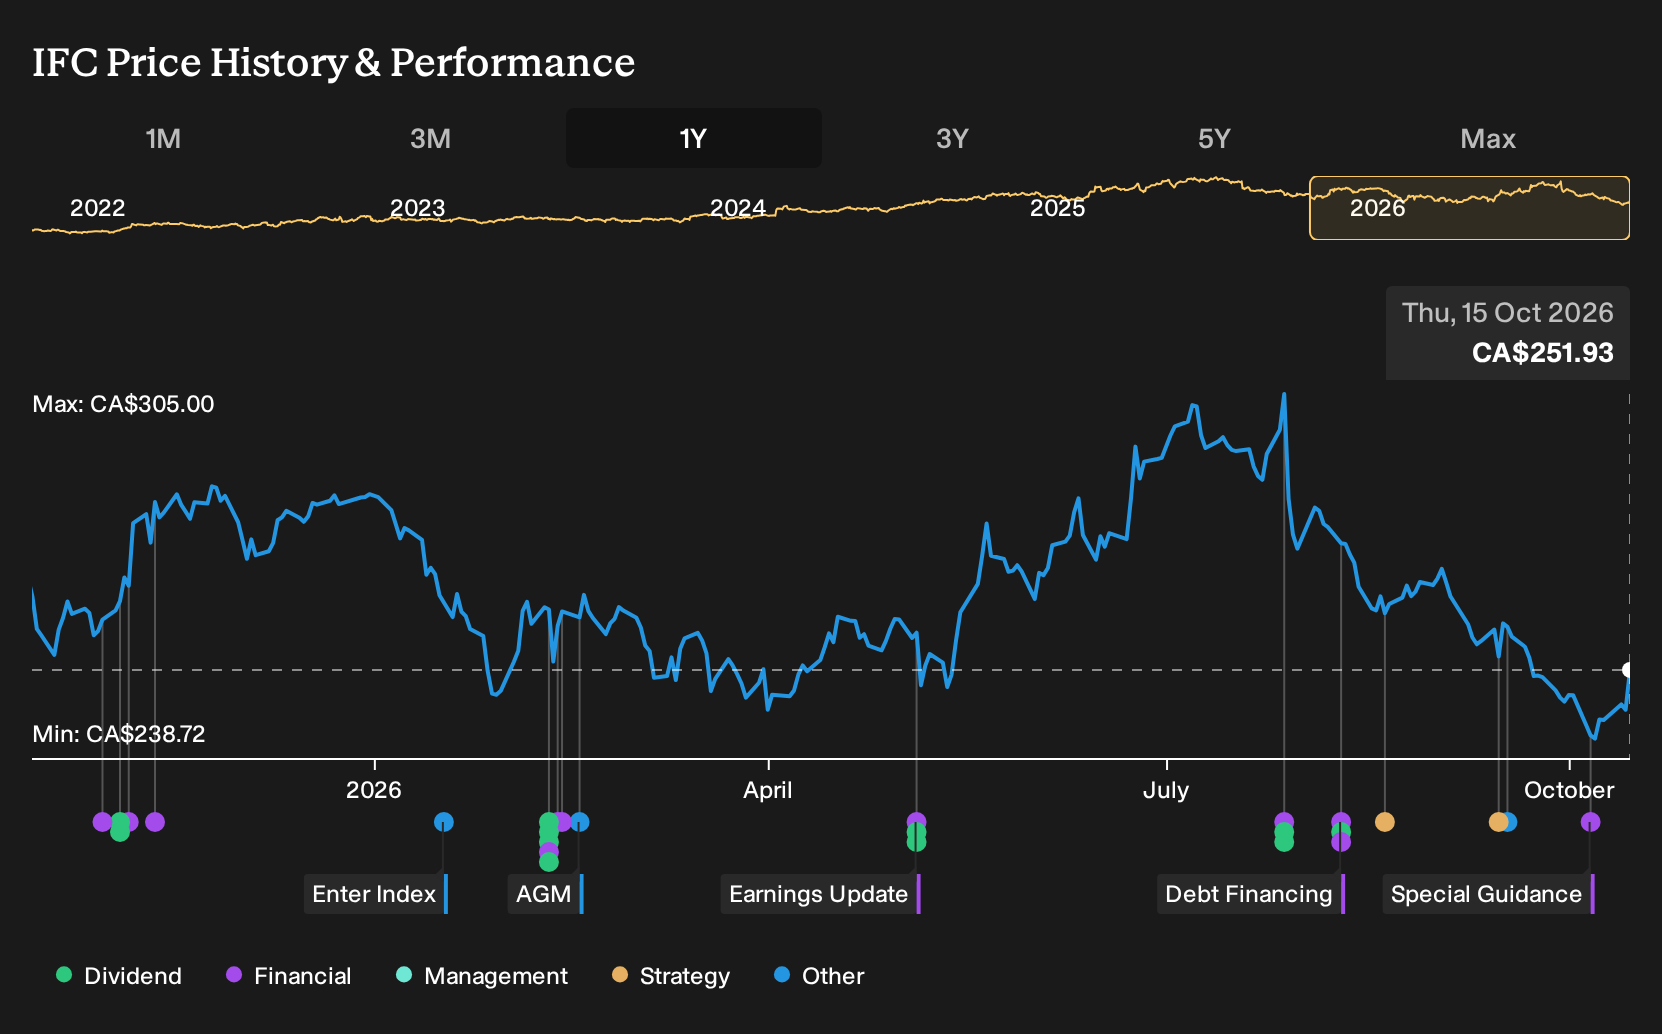
- Intact Financial reported that in Q3 2026 it expects about $660 million in catastrophe losses before tax and after reinsurance, or $2.76 per diluted share after tax, linked to severe storms, flooding, wind damage, and wildfires that affected Canadian personal property and commercial lines.
- The updated catastrophe loss guidance underscores how concentrated weather related claims in key Canadian regions can pressure underwriting performance and test Intact Financial’s ability to price climate risk and manage exposure in its core property and casualty portfolio.
- We will examine how Intact Financial's investment narrative intersects with higher catastrophe losses and what that means for its future risk management practices.
Compare how other insurers and financials handle severe weather risk and balance sheet strength by scanning our hand picked 8 resilient stocks with low risk scores aligned with tougher catastrophe seasons.
Intact Financial Investment Narrative Recap
To own Intact Financial, you need to believe the insurer can turn premium growth, technology investment and underwriting discipline into steady earnings, even when weather turns hostile. The Q3 2026 catastrophe guidance is a hit to near term profitability, but it mainly stress tests pricing, risk selection and reinsurance rather than the entire business model.
The more immediate swing factor is how fast Intact Financial can reprice Canadian property and commercial lines and refine catastrophe exposure after another heavy year. The biggest risk right now is that elevated catastrophe losses, on top of the recent 12 month total of about $1.29b, start to feel less temporary and more structural.
The recent disclosure of roughly $660 million in Q3 2026 catastrophe losses ties directly into earlier commentary about climate related claims pressure and the role of resiliency programs. Management has already been highlighting prevention campaigns, data driven underwriting and On Side Restoration as tools that can help keep loss ratios under control when severe events hit.
For you as an investor, the link between this guidance and those climate resiliency efforts is critical. The more Intact Financial can use its AI models, claims data and restoration capabilities to manage catastrophe volatility, the more room it has to lean on catalysts such as Canadian personal lines growth, expansion in specialty premiums and disciplined capital deployment to support earnings quality over time.
Intact Financial's current analyst narrative points to CA$26.3b of revenue and CA$2.9b of earnings by 2029, with revenue expected to remain fairly flat and earnings projected to decline by about CA$0.3b from CA$3.2b today.
Uncover why Intact Financial's fair value indicates a 26% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly CA$318 to CA$437 per share, so retail opinions on Intact Financial already stretch across a wide band. You are weighing those views against rising catastrophe losses and integration work in the UK&I portfolio, which could influence how sustainably the insurer converts premiums into earnings.
Explore another Intact Financial fair value estimate, including one that suggests the potential for as much as 73% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Intact Financial research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Intact Financial. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Intact Financial's overall financial health at a glance.
Looking for more Intact Financial style investment ideas?
If you want to apply the same kind of disciplined thinking used on Intact Financial to a wider watchlist, the Simply Wall St Screener can help you filter opportunities by balance sheet quality, valuation, and income potential in a few quick passes.
- For investors who care most about resilience, start with a 8 resilient stocks with low risk scores that have historically shown lower overall risk profiles than the broader market.
- If reliable income sits higher on your priority list, focus on companies in the 3 dividend fortresses that may appeal to yield oriented portfolios.
- When you want a mix of strong fundamentals and less crowded ideas, scan through a 10 high quality undiscovered gems that could complement a core holding like Intact Financial.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com