
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
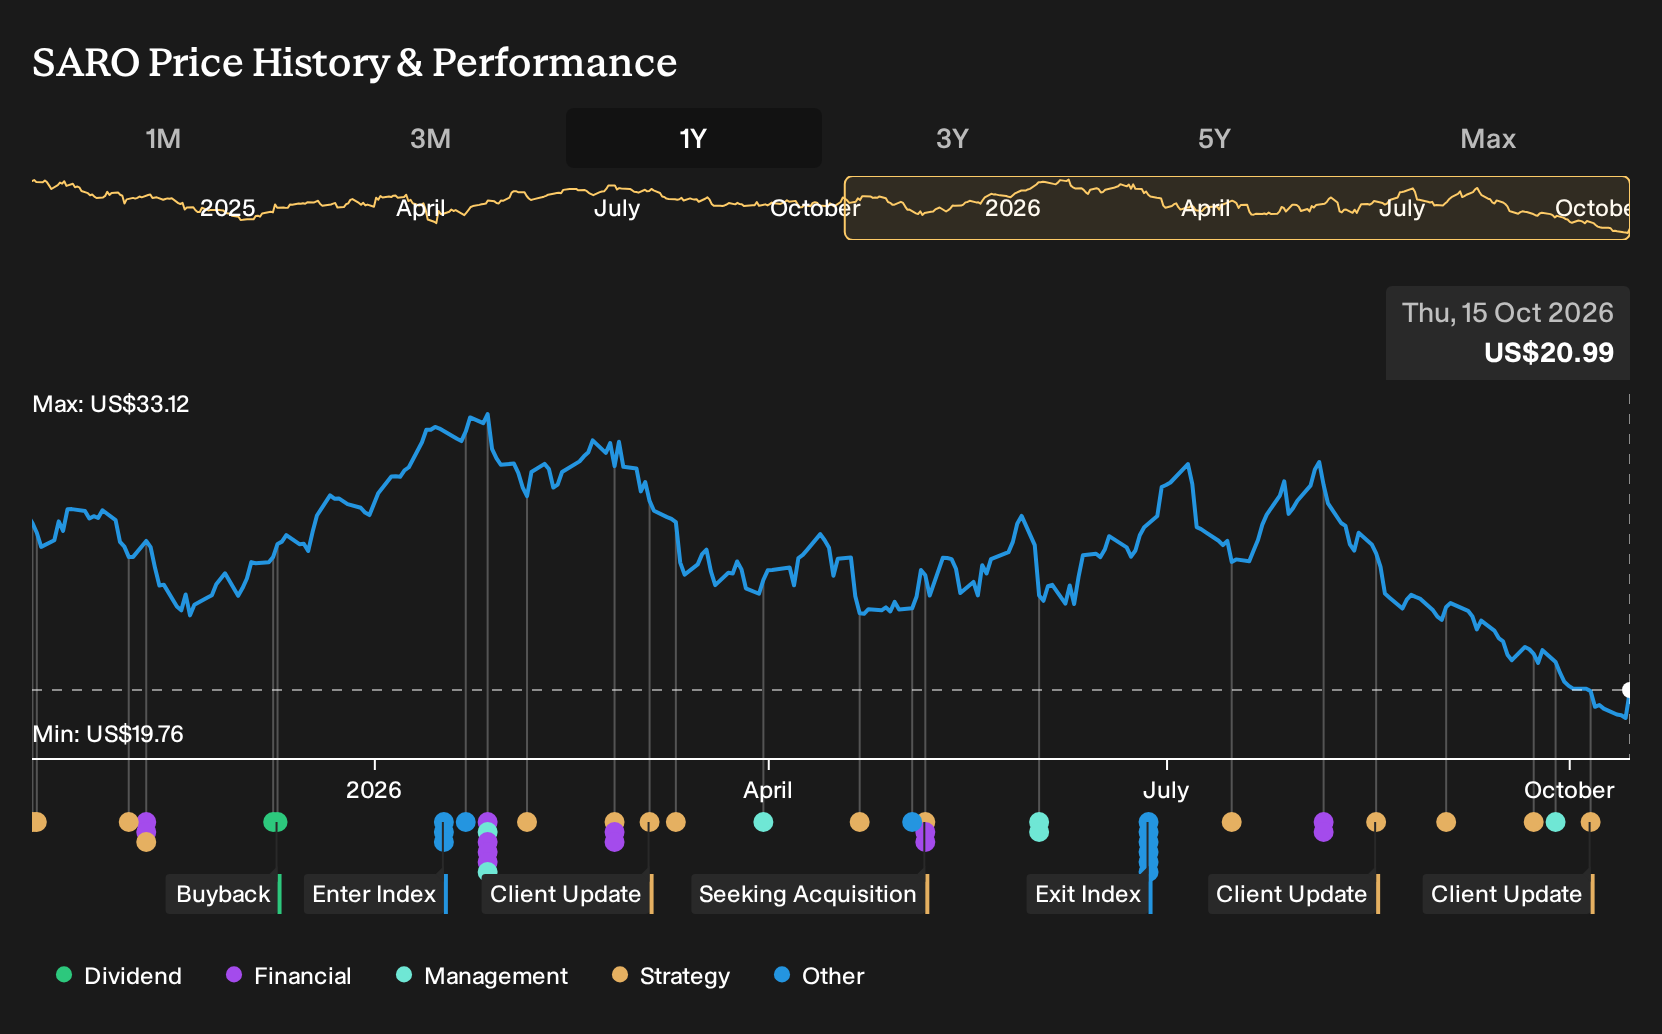
StandardAero Stock In Focus After Air Force Engine Maintenance Award
- In October 2026, StandardAero announced that the U.S. Air Force awarded it work to apply Maintenance Insight predictive diagnostics to the F100-220 engine program, extending these AI, machine learning and digital twin tools to engines powering more than 175 F-15 aircraft.
- The contract broadens StandardAero’s role across five USAF engine types and highlights how its data driven maintenance tools influence readiness, reliability and cost control for critical military fleets.
- We will now explore how StandardAero’s expanded predictive maintenance role on USAF F100-220 engines could influence the broader investment narrative.
StandardAero Investment Narrative Recap
To own StandardAero, you need to believe that its engine services and Component Repair Services can keep turning a long contract pipeline into steady earnings while supply chain friction and parts constraints remain manageable. The USAF Maintenance Insight award fits that view as another proof point in military engines, but it does not fundamentally change the near term story.
The key short term catalyst is still operational execution on LEAP and CFM56 work in DFW, where zero margin programs need to become profitable. The biggest risk remains strained cash conversion and debt coverage if parts shortages or learning curve issues drag on, even as the stock trades well below analyst targets and intrinsic estimates.
The new F100-220 Maintenance Insight work sits alongside earlier USAF projects on T56, J85, TF33 and TF39 fleets, so the pattern matters. This is a growing cluster of defense engine diagnostics that leans directly into what investors already watch most closely for StandardAero: high value, recurring aftermarket work on large installed bases.
For catalysts, that matters because military engine analytics can help smooth shop visit timing, improve work scoping and support better use of existing facilities. It does not remove risks around forgings, castings or LEAP margin uplift, but it gives StandardAero one more operational arena where consistent delivery, not big new bets, is what you are really underwriting.
StandardAero's analyst narrative points to revenues of $7.8b and earnings of $613.4m by 2029, based on an assumed 7.5% yearly revenue growth rate and a move in earnings from $324.0m today. This implies an earnings increase of about $289m by that forecast year.
Uncover why StandardAero's fair value indicates a 64% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate angle to watch is cash conversion. The most bearish analysts were already modeling StandardAero at about 5.8% yearly revenue growth to roughly US$7.5b and earnings of US$602.7m by 2029, using a lower 16.8x P/E. You might see this USAF Maintenance Insight win and wonder if those cautious views need a rethink.
Explore 3 other StandardAero fair value estimates, including one that suggests it could be worth just $31.81!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your StandardAero research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for StandardAero. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate StandardAero's overall financial health at a glance.
Looking for more investment ideas beyond StandardAero?
If the StandardAero story has sharpened your thinking about AI driven maintenance and long-term contracts, it can be useful to line it up against other businesses with very different profiles. The Simply Wall St Screener helps you scan wider, compare trade offs quickly and pressure test whether StandardAero still earns a place on your watchlist once you see what else is out there.
- For investors focused on value and quality together, consider reviewing a 32 high quality undervalued stocks that pair strong fundamentals with prices that analysts see as attractive relative to their financials.
- If resilience matters more than excitement for you, check out a 32 resilient stocks with low risk scores that have sturdier risk profiles and may help balance a portfolio tilted toward more volatile ideas.
- When you want growth potential without throwing away balance sheet discipline, scan a 20 high quality undiscovered gems that combine solid financial footing with underfollowed stories.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com