
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
AI HR Tool Launch Might Change The Case For Investing In Insperity (NSP)
- Insperity announced an AI Agent within its HR360 platform that answers everyday HR questions, links users to the right tools, and is being built to deliver conversational workforce insights such as headcount by location and engagement trends.
- The AI Agent is closely integrated with each client's own HR policies and data, so Insperity is moving beyond generic HR automation toward company‑specific guidance and insight.
- We will now see how Insperity's investment narrative might be affected by the HR360 AI Agent initiative into conversational workforce insights.
Scan how Insperity's AI push compares with other HR and productivity plays by reviewing a curated set of 94 AI infrastructure stocks poised to benefit from similar enterprise adoption themes.
Insperity Investment Narrative Recap
To own Insperity, you need to believe the business can turn a currently loss making model into steadier earnings by lifting profit per worksite employee rather than relying only on headcount growth. The AI Agent inside HR360 fits that story if it leads to better client retention, higher attachment of services and more efficient support.
The near term swing factor still looks tied to healthcare and benefits costs and to how cautious small and mid sized clients remain on hiring. If medical inflation or utilization run hotter than Insperity can reprice, or worksite employees stay soft, the AI news alone probably does not change the risk profile much.
Among recent developments, HRScale with Workday is the one most tightly linked to this AI announcement. HRScale targets mid sized employers and already supports about 8,000 worksite employees, and management has framed it as capable of profitability at or above HR360 levels, which matters if unit growth in the core PEO book stays muted.
Insperity is now weaving AI Agents into both HR360 and HRScale, which ties the product story together. If the HR360 Agent delivers the promised conversational insights and faster workflows, and the same engine flows into HRScale, that could support the broader margin recovery plan that includes repricing, benefit redesign and the updated UnitedHealthcare contract.
Insperity's narrative projects US$7.7b revenue and US$145.3 million earnings by 2029. This assumes 3.7% yearly revenue growth and an earnings increase of about US$161 million from a loss of US$16.0 million today.
Uncover why Insperity's fair value indicates value that is roughly in line with its current price.
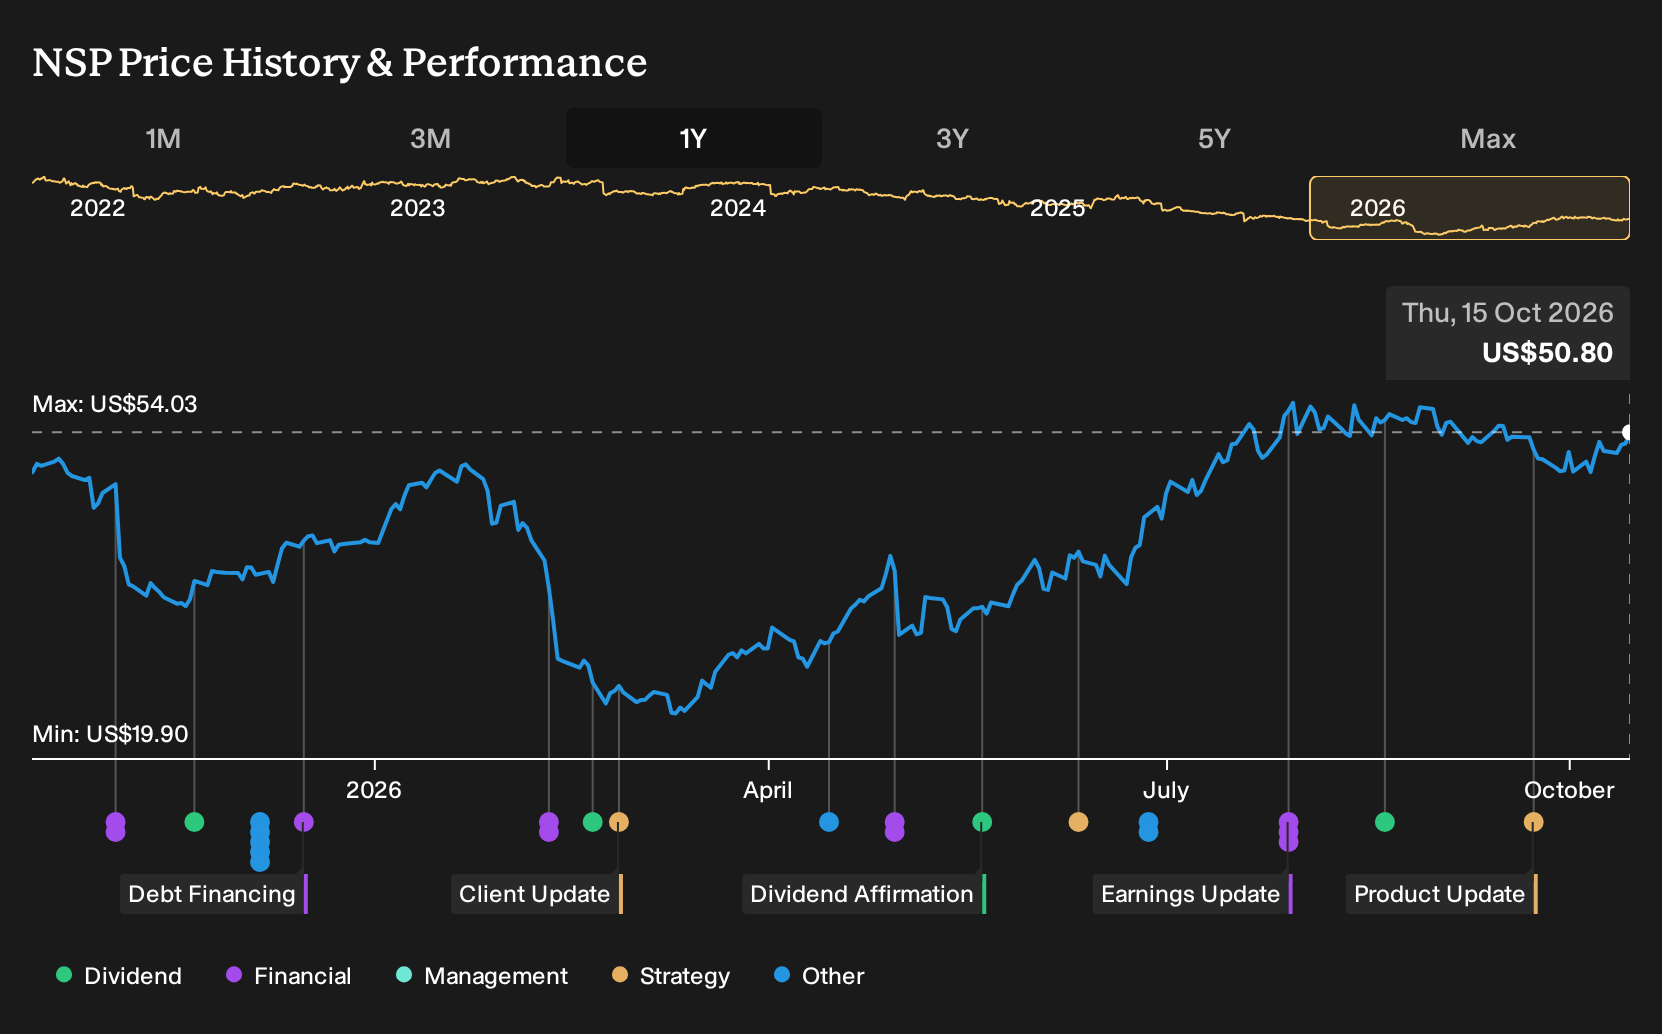
Exploring Other Perspectives
One pushback you will see on Insperity is healthcare cost pressure. The more bearish analysts already baked in a more cautious view, with revenue still modeled at about US$7.7b and earnings of roughly US$121.9 million by 2029, versus consensus at US$145.3 million. Those forecasts predate the AI Agent news, so opinions may evolve as you compare different scenarios.
Explore 3 other Insperity fair value estimates, including one that suggests as much as 25% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Insperity research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Insperity. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Insperity's overall financial health at a glance.
Looking for more investment ideas beyond Insperity?
Once you have a handle on Insperity, it can help to widen the lens and compare it with other companies that fit different risk and income profiles using the Simply Wall St Screener.
- For investors who want potential mispricing plus quality fundamentals, review a curated set of 32 high quality undervalued stocks that might offer a more attractive entry point than broad market benchmarks.
- If reliability and capital preservation matter most to you, shift attention to a 32 resilient stocks with low risk scores that score well on balance sheet strength and business stability.
- Income focused investors can round out their watchlist by scanning a pool of 8 dividend fortresses that combine higher yields with detailed payout and coverage metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com