
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors Are Reacting To Rogers Communications (TSX:RCI.B) Anti Fraud Platform Launch
- Rogers Communications is involved in the launch of the Cross-Sector Anti-Fraud Exchange, a shared fraud intelligence platform developed by EnStream with major Canadian banks and telecom operators, following earlier pilot work between Rogers and CIBC.
- The CSAFE platform uses shared data, AI and machine learning to target repeat fraud, which can influence Rogers Communications' fraud costs, customer trust and digital security positioning across its connectivity and media services.
- Attention now shifts to how Rogers Communications' role in CSAFE and its AI driven fraud intelligence platform could reshape the investment narrative.
Scan how Rogers Communications' fraud intelligence push compares with other companies prioritizing digital resilience through 8 resilient stocks with low risk scores in the current market.
Rogers Communications Investment Narrative Recap
To own Rogers Communications, you need to be comfortable with a slow growth, capital heavy telecom and media group that is working through regulatory pressure, debt from past deals and a wireless market that looks mature. The near term story still leans on execution in 5G, satellite to mobile services and ongoing cost work in Cable while keeping churn in check.
The CSAFE fraud platform and broader fraud intelligence push matter more for reputation and operating costs than for near term financial catalysts. They do not change the biggest swing factors right now, which are earnings pressure, interest coverage on its borrowings and the risk of further regulatory decisions affecting pricing and returns on network spend.
The Dateline Canada launch on Citytv sits squarely in that context. Rogers Communications is trying to get more value out of its Media assets by leaning on recognizable formats and using Rogers Studios to produce content that can hold audience attention as traditional TV viewing fragments and cord cutting weighs on legacy video revenue.
If execution on Dateline Canada is solid, it could support advertising relationships, streaming engagement on Citytv+ and cross promotion with sports and other media properties. The operational stakes are clear. Media needs to justify its place alongside Wireless and Cable, and fresh franchises give management one more lever to offset the structural pressure facing traditional broadcast and pay TV economics.
Rogers Communications' current analyst narrative points to revenues of CA$23.7b and earnings of CA$2.4b by 2029. That profile builds on an assumed 1.6% yearly revenue growth rate and an earnings decline of CA$3.8b, from CA$6.2b today to the 2029 forecast level.
Uncover how Rogers Communications' fair value indicates a 31% potential upside to its current price, which could narrow quickly.
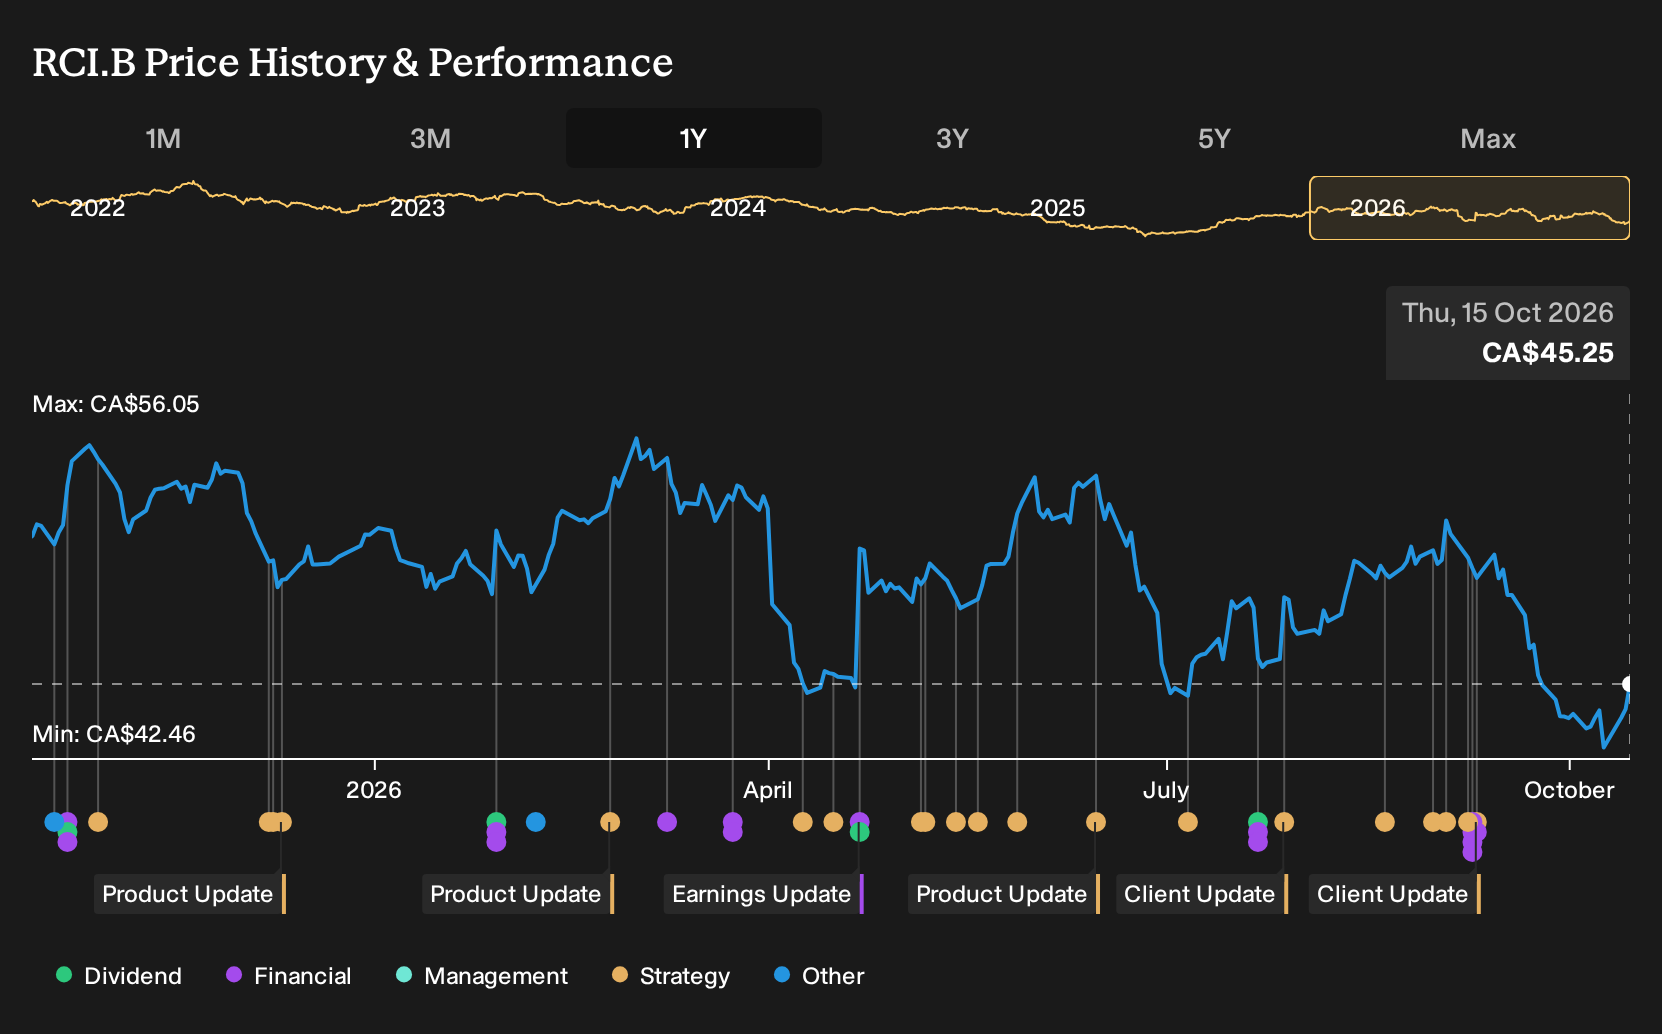
Exploring Other Perspectives
Some of the most optimistic analysts frame Rogers Communications less as a slow growth utility and more as a media and cash flow story. Before this fraud intelligence and Dateline Canada news, that group was working off assumptions of CA$24.0b in 2029 revenue and about CA$2.1b in earnings. You might see those views shift if CSAFE and new content change how media and security strength are valued.
Explore 4 other Rogers Communications fair value estimates, including one that suggests potential upside of up to 440% from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Rogers Communications research is our analysis highlighting 5 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Rogers Communications. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Rogers Communications' overall financial health at a glance.
Looking for more Rogers Communications investment ideas and peers?
If you want to put Rogers Communications in context, it helps to line it up against other stocks with different risk profiles, balance sheets and income characteristics. The Simply Wall St Screener can surface a range of alternatives so you can build a watchlist that actually fits how you like to invest.
- If capital preservation comes first for you, start with a basket of companies that score well on resilience through the 8 resilient stocks with low risk scores.
- Income focused investors can hunt for yield by scanning a curated set of higher payout opportunities using the 3 dividend fortresses.
- For those hunting for quality at a reasonable price, broaden your research with a hand picked universe of potential bargains via the 6 high quality undervalued stocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com