
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Learn Why The Bull Case For PulteGroup (PHM) Could Change Following Weaker Quarterly Results
- PulteGroup expanded its Explore by Del Webb brand with a planned 900 home community at Jordanelle Ridge in Utah, featuring resort style amenities and year round recreation access, informed by Del Webb’s long running active adult experience.
- The Utah project deepens PulteGroup’s tilt toward lifestyle and active adult style communities, even as analysts currently expect softer near term earnings and revenue.
- This article examines how PulteGroup's investment narrative is shaped by the Jordanelle Ridge expansion alongside expectations for weaker upcoming earnings.
Scan beyond PulteGroup and this Utah lifestyle push by reviewing hand picked list of solid balance sheet and fundamentals (25 results).
PulteGroup Investment Narrative Recap
To own PulteGroup, you need to be comfortable with a homebuilder that leans into higher priced move up and active adult communities while managing choppy demand. The Jordanelle Ridge project fits that mix shift but does not change the near term reality of softer closings, lower average selling prices and pressure on home sale revenues.
The key short term swing factor remains how effectively PulteGroup balances incentives, build to order execution and cost control against affordability constraints. The biggest risk is that weak demand and heavy discounting persist, which would keep margins and earnings under pressure even as lifestyle driven communities continue to roll out.
The fresh announcement that Explore by Del Webb is expanding to Jordanelle Ridge matters because it reinforces the tilt toward active adult and lifestyle focused projects. This aligns with earlier Explore communities in Florida, Ohio and California and supports the idea that mix and amenities, rather than deep discounts alone, can attract buyers.
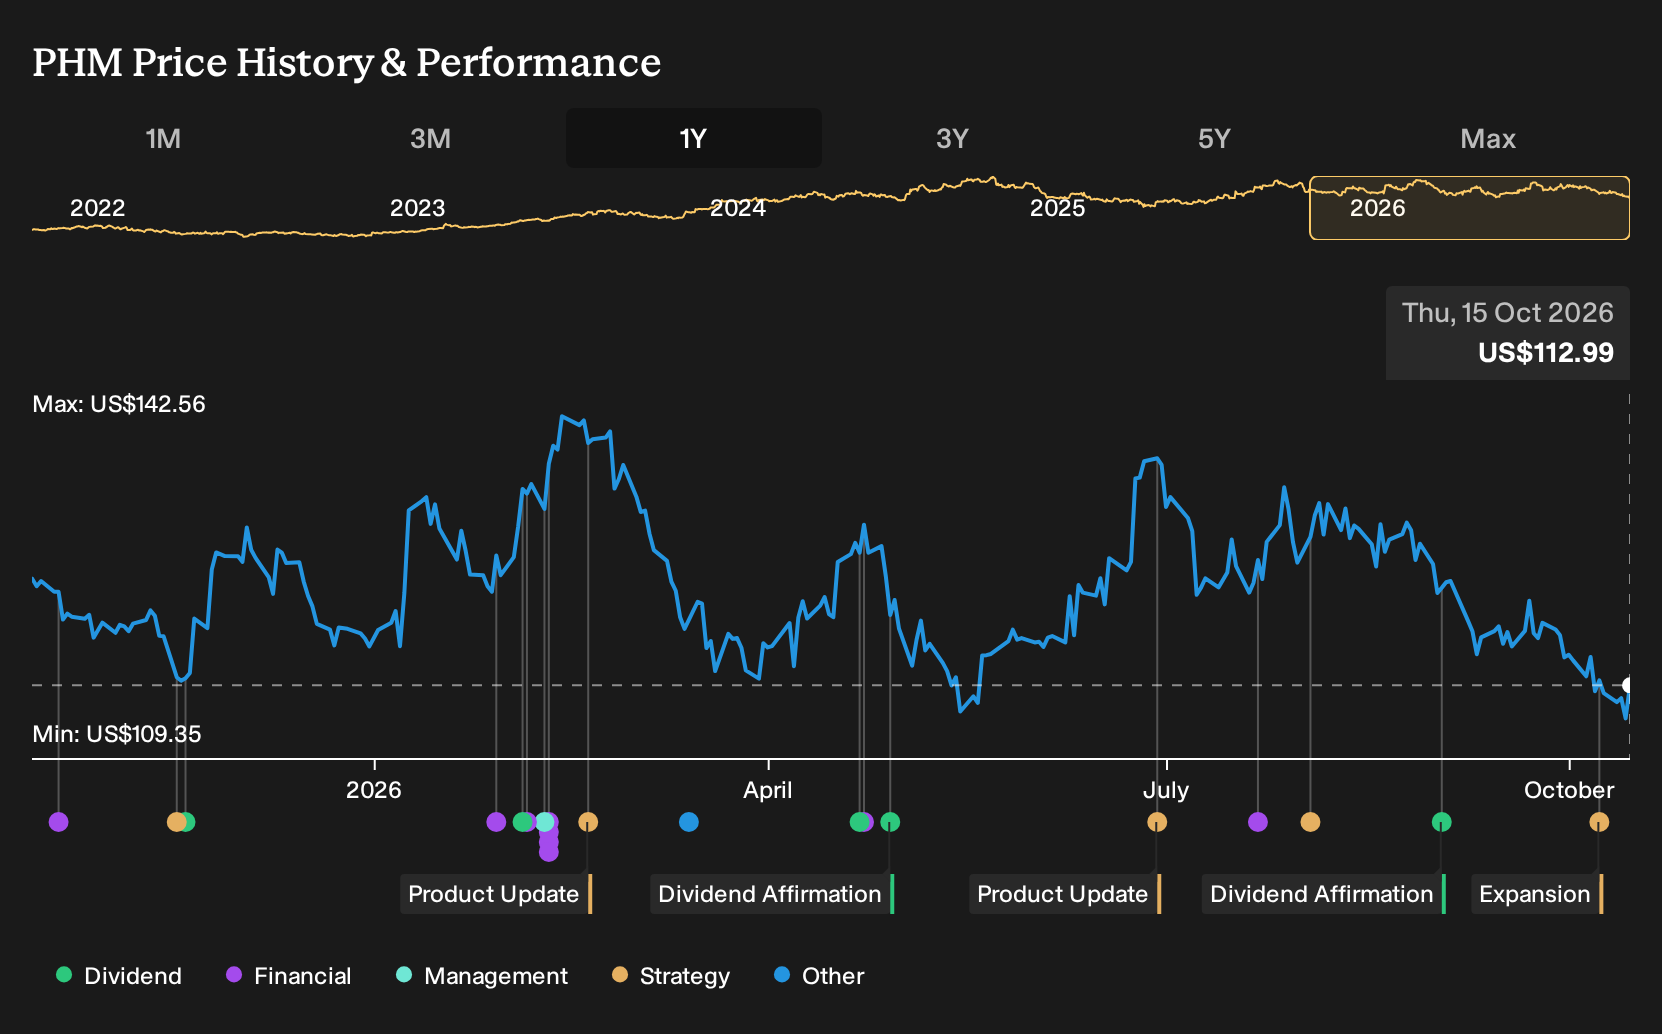
For catalysts, the question is whether these resort style communities with clubhouses, recreation access and curated amenities can offset regional softness and high incentive levels. Analyst expectations for a year over year earnings and revenue decline into the October 22 earnings date keep execution risk front and center while investors watch how quickly new projects translate into contracted sales.
PulteGroup's outlook forecasts US$18.1b in revenue and US$2.2b in earnings by 2029. This is based on an assumed 3.4% annual revenue growth rate and an increase in earnings of about US$0.3b from US$1.9b today.
Uncover how PulteGroup's fair value indicates a 22% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view says the real risk for PulteGroup is that all this active adult and Explore community momentum still leaves earnings flat. The most cautious analysts were modeling only about 2.4% annual revenue growth to roughly US$17.6b and earnings stuck near US$1.9b by 2029, so Jordanelle Ridge could eventually nudge those expectations in either direction.
Explore 5 other PulteGroup fair value estimates, including one that suggests as much as 7% downside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your PulteGroup research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for PulteGroup. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate PulteGroup's overall financial health at a glance.
Looking for more investment ideas beyond PulteGroup?
Once you understand where PulteGroup sits in your portfolio, it often helps to compare it with a few different types of opportunities using a structured stock screener, rather than a watchlist built on headlines alone.
- If you want income to play a bigger role in your returns, scan through 8 dividend fortresses that combine yield with balance sheet support.
- For investors who prefer to keep risk in check, narrow your search to 32 resilient stocks with low risk scores that score well on resilience and financial strength.
- When you are hunting for ideas that the wider market may not be focused on yet, cast a wider net across 20 high quality undiscovered gems with solid fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com