
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Does Special Meeting Rights Proposal Change The Bull Case For Avnet (AVT)?
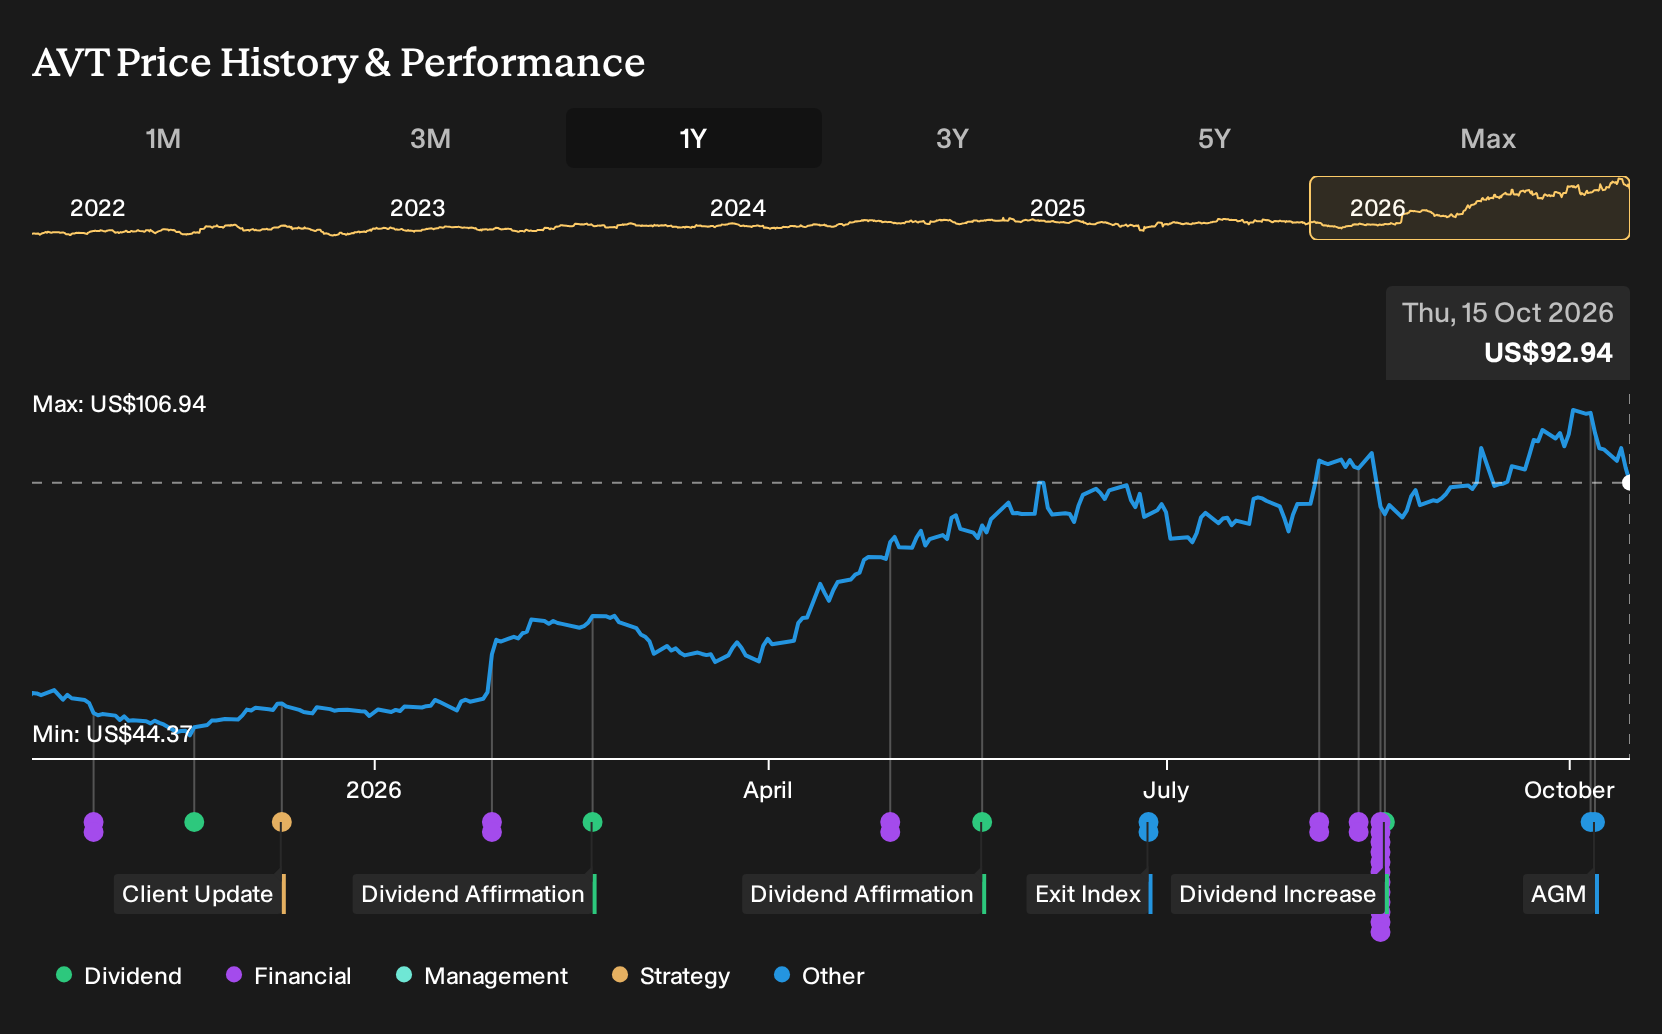
- Avnet disclosed that it filed a definitive proxy statement on 6 October 2026 urging shareholders to vote against a proposal that would let holders of a combined 10% of outstanding common stock call an online special shareholder meeting.
- The move signals management’s preference for tighter control over how and when investors can force governance debates. This could shape how quickly shareholder concerns influence Avnet’s capital allocation and operating priorities.
- We will look at how Avnet's investment narrative is affected by shareholder pushback over 10% special meeting rights in the proxy.
Compare how Avnet handles shareholder control with a curated group of companies where investors are already pushing for sharper governance in our 32 resilient stocks with low risk scores.
Avnet Investment Narrative Recap
To own Avnet, you need to be comfortable with a distributor that leans into complex supply chains, AI and data center demand, and a mix that still pressures gross margins as Asia and memory exposure remain meaningful. The recent proxy fight over 10% special meeting rights sits in the background of this but does not alter the near term operational drivers around backlog, pricing, and capacity.
The more immediate swing factor remains whether Avnet can keep expanding operating margins and return on working capital while memory pricing and book to bill strength hold up. The biggest current risk is that mix and pricing reset, especially in memory and Asia, which could cap earnings even if the governance debate cools down.
The definitive proxy filed on 6 October 2026 is the clearest recent development tying governance to the investment story. Management is urging investors to vote against giving 10% holders the ability to call an online special meeting, which effectively keeps tighter control over when capital allocation and risk appetite get debated formally.
For you, the practical link runs through execution on existing catalysts. If operating income continues to track faster than sales, Farnell keeps working toward double digit margins from 9% in Q4 FY26, and AI or data center exposure near 10% to 15% of revenue stays intact, then the special meeting proposal mainly sits as a governance watchpoint rather than an operational shock.
What The Current Forecasts Assume For Avnet
Avnet's stock story today leans heavily on a fairly tight analyst playbook. Consensus models point to revenue climbing at about 10.3% a year over the next three years, with earnings moving from US$334.4 million today to roughly US$1.4b by 2029. That implies earnings need to grow a bit more than 4x in absolute dollar terms on this timeframe, helped by profit margins shifting from 1.2% to 3.7% if the projections line up with reality.
Avnet's narrative projects US$37.1b revenue and US$1.4b earnings by 2029. This requires 10.3% yearly revenue growth and an earnings increase of a little more than 4x from US$334.4 million today.
Forecasts also build in a modest lift in the share count, with analysts penciling in share growth of around 0.91% a year for three years. At the same time, the models assume the market will not keep paying today's valuation multiple. The consensus framework uses a future P/E of 8.6x on those 2029 earnings compared with 26.2x today and below the 30.3x cited for the broader US electronic industry. That mix of faster profit growth and a lower assumed multiple is doing a lot of work in the math behind the current fair value debates.
Uncover how Avnet's fair value indicates a 14% potential upside to its current price. This opportunity could narrow quickly if sentiment catches up.
Exploring Other Perspectives
For a different lens on Avnet, focus on the bullish catalyst of AI and data center demand. Before this governance fight surfaced, the most optimistic analysts were already penciling in US$38.0b of revenue and US$1.6b of earnings by 2029. You can treat those richer assumptions as one end of a wide opinion range that may shift as the 10% meeting debate plays out.
Explore 2 other Avnet fair value estimates, including one that suggests as much as 29% upside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Avnet research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Avnet. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Avnet's overall financial health at a glance.
Looking for more Avnet style investment ideas?
If Avnet has put governance and capital discipline on your radar, it might be worth widening your watchlist with stocks that fit different risk and balance sheet profiles using the Simply Wall St Screener.
- For investors who want resilience first, focus on companies with stronger financial footing and cleaner leverage profiles through a curated list of solid balance sheet and fundamentals (25 results).
- If income is your priority, scan for businesses offering higher yields and more robust payout histories by reviewing the 8 dividend fortresses.
- To search for future compounders before they hit the mainstream, filter for under-followed companies with stronger fundamentals via the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com